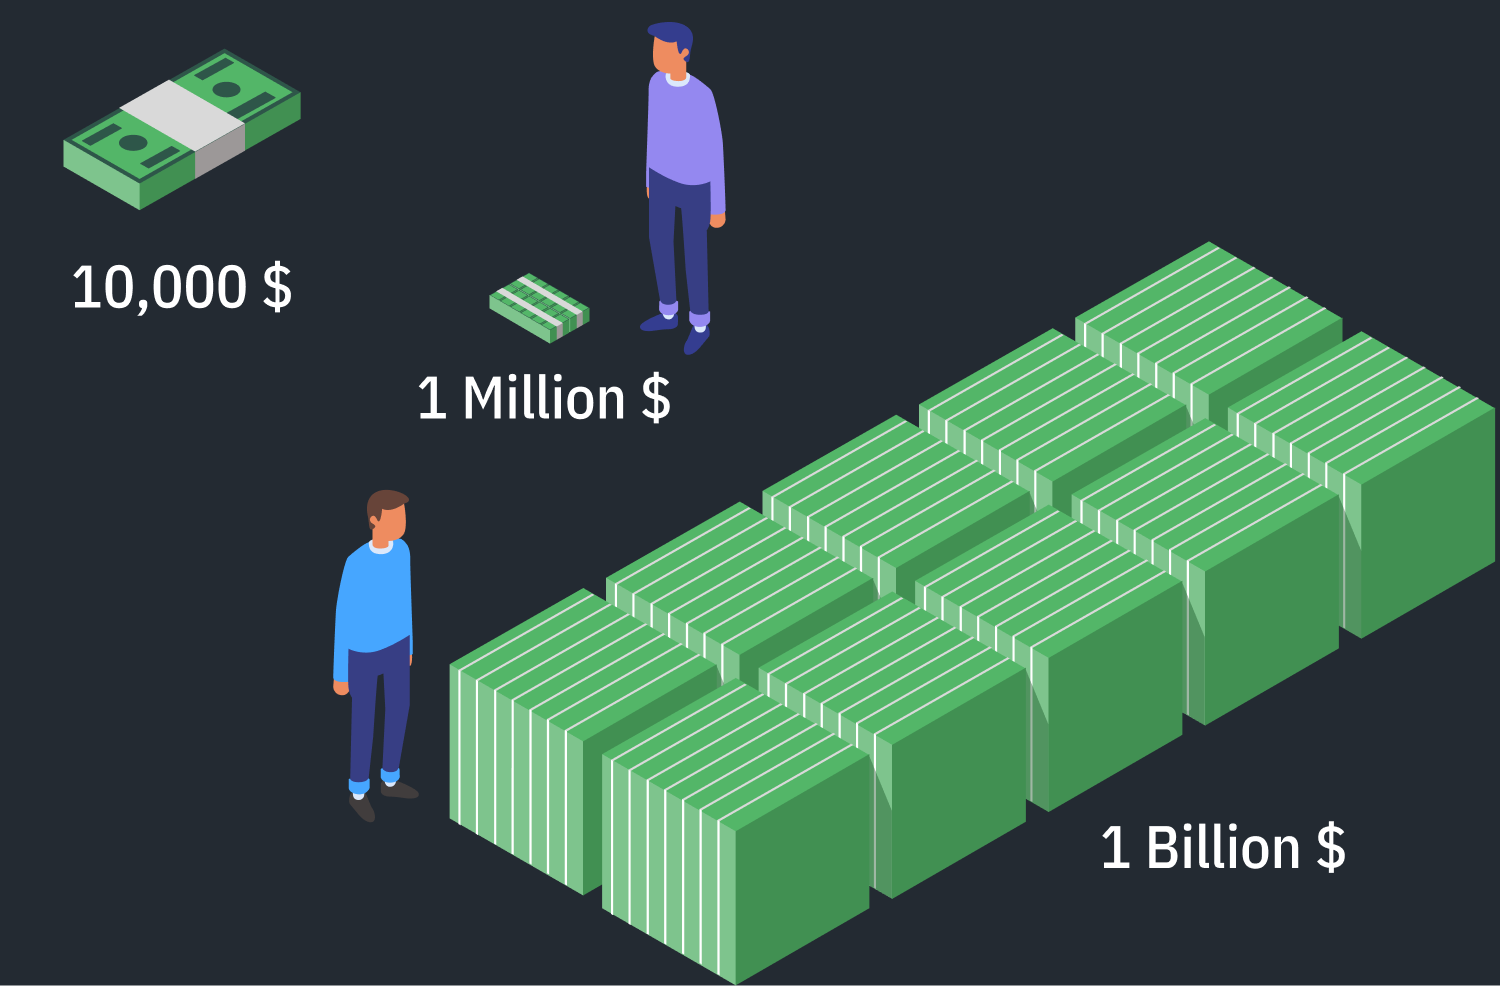
Accumulating or managing 1 million dollars represents a significant financial milestone that changes a person's relationship with money, security, and long-term planning. While traditionally viewed as the ultimate threshold of wealth and independence, a million dollars today functions differently due to inflation, cost of living variations, and changing economic landscapes. Achieving, maintaining, or evaluating this sum requires a clear understanding of purchasing power, investment strategies, tax implications, and psychological shifts.
The Historical and Modern Reality of a Million Dollars
The perception of a million dollars has evolved drastically over the past century. Popularized by game shows, literature, and cultural milestones, the figure long stood as the definitive symbol of being rich. However, economic realities have shifted the practical utility of this sum.
Inflation and Purchasing Power
Inflation steadily erodes the purchasing power of fiat currency. A dollar from several decades ago bought significantly more goods and services than it does today. Consequently, 1 million dollars in the current economic environment does not purchase the same basket of goods, real estate, or lifestyle luxuries it did in the mid-to-late twentieth century.
When evaluating what a million dollars can achieve, economists and financial planners look at real purchasing power rather than nominal value. While it remains a substantial amount of capital, its longevity depends entirely on how it is deployed, where an individual lives, and their annual expenditure requirements.
The Psychological Threshold
Beyond the math, 1 million dollars occupies a unique space in human psychology. It acts as a mental benchmark for success, security, and freedom from immediate financial distress. Crossing this line often triggers shifts in personal goals, risk tolerance, and career paths. Yet, behavioral finance notes that individuals frequently suffer from lifestyle inflation once they reach major milestones, scaling up their expenses to match their new asset level, which can neutralize the safety net the money was intended to provide.
Earning, Saving, and Accumulating 1 Million Dollars
Building a net worth of 1 million dollars requires a disciplined approach combining income generation, consistent saving, and strategic asset allocation. For most individuals, achieving this milestone is a gradual process rather than a sudden windfall.
The Power of Compound Interest
Time is the most critical variable in wealth accumulation. Through the mechanism of compound interest—earning returns on both the initial principal and the accumulated interest or gains from prior periods—smaller, consistent contributions can grow into substantial sums over decades.
- Consistency: Regular contributions to investment accounts smooth out market volatility through dollar-cost averaging.
- Time Horizon: Starting early allows investments to weather multiple market cycles and leverage exponential growth curves.
- Rate of Return: The chosen asset classes (stocks, bonds, real estate) dictate the average annual growth rate, balancing risk against potential reward.
Common Paths to Seven Figures
Individuals typically reach the 1-million-dollar mark through several primary avenues:
- Corporate Careers and Professional Services: High-earning professions, equity compensation, and steady corporate advancement combined with maxed-out retirement accounts.
- Entrepreneurship and Business Ownership: Building and scaling a privately held business, which can yield liquidity events or steady cash flow.
- Real Estate Appreciation and Leverage: Acquiring residential or commercial property, utilizing mortgages to build equity, and benefiting from long-term market appreciation and rental income.
- Disciplined Investing: Long-term participation in broad-market index funds, mutual funds, and diversified portfolios without relying on speculative trading.
Managing and Protecting a Million-Dollar Portfolio
Once accumulated, 1 million dollars requires active preservation strategies. Poor asset management, unmitigated tax liabilities, and emotional decision-making during market downturns can deplete capital rapidly.
Asset Allocation and Diversification
A balanced portfolio prevents catastrophic losses during economic downturns. Diversification spreads risk across different asset classes, geographic regions, and industries.
| Asset Class | Typical Role in Portfolio | Risk Level | Liquidity |
|---|---|---|---|
| Equities (Stocks) | Long-term growth and capital appreciation | Moderate to High | High |
| Fixed Income (Bonds) | Income generation and capital preservation | Low to Moderate | Moderate |
| Real Estate | Cash flow, diversification, and inflation hedge | Moderate | Low |
| Cash and Equivalents | Emergency funds and short-term liquidity | Lowest | Immediate |
Tax Efficiency
Tax planning is a core component of managing substantial wealth. Capital gains taxes, income taxes, and estate taxes can significantly reduce net returns if ignored. Utilizing tax-advantaged accounts (such as IRAs, 401(k)s, or equivalent structures depending on jurisdiction) and working with certified tax professionals helps maximize retention of earnings.
The 4% Rule and Sustainable Withdrawal Rates
For individuals looking at 1 million dollars through the lens of retirement or financial independence, the primary question centers on sustainability: How long will the money last?
The widely referenced "4% rule" emerged from historical market studies (such as the Trinity Study) as a guideline for retirement withdrawals. It suggests that a retiree can withdraw 4% of their initial portfolio value in the first year of retirement, and adjust that dollar amount for inflation in subsequent years, with a high probability that the funds will last for 30 years.
Limitations of Withdrawal Rules
While useful as a baseline, the 4% rule relies on historical data that may not mirror future economic conditions. Factors that influence sustainable withdrawal rates include:
- Sequence of Returns Risk: Experiencing severe market downturns in the first few years of retirement can permanently damage portfolio longevity.
- Inflation Volatility: Unanticipated spikes in living costs force higher withdrawals, depleting principal faster.
- Flexible Spending: Modern financial planning often advocates for dynamic withdrawal strategies, where spending scales down during bad market years and scales up when portfolios perform well.
Common Misconceptions About Having a Million Dollars
Popular culture often distorts the reality of personal finance, leading to widespread myths about seven-figure net worths.
Myth: It Guarantees Lifelong Luxury
A million-dollar net worth does not automatically equate to perpetual luxury or freedom from work. If tied up in primary residential real estate and illiquid retirement accounts, a person may have a high net worth on paper while experiencing tight cash flow. Furthermore, in high-cost-of-living metropolitan areas, a million dollars buys a modest home and a standard retirement fund rather than an extravagant lifestyle.
Myth: It Is an Endpoint
Many view 1 million dollars as a finish line. In reality, financial health is dynamic. Inflation, healthcare costs, market corrections, and life events mean that wealth requires ongoing management, maintenance, and adaptation regardless of the specific dollar figure attached to a portfolio.
Frequently Asked Questions
Can you retire comfortably on 1 million dollars?
Retiring comfortably on 1 million dollars depends heavily on lifestyle expectations, geographic location, and annual expenses. For individuals with modest spending habits and low debt, a million-dollar portfolio—supplemented by pensions or social security systems—can provide a stable retirement. However, in high-cost regions or for those with high healthcare needs, additional capital may be necessary.
Is 1 million dollars considered rich today?
While 1 million dollars places an individual well above average net worth statistics globally, it no longer buys the elite status it once did. It represents upper-middle-class security or the foundation of a comfortable retirement rather than extreme wealth or perpetual luxury.
How does inflation affect a million-dollar savings account?
Holding 1 million dollars purely in cash or low-interest accounts leaves the principal vulnerable to inflation. Over time, rising consumer prices reduce the purchasing power of that cash, meaning it will buy fewer goods and services each year unless invested in assets that outpace inflation.
What is the fastest way to make 1 million dollars?
There is no guaranteed or safe shortcut to accumulating 1 million dollars. While high-risk ventures, successful entrepreneurship, or speculative trading can generate wealth quickly, they carry an equally high probability of total capital loss. Sustainable wealth accumulation typically relies on consistent saving, disciplined investing, and income growth over time.
How much income does 1 million dollars generate annually?
Using conservative investment withdrawal guidelines like the 4% rule, 1 million dollars can theoretically generate around $40,000 per year in initial pre-tax income. Actual income varies depending on dividend yields, interest rates, portfolio composition, and market performance.
Next Steps for Financial Planning
Evaluating personal proximity to a million-dollar net worth requires a structured review of current assets, liabilities, and long-term goals. Start by calculating a precise net worth statement, listing all liquid savings, investments, real estate equity, and outstanding debts. Consult a fee-only fiduciary financial planner to review tax strategies, risk tolerance, and retirement projections tailored to your specific jurisdiction and life stage.