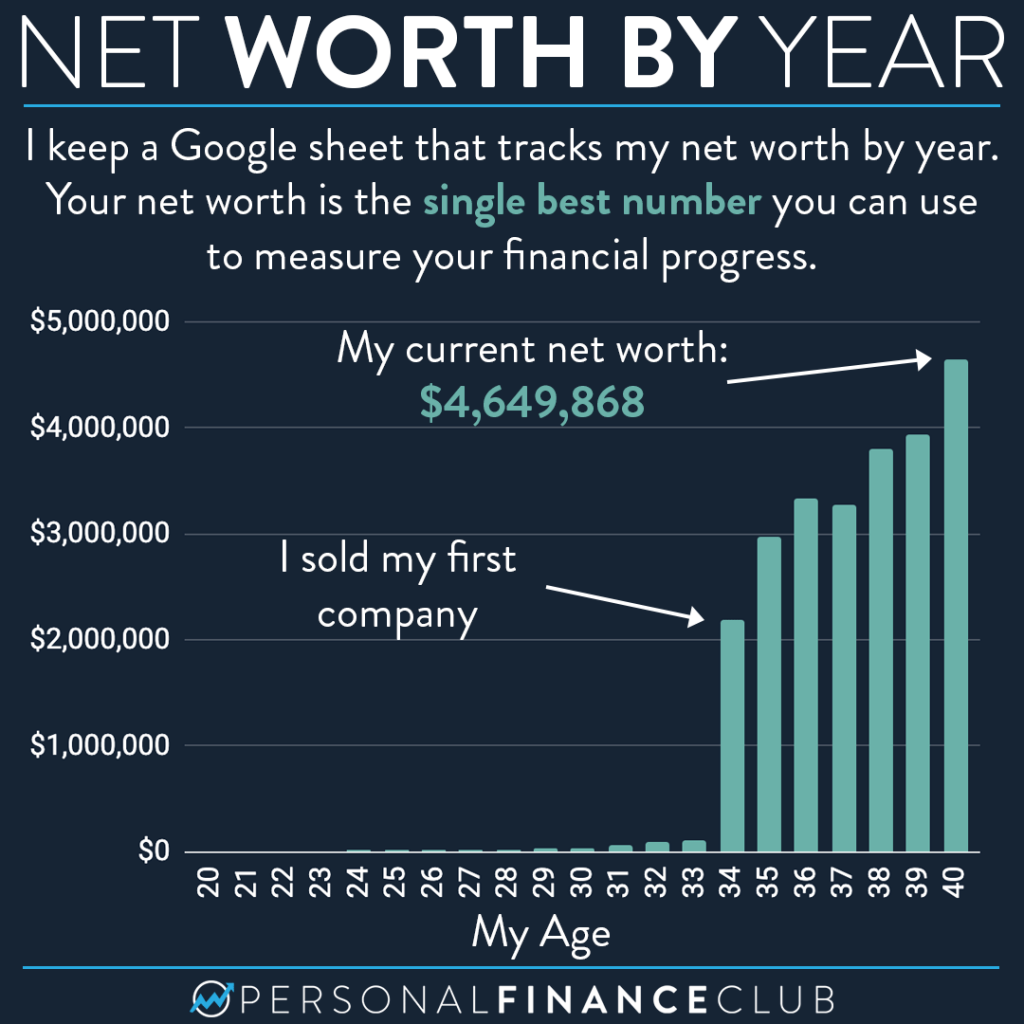
As of 2026, the median net worth for a 25-year-old is approximately $12,000, while the average net worth sits significantly higher at nearly $52,000. This disparity exists because high earners and those with inherited wealth skew the average, making the median a more realistic benchmark for the typical young professional.
Calculating net worth at age 25 provides a critical baseline for your financial journey. At this stage of life, many individuals are transitioning from entry-level roles into mid-level positions or completing advanced degrees. While the "average" may seem daunting, net worth is a highly individualized metric influenced by student debt, geographic location, and career choice. Understanding where you stand relative to 2026 benchmarks allows for better strategic planning regarding debt repayment, retirement contributions, and asset accumulation.
Defining Net Worth: Average vs. Median in 2026
To understand the benchmarks for a 25-year-old, one must first distinguish between the average (mean) and the median. In the context of American wealth, these two figures tell very different stories.
The average net worth is calculated by summing the total wealth of all individuals in the age bracket and dividing by the number of people. Because of the "top 1%"—individuals who may have founded successful startups, inherited significant estates, or entered high-paying fields like specialized surgery or investment banking—the average is often inflated. In 2026, the average net worth for those aged 20-25 is approximately $52,000, but this figure does not represent the "typical" experience.
The median net worth is the middle point of the data set. If you lined up every 25-year-old in the country from poorest to wealthiest, the person in the exact middle represents the median. For 2026, that figure is roughly $12,000. This is a more attainable and grounded benchmark for most people. It reflects the reality that many 25-year-olds are still grappling with the early stages of compounding interest while simultaneously servicing liabilities like auto loans or remaining student debt.
The Financial Landscape for 25-Year-Olds in 2026
The economic environment of 2026 presents unique challenges and opportunities compared to previous decades. Several factors have shifted the "normal" net worth for young adults:
1. Wage Growth and Inflation
Over the past several years, wage growth has remained competitive in technical and service sectors, but the cost of living—particularly housing—has remained a significant hurdle. A 25-year-old in 2026 likely entered the full-time workforce between 2022 and 2024, a period marked by fluctuating interest rates. Consequently, while salaries are higher in nominal terms than they were in 2020, the purchasing power and the ability to save for a down payment have required more disciplined budgeting.
2. The Persistence of Student Debt
Student loans remain the primary "anchor" on net worth for this demographic. While various federal forgiveness programs and income-driven repayment plans have evolved, the sheer volume of debt for those with graduate degrees often leads to a negative net worth at 25. It is important to remember that a negative net worth at this age is not a permanent failure; rather, it is often an investment in "human capital" that will yield higher earnings in the future.
3. Digital Assets and Early Investing
By 2026, the barrier to entry for investing has collapsed. Fractional shares, automated "round-up" savings apps, and the normalization of low-cost Index ETFs mean that more 25-year-olds are participating in the market than previous generations. This early exposure to the S&P 500 or total market funds has helped buoy the median net worth, even for those with modest incomes.
2026 Net Worth Benchmarks by Percentile
To give you a clearer picture of where you stand, we can look at the distribution of wealth across the 25-year-old cohort. Note that "Net Worth" is defined as Total Assets minus Total Liabilities.
| Percentile | Estimated Net Worth (2026) | Description |
|---|---|---|
| 10th Percentile | -$35,000 | Individuals with significant student or consumer debt. |
| 25th Percentile | $1,500 | Just beginning to build an emergency fund; debt nearly equals assets. |
| 50th Percentile (Median) | $12,000 | The "average" young adult with a modest savings/401k balance. |
| 75th Percentile | $45,000 | Consistent savers, often in dual-income households or low-cost areas. |
| 90th Percentile | $115,000 | High earners or those with significant early-career investment growth. |
| 99th Percentile | $450,000+ | Top earners, entrepreneurs, or beneficiaries of family wealth. |
How to Calculate Your Current Net Worth
Before comparing yourself to the benchmarks, you must perform an honest audit of your finances. Net worth is a snapshot in time; it will change monthly.
Step 1: List Your Assets
Assets are everything you own that has cash value. For a 25-year-old, this typically includes:
- Cash and Equivalents: Money in checking, savings, and High-Yield Savings Accounts (HYSA).
- Retirement Accounts: The current balance of your 401(k), 403(b), or Roth/Traditional IRA.
- Brokerage Accounts: Taxable investments in stocks, bonds, or ETFs.
- Real Estate: If you own a home, use the current market value (not what you paid for it).
- Personal Property: Generally, only include high-value items that retain resale value, such as a car (using Kelley Blue Book values). Avoid including clothes or electronics unless they are high-end collectibles.
Step 2: List Your Liabilities
Liabilities are everything you owe to another entity:
- Student Loans: The total remaining principal on federal and private loans.
- Credit Card Debt: Any balances carried over from month to month.
- Auto Loans: The remaining payoff amount on your vehicle.
- Mortgages: The total principal remaining on your home loan.
- Personal Loans: Any money owed to family or private lenders.
Step 3: The Formula
[Total Assets] - [Total Liabilities] = Net Worth.
If your result is negative, do not panic. This is common for doctors, lawyers, and other professionals who spend their early 20s in school. The goal at 25 is not necessarily a high number, but a positive trend line.
Factors That Skew the Benchmarks
A 25-year-old living in San Francisco with a $150,000 salary might have a lower net worth than a 25-year-old in Indianapolis earning $65,000, simply due to the cost of living and taxes. When evaluating your progress, consider these context-specific variables:
- Geographic Arbitrage: Those working remotely for high-paying companies while living in low-cost-of-living (LCOL) areas tend to see their net worth explode in their mid-20s.
- Employer Matching: A 25-year-old whose company offers a 6% 401(k) match is effectively receiving a "guaranteed" 100% return on that portion of their wealth, which accelerates net worth growth faster than someone without a match.
- The "Hidden" Safety Net: Some individuals have their health insurance or cell phone bills paid by parents, allowing them to redirect 100% of their income toward assets. This creates a disparity in "earned" net worth versus "subsidized" net worth.
Strategies to Increase Your Net Worth Before Age 30
If you find yourself below the 2026 median of $12,000, there are several levers you can pull to accelerate your growth. The five years between age 25 and 30 are some of the most critical for wealth building due to the power of time.
1. Maximize the "Big Three" Expenses
Housing, transportation, and food typically consume 70% of a young adult's income. By "house hacking" (living with roommates) or driving a reliable used car instead of financing a new one, you can free up hundreds of dollars a month for the market.
2. Prioritize High-Interest Debt
In the current interest rate environment of 2026, credit card debt (often 20%+) is a "wealth killer." No investment will reliably beat a 20% guaranteed return. Use the Debt Avalanche method: pay the minimum on all debts, and put every extra dollar toward the loan with the highest interest rate.
3. Automate Retirement Contributions
The Internal Revenue Service (IRS) sets annual contribution limits for 401(k)s and IRAs. Even if you cannot "max out" these accounts, automating a percentage of your paycheck ensures that you pay yourself first. By age 25, aiming for 15% of your gross income into retirement accounts is the standard recommendation for long-term security.
4. Build a "Moat" (Emergency Fund)
A high net worth is fragile if you don't have liquidity. Aim for 3–6 months of essential expenses in a High-Yield Savings Account. This prevents you from having to sell investments or take on high-interest debt when an unexpected expense occurs.
The Role of Compound Interest at 25
The most valuable asset a 25-year-old possesses is time. According to the "Rule of 72," an investment at a 7% annual return will double roughly every 10 years.
- A dollar invested at 25 will double 4 times by the time you reach age 65 (becoming $16).
- A dollar invested at 35 will only double 3 times (becoming $8).
This is why your net worth at 25, even if it is only $5,000 or $10,000, is far more significant than it appears on paper. It is the "seed" for your future financial independence.
Frequently Asked Questions
Is it normal to have a negative net worth at 25?
Yes. It is very common, especially for those who have pursued higher education. If you have $50,000 in student loans and $10,000 in savings, your net worth is -$40,000. However, your "earning potential" (human capital) is high. As long as you have a plan to pay down high-interest debt and are contributing to a retirement account, a negative net worth in your mid-20s is often a temporary state.
How much should I have in my 401(k) by 25?
A common rule of thumb is to have roughly 0.5x your annual salary saved across all retirement accounts by age 25. If you earn $60,000, a benchmark goal would be $30,000. However, because many people don't start their careers until 22 or 23, having $10,000 to $15,000 is still considered "on track" for most.
Does my car count toward my net worth?
Technically, yes. A car is an asset. However, because cars are depreciating assets (they lose value over time), you should be conservative in your estimation. Use the "Private Party" value from a reputable source like Edmunds and remember to subtract any remaining auto loan balance to find the "equity" in the vehicle.
What is a "good" net worth for a 25-year-old in 2026?
A "good" net worth is any number that is higher than it was six months ago. Practically speaking, if your net worth is above the median of $12,000, you are doing better than 50% of your peers. If you have a positive net worth of any amount and zero high-interest credit card debt, you are in a very strong position relative to the general population.
Should I prioritize saving for a house or investing in stocks at 25?
This depends on your goals and the local real estate market. In 2026, if mortgage rates are high, investing in a diversified stock portfolio via a Roth IRA often yields better long-term results. However, if you plan to stay in one city for 7-10 years, saving for a down payment can be a powerful way to "lock in" housing costs and build equity.
Final Recommendation: Focus on the Trend, Not the Total
Your net worth at 25 is simply a starting point. The benchmark of $12,000 (median) or $52,000 (average) provides context, but it shouldn't be a source of stress. The most important action you can take in 2026 is to increase your savings rate.
Whether you are starting at -$50,000 or +$50,000, focus on increasing the gap between what you earn and what you spend. Invest that difference into low-cost index funds and high-yield savings. By the time you reach the next major benchmark at age 30, the habits you build today will have a far greater impact on your wealth than your current balance sheet.