When an individual—referred to here as X—owns a disability income policy, they hold a critical financial safety net designed to protect their most valuable asset: their earning power. In 2026, navigating the complexities of disability insurance requires a thorough understanding of policy mechanics, taxation rules, elimination periods, and claim optimization strategies. Whether X purchased an individual policy through a private broker or is utilizing an employer-sponsored group plan, understanding the precise parameters of ownership ensures that financial protection translates into reliable income replacement when health events interrupt employment.
Structural Anatomy of a Disability Income Policy Owned by X
A disability income (DI) policy functions by replacing a predetermined percentage of pre-disability earnings—typically between 60% and 80%—should an illness or injury prevent X from working. The ownership structure of the policy dictates not only who pays the premiums, but also how benefits are taxed at the time of payout.
When X owns an individual policy outright and pays the premiums with post-tax dollars, any benefits received are generally entirely income tax-free. This distinction is vital for financial planning, as a tax-free benefit of $5,000 per month has significantly greater purchasing power than a taxable benefit of the same nominal value. Conversely, if X participates in an employer-sponsored group long-term disability (LTD) plan where the employer pays the premiums or X pays pre-tax dollars through a cafeteria plan, the resulting benefits are treated as taxable ordinary income.
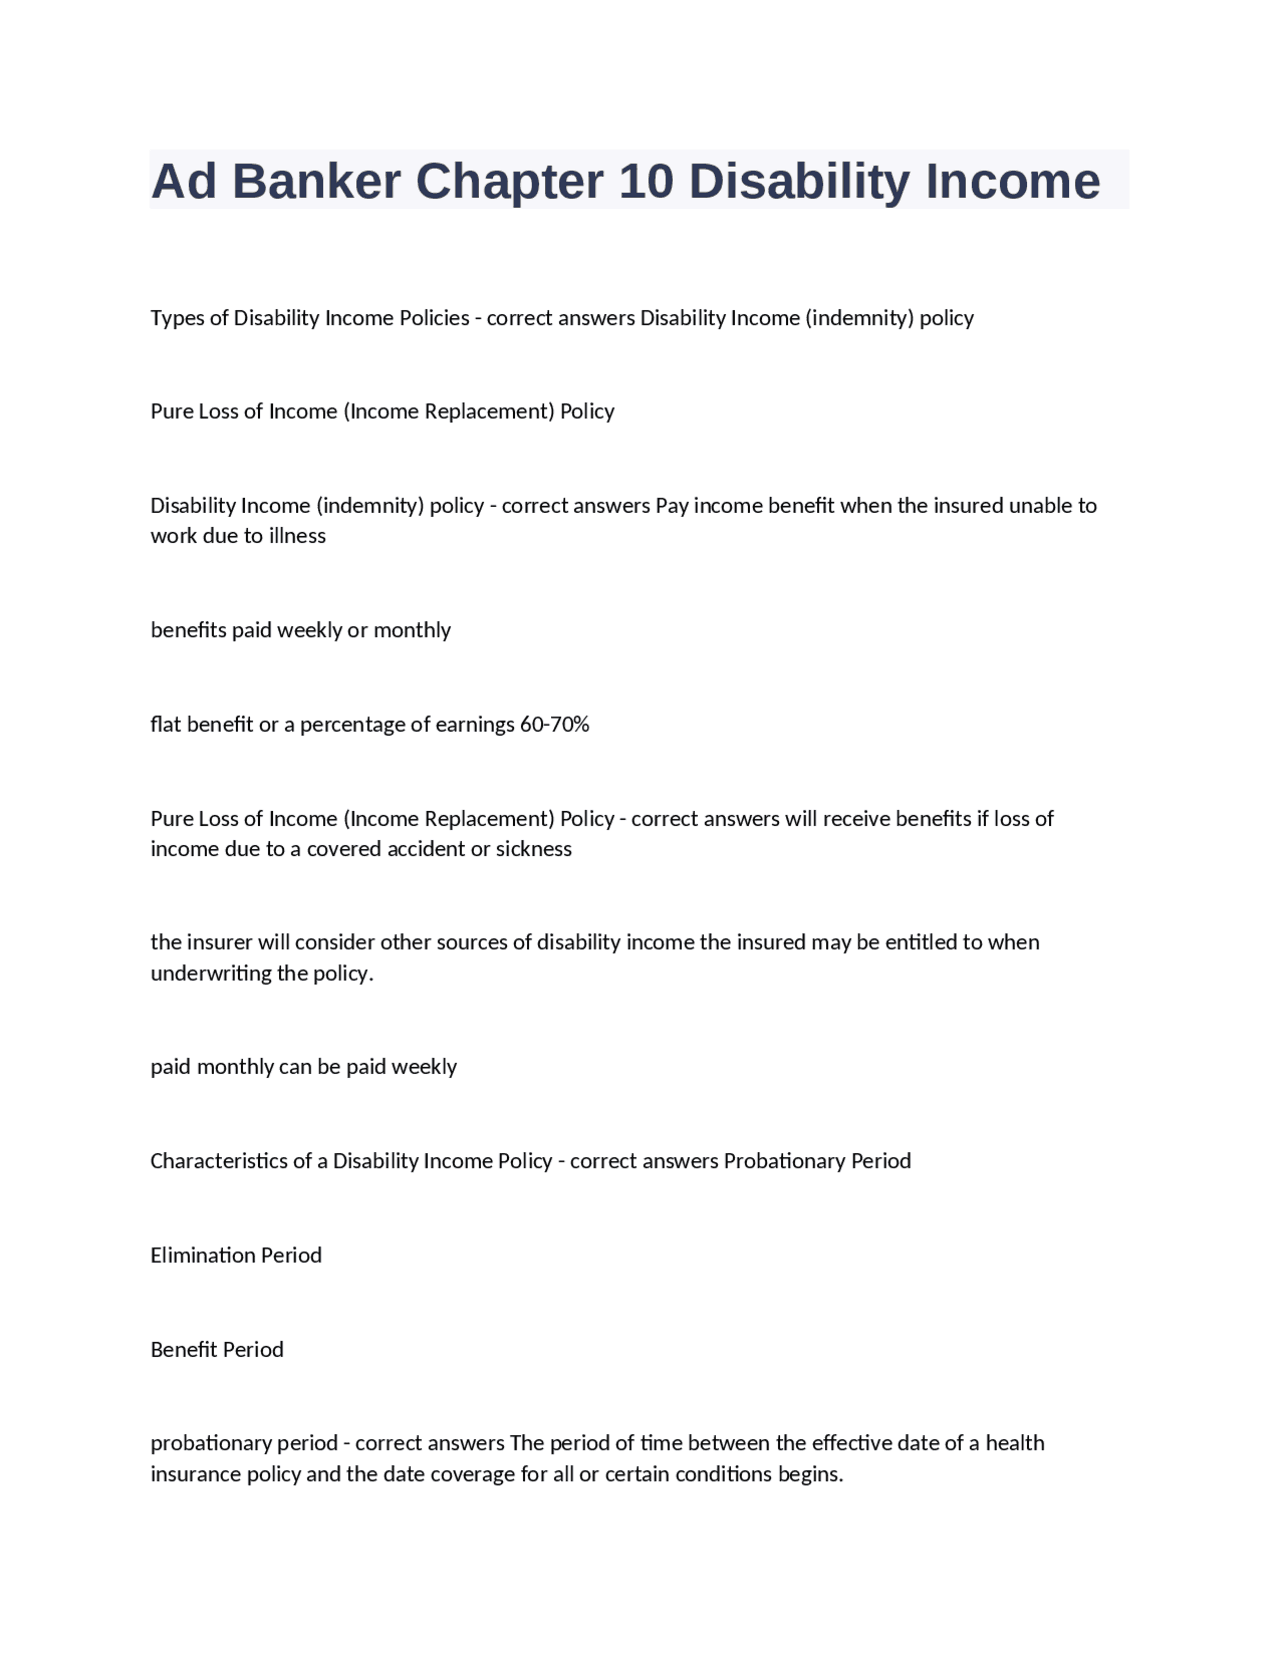
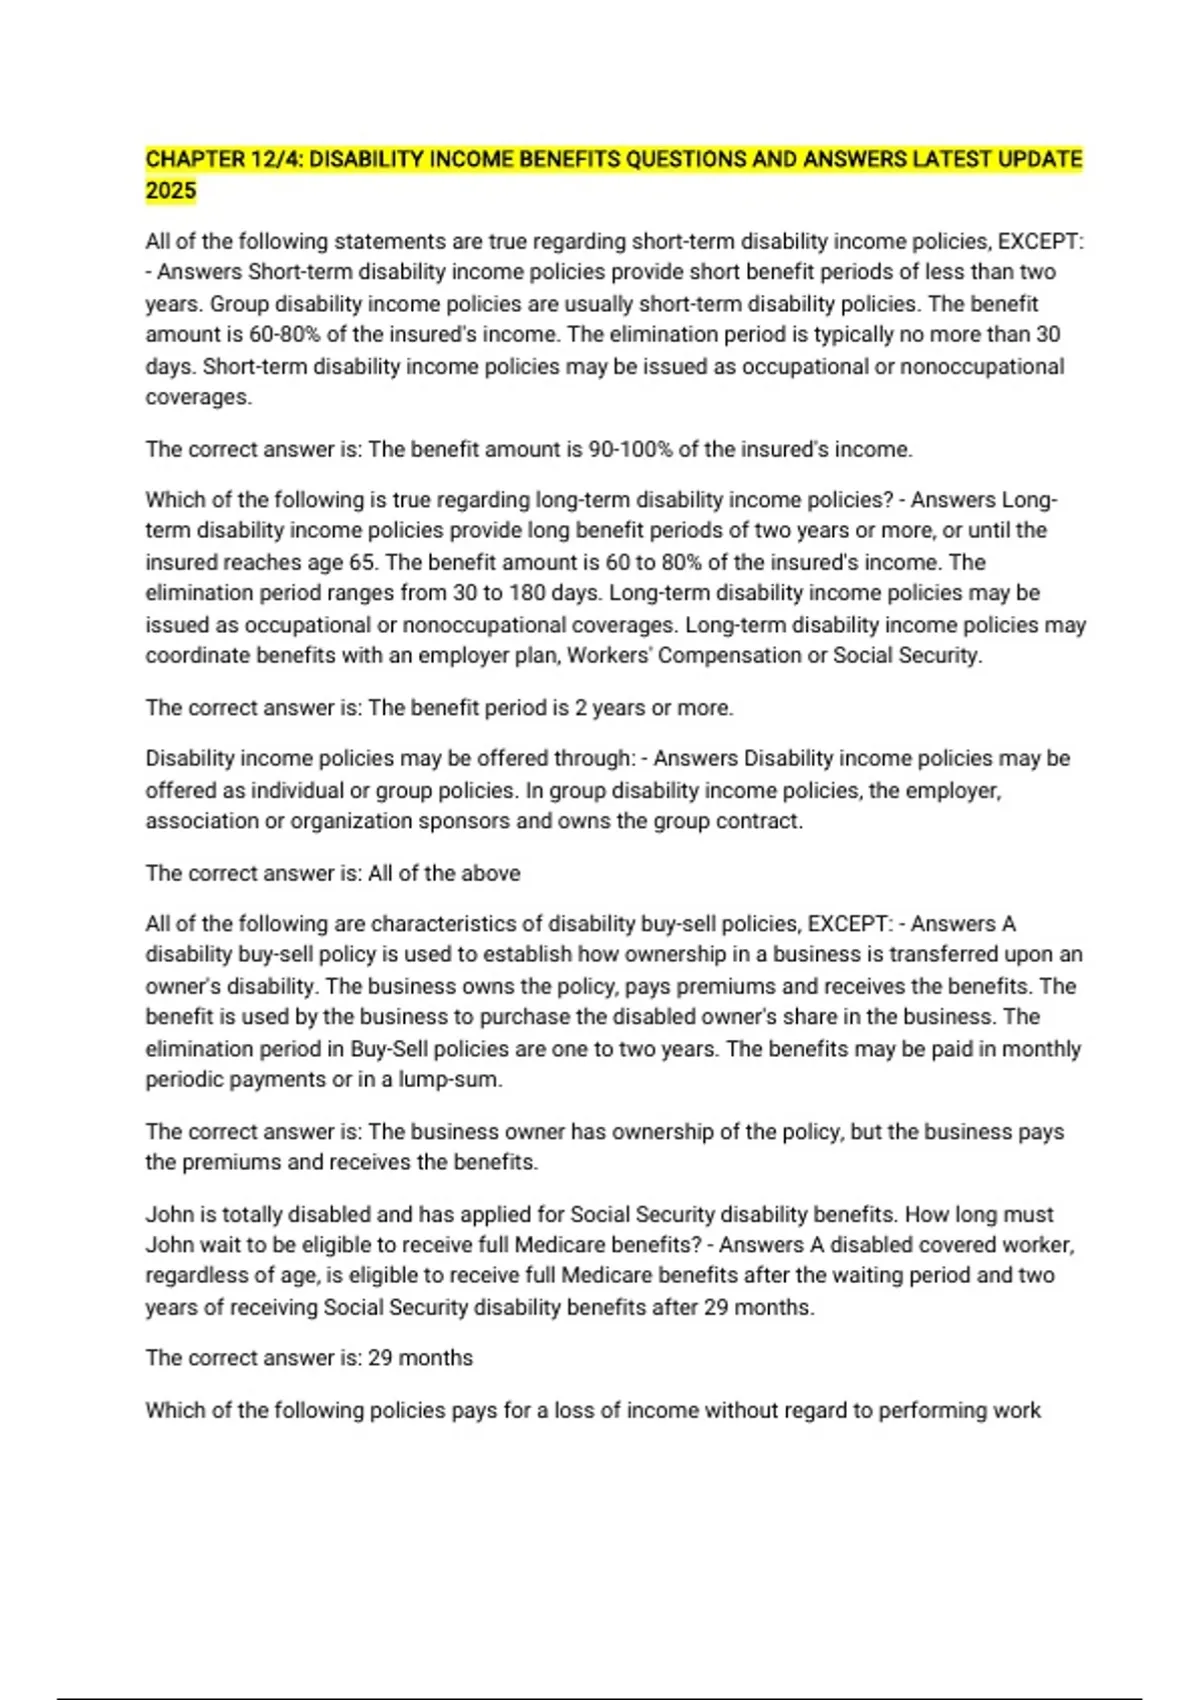
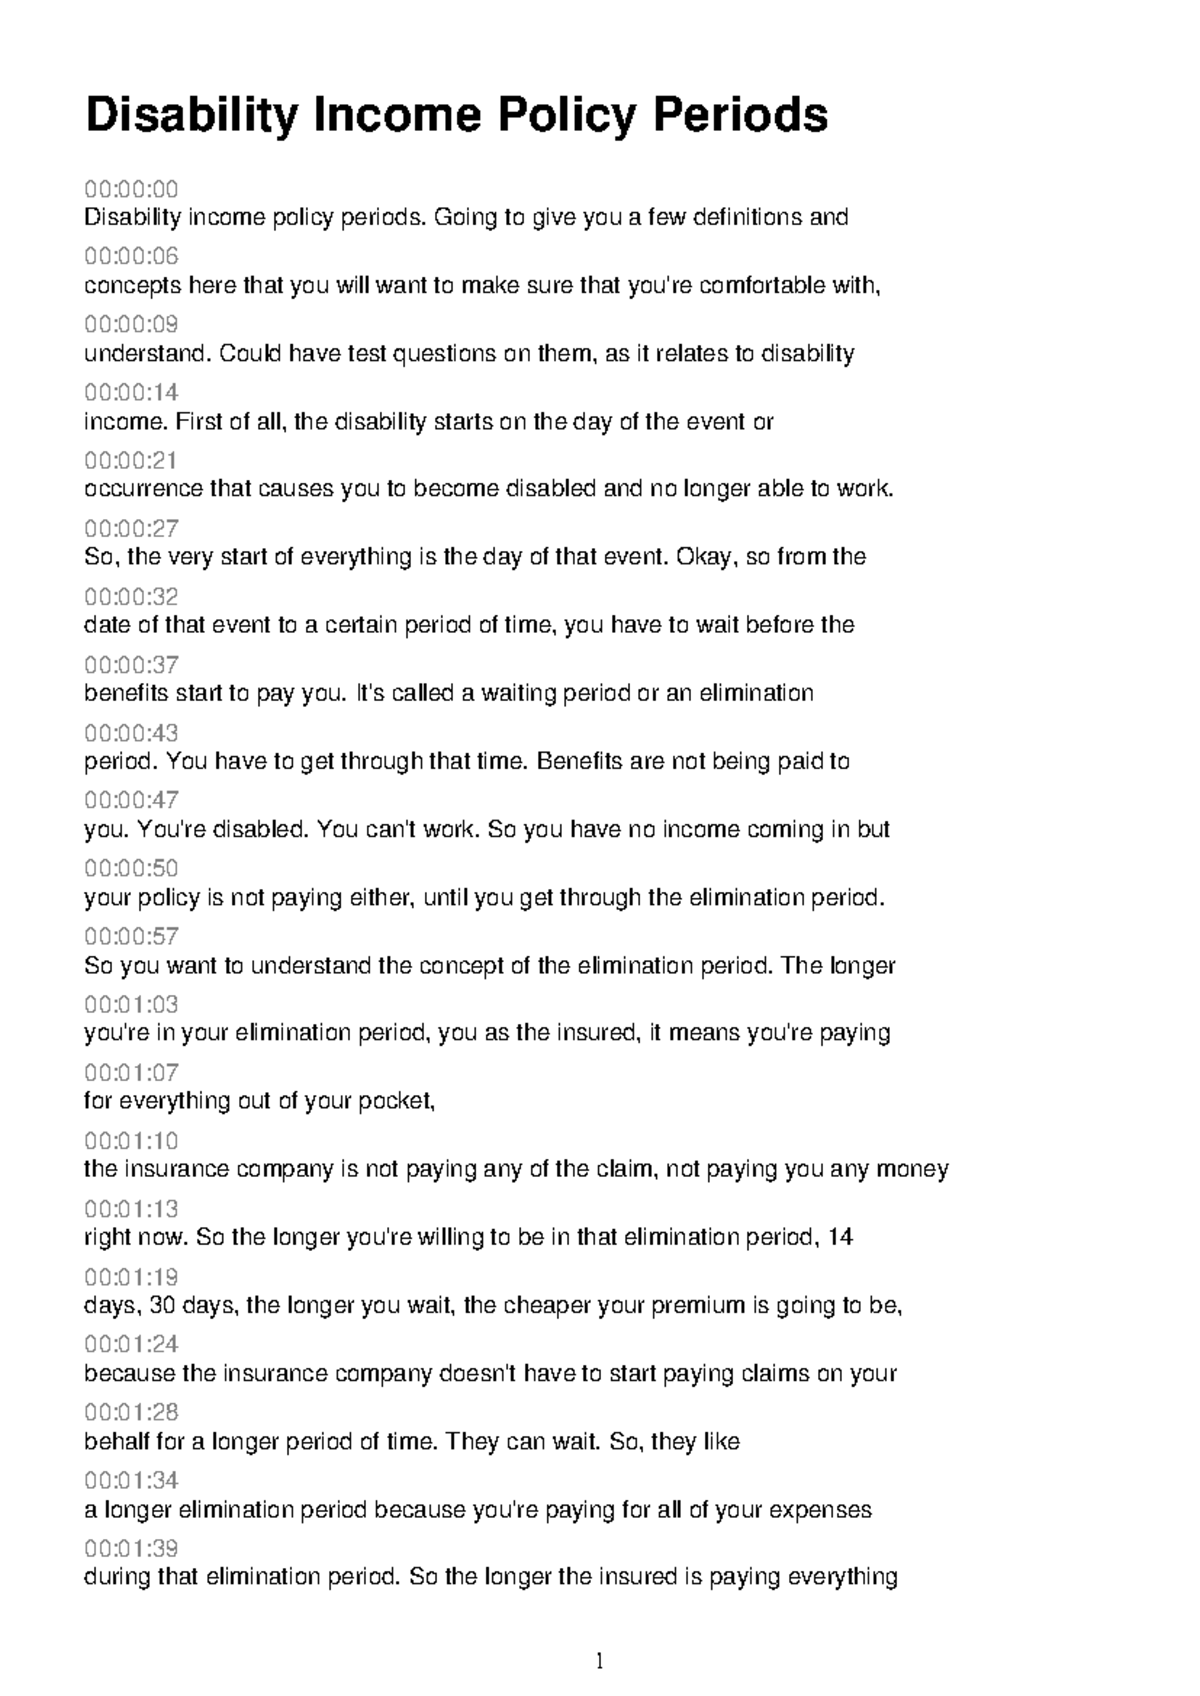
- Elimination Period: The waiting period between the onset of the disabling event and the commencement of benefit payouts. Common durations range from 30, 90, to 180 days, with longer periods substantially reducing annual premium costs.
- Benefit Period: The maximum duration for which benefits will be paid, which can range from two years, five years, to age 65, age 67, or lifetime coverage.
- Residual vs. Total Disability: Modern policies differentiate between total inability to perform any occupation and residual disability, which compensates X for partial loss of earnings if they can still work part-time or in a reduced capacity.
Evaluating Policy Definitions of Disability and Rider Integration
The core operational mechanism of any DI policy owned by X rests on how the contract defines "disability." Insurance carriers utilize varying standards that directly influence claim approval success and ongoing benefit eligibility.
The gold standard for professionals and specialized workers is the "Own Occupation" definition. Under this provision, if X is unable to perform the specific duties of their specialized occupation due to injury or illness, they collect full benefits even if they choose to work in a different, lower-paying profession. Conversely, an "Any Occupation" definition is much stricter, stipulating that benefits will only be paid if X is physically or mentally incapable of engaging in any gainful occupation for which they are reasonably fitted by education, training, or experience.
Crucial Policy Riders to Verify: X must regularly audit their policy schedule to ensure proper riders are active. A Cost of Living Adjustment (COLA) rider protects benefit purchasing power against inflation during long-term claims. A Future Insurability Option (FIO) rider allows X to increase monthly benefit limits as their income grows without undergoing medical underwriting.
Comparative Analysis of Individual vs. Group Disability Policies
Understanding the structural differences between individual policies owned privately by X and group plans provided by an employer helps clarify coverage gaps and risk exposure.
| Feature | Individual Disability Policy (Owned by X) | Group Long-Term Disability Plan |
|---|---|---|
| Ownership and Portability | Fully portable; stays with X regardless of employment changes. | Tied to current employer; terminates upon job separation. |
| Tax Treatment of Benefits | Generally tax-free because premiums are paid with post-tax dollars. | Typically taxable because premiums are employer-paid or pre-tax. |
| Definition of Disability | Often true "Own-Occupation" for the life of the policy or extended periods. | Shifts from "Own-Occ" to "Any-Occ" typically after 24 months. |
| Underwriting Requirements | Requires full medical and financial underwriting at application. | Little to no medical underwriting, but subject to pre-existing condition clauses. |
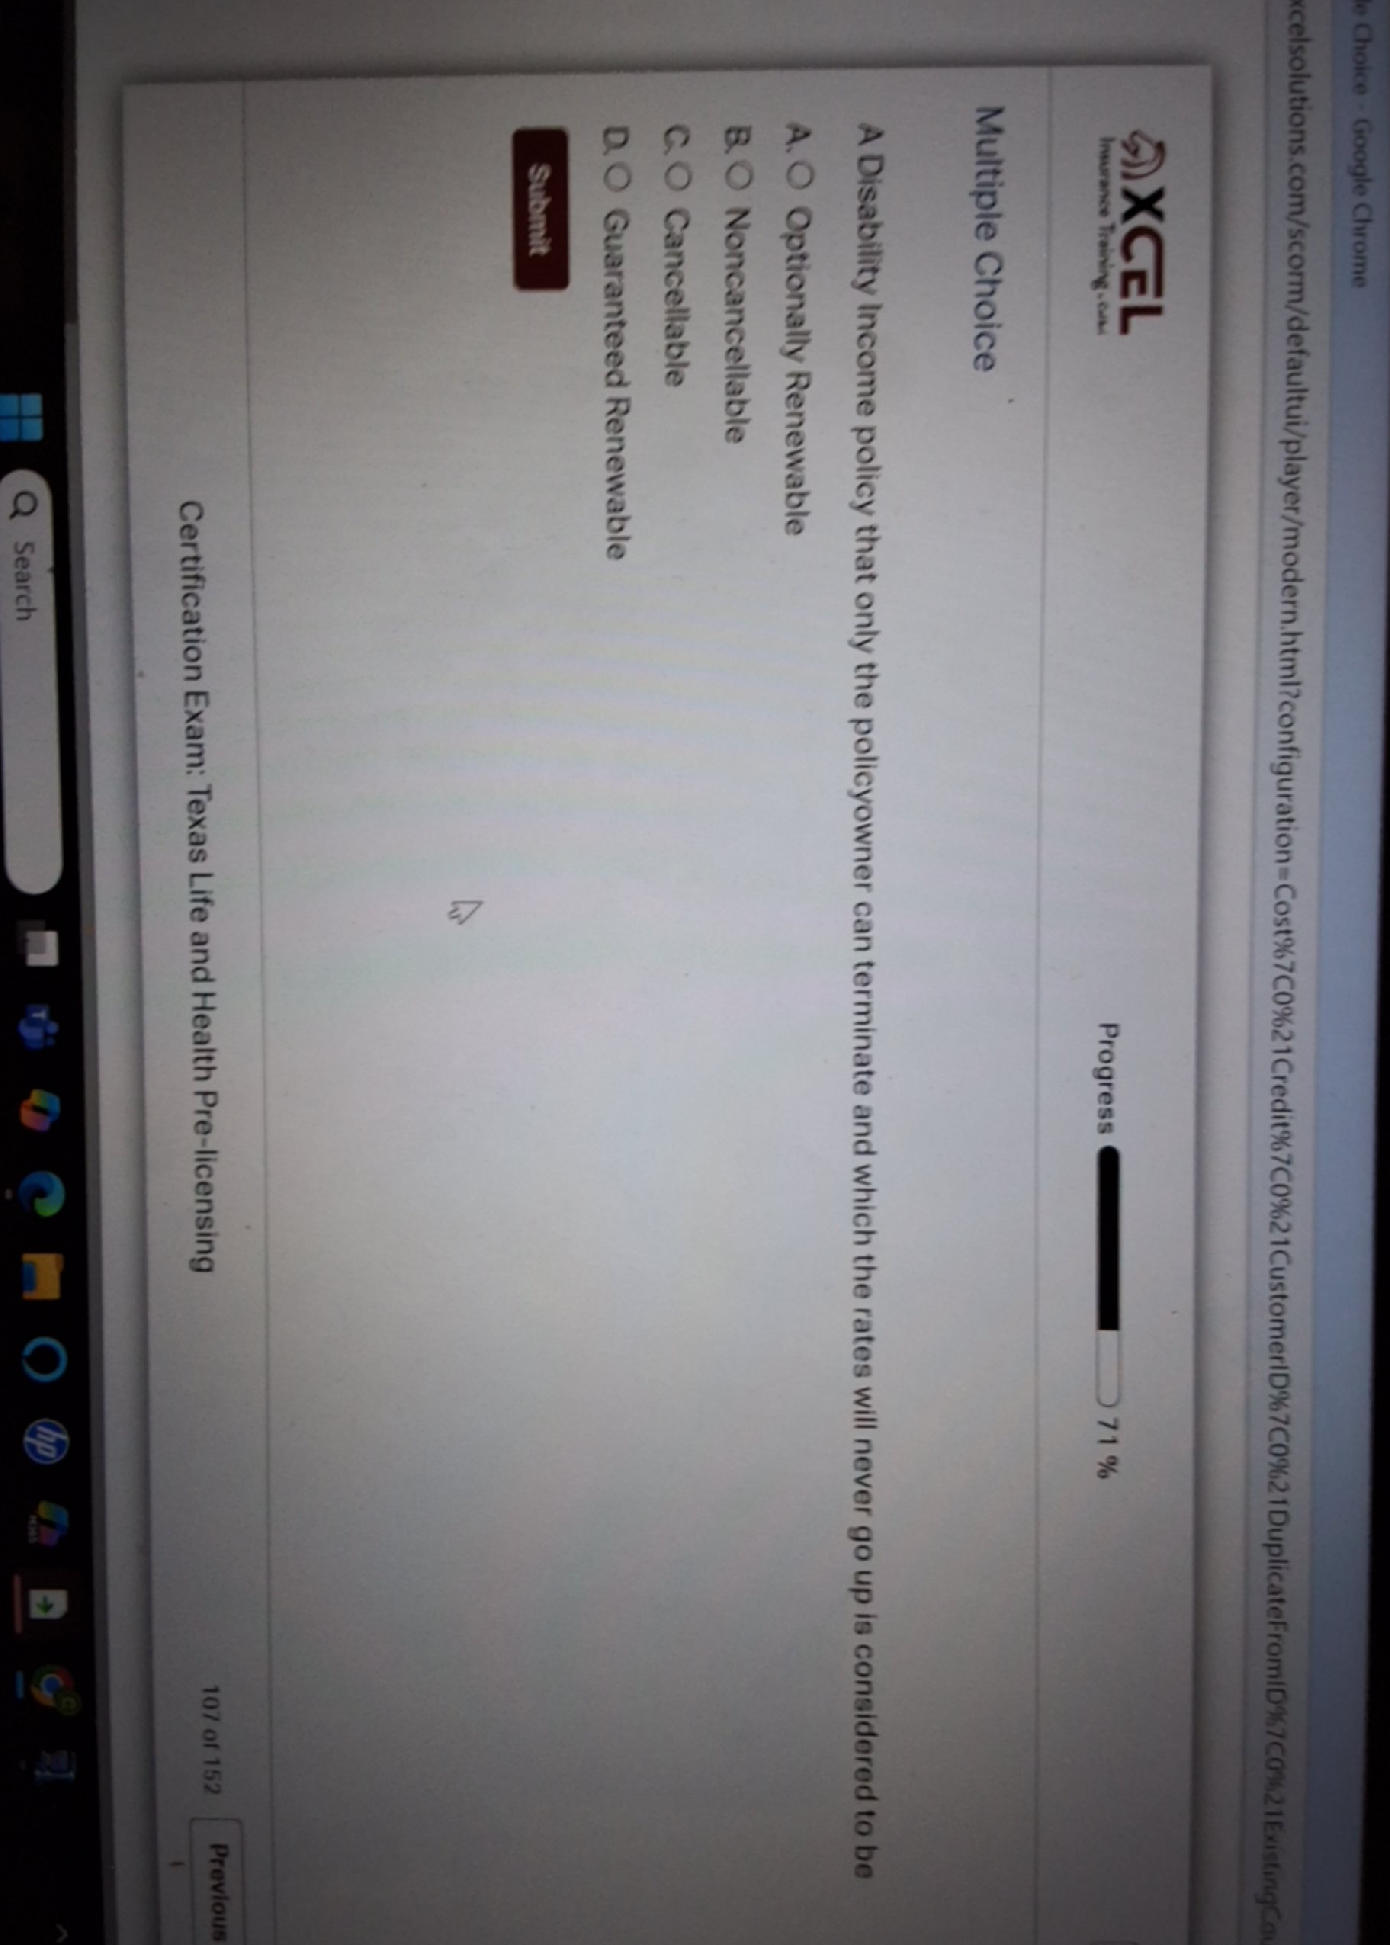
| Rate Stability | Non-cancellable and guaranteed renewable; premiums cannot be raised individually. | Rates can fluctuate annually, and the employer can cancel the plan. |
Strategic Action Plan: Managing and Claiming Under a Disability Policy
When X faces a medical event that triggers the potential need to file a claim, executing a systematic, methodical approach prevents administrative delays and minimizes the risk of claim denial.
- Review Contract Specifications: Immediately examine the policy schedule to confirm the exact elimination period, current benefit amount, and notification deadlines required by the carrier.
- Notify the Carrier Promptly: Submit written notice of claim within the timeframe specified in the contract—typically within 20 to 30 days of the disabling event—to avoid compliance complications.
- Gather Comprehensive Medical Documentation: Coordinate with attending physicians, surgeons, and specialists to compile objective clinical data, diagnostic test results, treatment logs, and explicit restrictions and limitations forms.
- Establish Proof of Earnings Loss: For residual or partial disability claims, provide detailed historical and current financial statements, tax records, or payroll reports demonstrating the direct correlation between the medical condition and income reduction.
- Maintain Active Communication: Keep a detailed log of all phone calls, correspondence, and submitted documents with the insurance claims adjuster, ensuring all follow-up requests are satisfied promptly.
Common Pitfalls and Troubleshooting Claim Disputes
Even when X owns a well-structured disability income policy, carriers frequently scrutinize claims, particularly those involving subjective conditions such as chronic fatigue, mental health disorders, or musculoskeletal pain.
- Objective vs. Subjective Evidence: Insurers often deny claims citing a lack of objective findings. X should work closely with medical providers to ensure clinical notes emphasize measurable functional capacities (e.g., lifting limits, sitting tolerances) rather than solely patient-reported pain scales.
- Concurrent Work and Residual Traps: Attempting to work part-time without an active residual disability rider or without notifying the carrier can jeopardize the entire claim. Always verify how partial earnings impact benefit calculations.
- Independent Medical Examinations (IMEs): The carrier may request X to undergo an evaluation by an independent physician of the insurer's choosing. Preparation, accurate representation of daily limitations, and adherence to appointment requirements are vital.
Frequently Asked Questions
What happens to the policy owned by X if X changes jobs or becomes self-employed?
If X owns an individual, non-cancellable, and guaranteed renewable disability policy, changing jobs or transitioning to self-employment has zero effect on coverage, as the policy is entirely portable. However, if the coverage is an employer-sponsored group plan, the insurance terminates immediately upon employment separation unless a portability option was explicitly purchased.
Are disability income policy benefits considered taxable income for X?
Taxability depends entirely on who paid the premiums. If X paid the premiums with personal, post-tax dollars for an individual policy, the benefits are 100% tax-free, whereas benefits from employer-funded or pre-tax group plans are fully taxable as ordinary income.
How does the elimination period affect the cost of the policy owned by X?
The elimination period functions like an insurance deductible in reverse time; selecting a longer waiting period significantly lowers the annual premium. For example, extending the elimination period from 30 days to 90 or 180 days can decrease premium costs by 15% to 30%.
Can an insurance company cancel a disability policy owned by X if X develops a chronic illness?
If X owns a policy classified as "non-cancellable and guaranteed renewable," the insurer cannot cancel the policy, alter its terms, or raise premium rates as long as X continues to pay the required premiums on time.
What is the difference between "Own-Occupation" and "Any-Occupation" clauses?
Own-Occupation covers X if they cannot perform the specific duties of their specialized job, even if they can work elsewhere, while Any-Occupation only pays benefits if X is completely unable to perform any job suited for their education, training, and experience.
Conclusion and Expert Guidance
Securing financial stability requires ongoing management and strategic foresight when X owns a disability income policy. By verifying policy definitions, understanding tax implications, and maintaining pristine documentation standards, X can safeguard their financial future against unforeseen health disruptions. To optimize existing coverage or structure a new policy tailored to specific professional earnings, consult with a fee-only financial planner or an independent insurance specialist licensed in your jurisdiction.