Navigating the aftermath of a "160 accident"—a term often used in transit and civil engineering to refer to incidents involving specific high-capacity road segments, heavy transport vehicle limitations, or technical classification markers—requires a methodical approach. Whether you are involved in a collision on a major artery or are managing a site incident, addressing the immediate safety, legal, and reporting requirements is critical to mitigating long-term physical, financial, and regulatory consequences.
Understanding the 160 Incident Context
In professional transport and safety management, an incident labeled under the "160" designation typically pertains to specific high-traffic corridors, weight-restricted zones, or segments where speed and load dynamics create unique risk profiles. When such an accident occurs, the urgency of the situation often obscures the necessary steps for documentation and recovery.
By analyzing the intersection of mechanical failure, human error, and environmental factors, we can categorize the core causes that lead to these events. Understanding these precursors is the first step toward effective mitigation and legal protection.
Primary Causes of Significant Road and Site Accidents
Accidents categorized within the "160" framework rarely stem from a single point of failure. Instead, they are usually the result of a chain reaction of factors.
- Mechanical and Technical Failure: In instances involving heavy machinery or commercial vehicles, brake failure, tire blowouts, or steering system malfunctions are common. These are often linked to deferred maintenance or parts that have exceeded their specified service life.
- Environmental and Infrastructure Stress: High-traffic segments often suffer from surface degradation. Potholes, poor drainage leading to hydroplaning, and inadequate signage in work zones frequently contribute to multi-vehicle collisions.
- Human Factor and Cognitive Load: Driver fatigue and distraction remain the leading causes of accidents. On long-haul routes or repetitive delivery circuits, the "vigilance decrement" phenomenon—where attention wanes after prolonged focus—significantly increases the risk of misjudging distance and speed.
- Regulatory Non-Compliance: Exceeding load-bearing capacity or failing to adhere to lane-specific regulations for heavy vehicles often triggers incidents. When a vehicle exceeds its structural or legal limit for a specific segment, the risk of loss of control during emergency maneuvers rises exponentially.
The Consequences: Beyond the Initial Impact
The aftermath of an accident extends far beyond the immediate damage to property or vehicles. Understanding the layers of impact helps stakeholders prioritize their actions during the critical first hour.
Immediate Physical and Safety Consequences
The primary consequence is always the risk to human life. Even in low-speed impacts, secondary accidents involving oncoming traffic are common. Secondary incidents often cause more severe injuries than the primary impact because the initial site remains unshielded and chaotic.
Economic and Operational Consequences
For businesses and commercial operators, the consequences include:
- Asset Loss: The cost of vehicle repair or total loss, combined with the loss of cargo or equipment.
- Insurance Premium Volatility: Even a single incident can lead to a significant spike in premiums, as risk profiles are recalculated based on historical data.
- Operational Downtime: The loss of a vehicle or the closure of a site segment results in contractual penalties and missed delivery windows.
Legal and Liability Implications
Liability is rarely clear-cut. Documentation collected at the scene becomes the primary evidence used by insurance adjusters and legal representatives. Failing to secure the scene or report the incident accurately can result in shifted liability, where the party with the most evidence—or the best documentation—tends to prevail in settlement negotiations.
Immediate Steps to Take After an Incident
When an accident occurs, your actions during the first 60 minutes determine the quality of your legal and insurance standing. Follow this sequence to protect your interests and ensure safety.
1. Secure the Environment
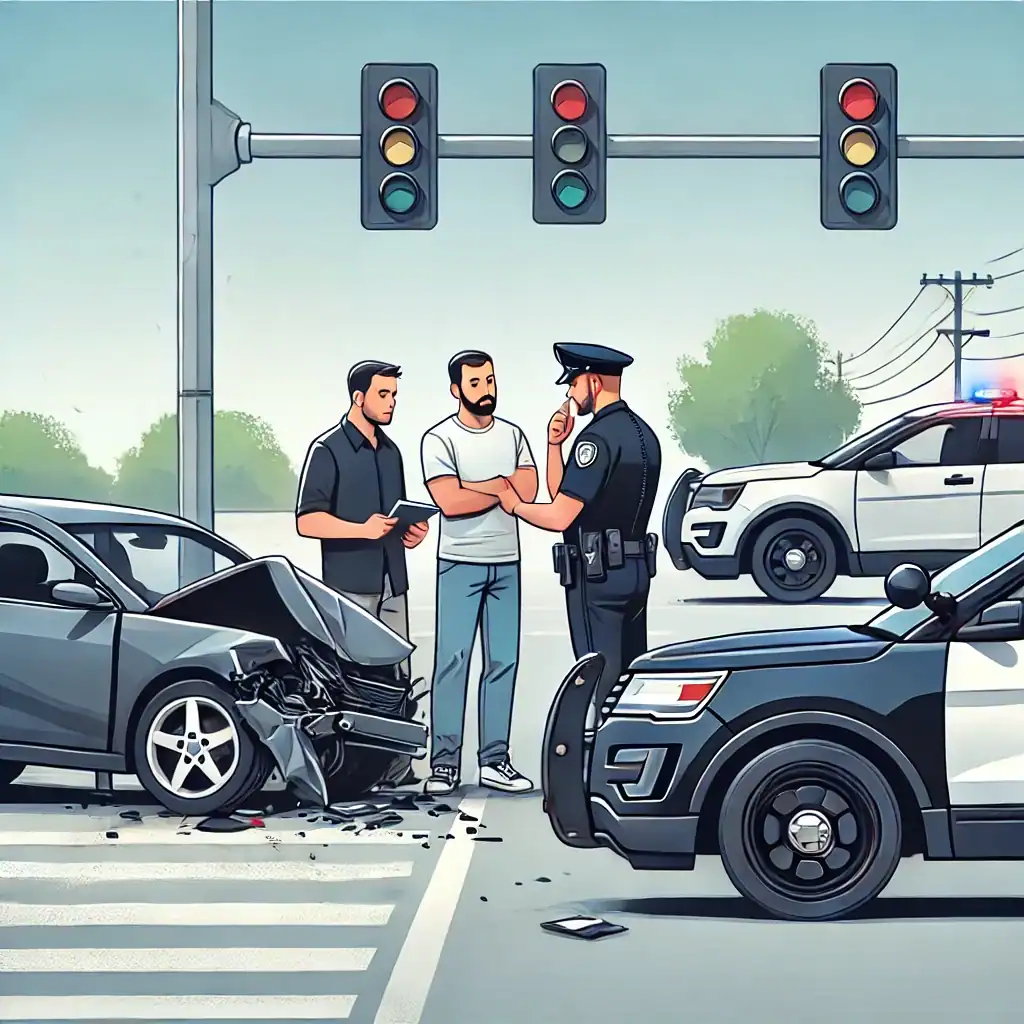
Before addressing documentation, ensure the safety of all individuals involved. Activate hazard lights and, if safe to do so, place reflective warning markers at a sufficient distance to alert oncoming traffic. If the vehicle is in a dangerous position, relocate to a protected area if possible, but do not move the vehicles involved in the collision unless instructed by law enforcement or local safety regulations.
2. Assess and Document
Detailed documentation is your strongest asset. If you are physically capable, collect the following:
- Visual Evidence: Capture photos of the vehicles from multiple angles, specifically noting the point of impact, tire marks, and the position of the vehicles relative to lane markers or signs.
- Environmental Context: Photograph weather conditions, the presence (or absence) of lighting, and the state of the road surface.
- Participant Information: Obtain names, contact details, insurance information, and identification from all drivers involved. Note the make, model, and license plate of every involved vehicle.
3. Formal Reporting
In most jurisdictions, any accident involving injury, property damage, or public infrastructure must be reported to the local police. Do not rely on verbal agreements with other parties to "settle out of pocket." A formal police report provides a neutral record of the event, which is essential for insurance claims and potential litigation.
Comparative Analysis of Accident Response Actions
| Action | Priority Level | Goal | Timing |
|---|---|---|---|
| Safety Assessment | Critical | Prevent further injury | Immediate |
| Emergency Services | High | Medical aid/Traffic control | 0-10 Minutes |
| Scene Documentation | High | Evidence preservation | 0-30 Minutes |
| Insurance Notification | Medium | Claim initiation | Within 24 Hours |
| Legal Consultation | Medium | Protect long-term rights | Within 48 Hours |
FAQ: Addressing Common Concerns
What if the other party suggests not calling the police? Always decline this request. A lack of an official police report makes it significantly harder to prove liability, leaving you vulnerable to fraudulent claims or "he-said, she-said" disputes that insurers are often unable to resolve in your favor.
How does a 160-type incident affect insurance premiums in 2026? As of 2026, insurance carriers are utilizing advanced telematics to analyze accident data. A formal report confirming your adherence to safety protocols during the post-accident phase can sometimes mitigate the severity of a premium increase compared to an undocumented, disputed claim.
When should I involve a legal professional? You should contact a lawyer if there are significant injuries, potential fatalities, or if the accident involves a commercial entity where complex liability and multi-party insurance agreements are in play.
Should I admit fault at the scene? Never admit fault. Statements made at the scene can be interpreted as legal admissions. Stick to the facts when speaking with police or other drivers: provide your contact and insurance details, and allow the investigators to determine the cause of the accident.
What if my vehicle is a total loss? If the repair costs exceed the vehicle's market value, the insurance company will classify it as a "total loss." In 2026, market volatility can affect vehicle valuation. Ensure you are aware of the "Actual Cash Value" (ACV) of your vehicle and do not simply accept the first offer from an insurer without reviewing current market comps.
Next Steps for Risk Mitigation
To avoid future accidents, implement a proactive maintenance and training schedule. For drivers and fleet managers, this means moving beyond annual inspections and adopting real-time monitoring of vehicle health. Regularly reviewing your insurance policy and understanding the specific "160" regulatory requirements for your route can provide a financial safety net.
If you have been involved in an incident, start by downloading a formal copy of your police report and consolidating all photographic evidence into a single digital folder. Present this to your insurance agent immediately to begin the claims process with the highest possible level of transparency and documentation.