Comenity Bank, a subsidiary of Bread Financial, occupies a unique position in the consumer banking and retail credit sector. When evaluating Comenity Bank against traditional financial institutions and digital-first credit issuers, consumers and financial analysts must look closely at interest rates, fee structures, customer service metrics, and product ecosystems. This comprehensive review examines Comenity Bank in 2026, comparing its retail credit cards, high-yield savings accounts, and digital banking capabilities against major industry competitors.
Understanding the Comenity Bank Model in 2026
Comenity Bank primarily operates as a private-label and co-branded credit card issuer for hundreds of major retail brands, ranging from apparel stores to specialty home goods merchants. In addition to retail credit, Comenity offers direct-to-consumer deposit products, including high-yield savings accounts and certificates of deposit (CDs), designed to compete with online banks and fintech platforms.
Unlike full-service traditional institutions like Chase or Bank of America, Comenity focuses heavily on niche rewards programs tied directly to specific merchant ecosystems. However, as digital banking evolves through 2026, consumers increasingly compare Comenity's broader financial products against specialized neobanks and legacy banking giants to determine where to hold their balances and credit lines.
Comenity Bank vs Traditional Banks: Feature and Product Comparison
To understand how Comenity Bank stacks up against traditional brick-and-mortar and established digital banks, it is necessary to evaluate core banking and credit features side by side. The following comparison highlights key operational differences between Comenity Bank, a traditional national bank, and a digital-first fintech issuer.
| Feature / Metric | Comenity Bank | Traditional National Bank (e.g., Chase) | Digital-First Fintech / Neobank |
|---|---|---|---|
| Primary Focus | Retail co-branded credit cards & online savings | Full-service banking, mortgages, checking, wealth management | Fee-free checking, automated budgeting, crypto/investment tools |
| Savings APY (2026 Benchmark) | Competitive high-yield variable rates | Low standard rates (often near 0.01% on basic tiers) | High-yield variable rates matching top online banks |
| Physical Branch Access | None (100% online and phone-based service) | Extensive physical branch and ATM networks | Minimal to none; relies on partner ATM networks |
| Credit Card Portfolio | Primarily store-branded and closed-loop/open-loop retail cards | Premium travel, cash-back, and business credit cards | Secured credit cards or basic unsecured cards for credit-building |
| Customer Support Channels | Phone, secure online messaging, mobile app | In-branch, 24/7 phone support, chat bots, secure messaging | In-app chat, email, limited phone support |
Evaluating Credit Card Offerings: Comenity vs General-Purpose Issuers
The core of Comenity Bank's business remains its extensive portfolio of retail credit cards. When consumers weigh a Comenity store card against a general-purpose cash-back card from issuers like Capital One or Discover, several distinct trade-offs emerge.
Retail Rewards and Brand Loyalty
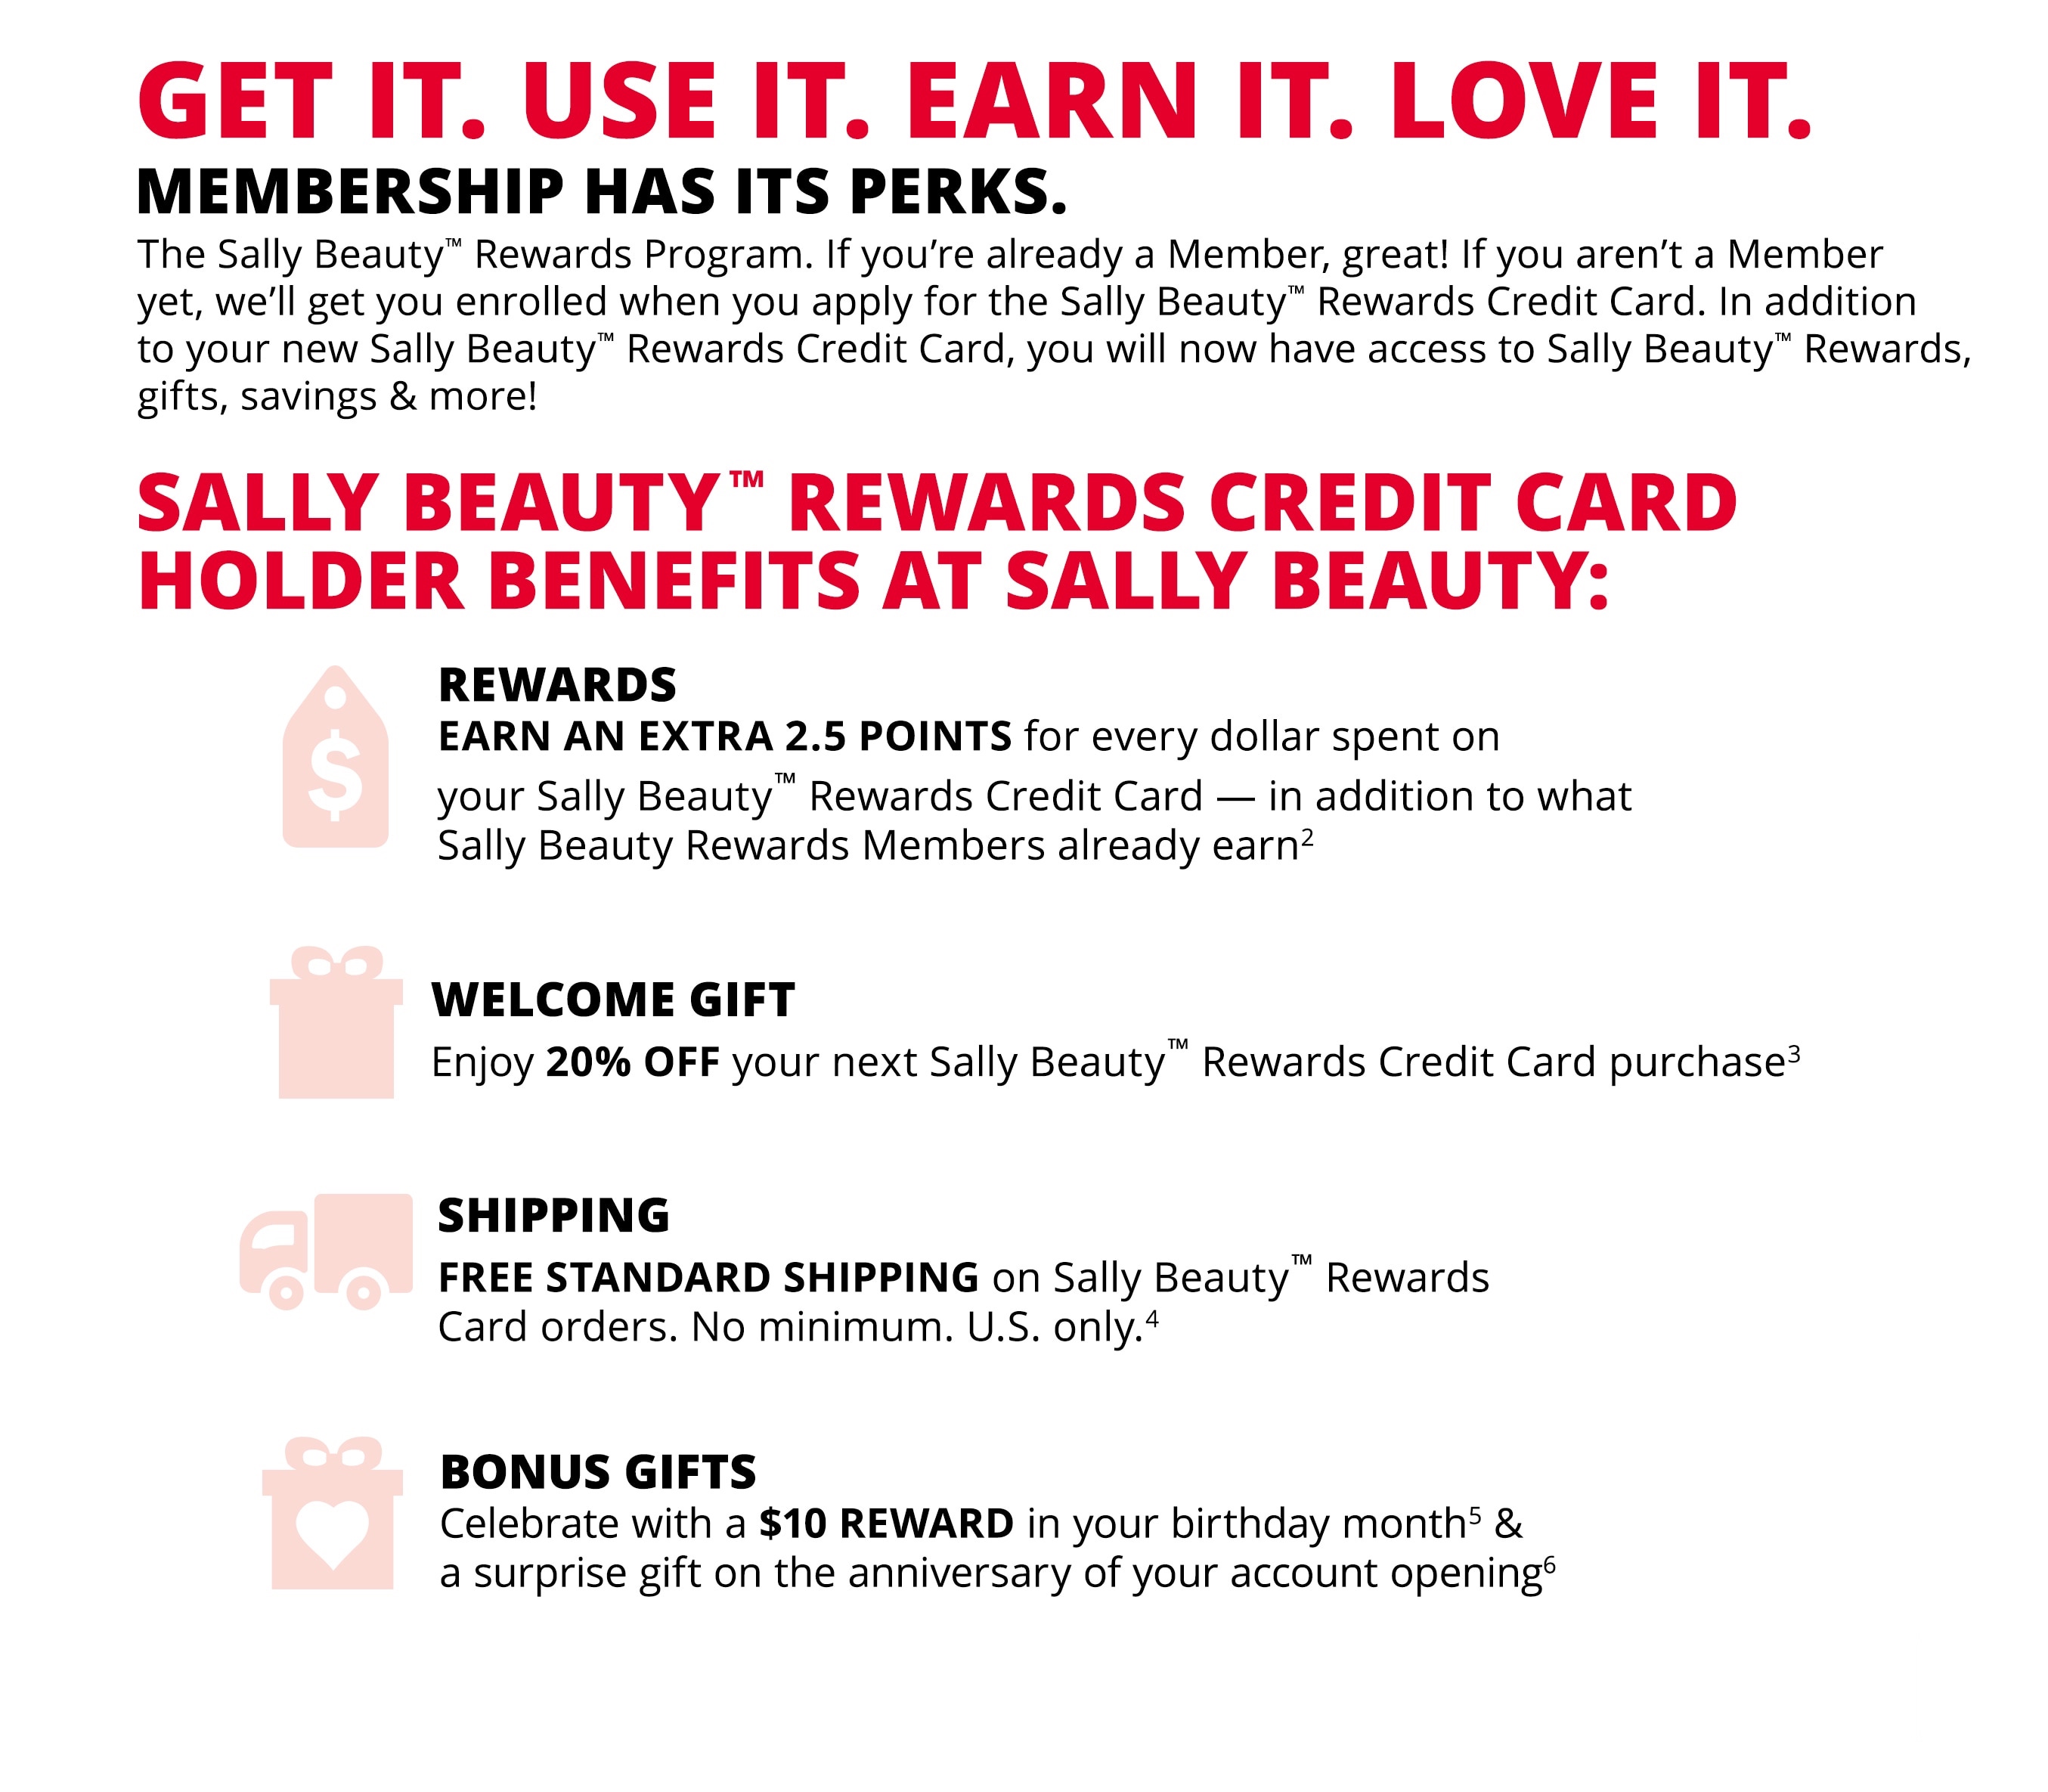
Comenity-issued cards often provide steep initial discounts (such as 15% to 20% off a first purchase) and ongoing perks like birthday rewards, free shipping, or elevated point multipliers within specific merchant families. For loyal shoppers of a particular brand, these benefits can outweigh standard flat-rate cash-back cards.
Interest Rates and Penalty APRs
Because retail credit cards generally carry higher average variable Annual Percentage Rates (APRs) compared to traditional bank credit cards, carrying a balance on a Comenity card can quickly erode any rewards earned. General-purpose cards frequently offer 0% introductory APR periods on balance transfers and purchases lasting 12 to 21 months, whereas many Comenity retail cards feature limited or no introductory low-rate windows.
Credit Score Requirements
Many Comenity retail cards feature accessible approval criteria, making them viable options for consumers building or rebuilding their credit profiles. In contrast, premium travel and rewards cards from major issuers often require good to excellent credit scores (typically 670 and above) for approval.
Comenity Savings Products vs Dedicated Online Banks
Beyond credit cards, Comenity Bank offers online savings accounts and time deposits. When compared to dedicated online banking competitors like Ally Bank, Marcus by Goldman Sachs, or Capital One 360, Comenity's deposit division presents specific advantages and limitations.
- Competitive Yields: Comenity consistently maintains savings account Annual Percentage Yields (APYs) that rank competitively within national online banking averages, appealing to savers seeking growth without locking funds into long-term vehicles.
- Fee Transparency: Comenity online savings accounts typically feature no monthly maintenance fees and no minimum balance requirements to earn interest, aligning with modern digital banking standards.
- Limited Digital Tooling: Unlike advanced fintech apps that offer automated round-ups, granular spending categorization, and integrated budgeting dashboards, Comenity's online portal focuses strictly on core account management and transfers.
- Absence of Checking Accounts: Comenity does not currently offer consumer checking accounts or debit cards for its deposit holders, requiring customers to link an external bank account at another institution for everyday transactional needs.
Pros and Cons of Banking and Financing with Comenity
Analyzing the institutional strengths and weaknesses of Comenity Bank helps clarify whether its financial products align with specific consumer goals.
Advantages
- Specialized Brand Rewards: Excellent point structures and loyalty perks for frequent shoppers of partner retailers.
- Accessible Credit Limits: Broader acceptance criteria for retail cards, offering opportunities for credit profile development.
- Solid Savings Rates: High-yield savings options that outperform traditional brick-and-mortar savings accounts.
- Digital Account Management: Streamlined online portals and mobile applications for tracking credit statements and managing savings goals.
Disadvantages
- Higher APRs on Credit: Elevated interest rates on retail credit cards make them costly if balances are not paid in full each month.
- Customer Service Variability: Support experiences can vary depending on whether the inquiry pertains to a co-branded retail card or a direct savings account.
- No Checking Integration: The lack of a transactional checking account or debit card limits its use as a primary, standalone financial hub.
- Customer Service Wait Times: Peak shopping seasons can lead to longer hold times when contacting support for retail credit inquiries.
Step-by-Step Guide: Choosing Between Comenity and Competitors
Selecting the right financial institution depends heavily on your immediate financial objectives, whether you are looking for retail financing, credit-building opportunities, or a place to park liquid cash.
- Audit Your Spending Habits: Review your monthly purchases to determine if you spend a significant amount with specific retail brands that partner with Comenity. If yes, a co-branded card may yield valuable perks.
- Evaluate Your Credit Strategy: If you intend to carry a monthly balance, prioritize general-purpose cards with low-interest profiles or 0% APR promotional windows rather than standard retail store cards.
- Compare Current Deposit Yields: Check real-time APY rates across Comenity and top online competitors before opening a high-yield savings account to ensure you secure the most competitive return for your emergency fund.
- Assess Ecosystem Integration: Ensure you are comfortable maintaining a primary checking account elsewhere, as Comenity's deposit products are designed strictly for savings rather than everyday spending.
Frequently Asked Questions
Is Comenity Bank a legitimate and secure financial institution?
Yes, Comenity Bank is a legitimate FDIC-insured institution (FDIC Certificate #57398), meaning eligible deposits are protected up to standard federal limits. It operates as a subsidiary of Bread Financial, a publicly traded financial services company.
How do Comenity credit card interest rates compare to major banks?
Comenity retail credit cards typically carry variable APRs that skew higher than standard general-purpose bank credit cards, often exceeding 29% depending on market indexes and specific brand agreements.
Does Comenity Bank charge monthly fees on its savings accounts?
No, Comenity Bank online savings accounts generally do not charge monthly maintenance fees or require high minimum balances to earn interest or keep the account active.
Can I use a Comenity savings account for everyday checking and bill pay?
No, Comenity's deposit platform focuses exclusively on high-yield savings and certificates of deposit, meaning you must transfer funds to an external checking account to execute everyday purchases or bill payments.
How can I contact Comenity customer service regarding a retail credit card?
You can reach Comenity customer service through the specific brand portal associated with your credit card, via the official mobile application, or by calling the dedicated toll-free customer care number listed on the back of your credit card.
Conclusion
Navigating the financial landscape in 2026 requires balancing specialized rewards against structural costs. While Comenity Bank provides compelling high-yield savings yields and targeted retail credit card perks, it functions best as a complementary financial tool rather than a primary, all-in-one banking provider. Consumers should carefully weigh the higher APRs of retail credit lines against the specific loyalty benefits offered, while utilizing Comenity's competitive savings products to maximize returns on liquid capital alongside primary checking accounts from established institutions.