Improving your credit score quickly requires targeting the specific metrics that credit scoring models calculate, such as credit utilization, payment history, and credit mix. By addressing errors on your credit reports, paying down high balances, requesting credit limit increases, and becoming an authorized user, you can often see measurable improvements in your score within 30 to 45 days.
Navigating the credit scoring ecosystem can feel overwhelming, especially when you need a higher score quickly for a major financial move, such as applying for a mortgage, securing an auto loan, or renting an apartment. While building stellar credit is typically a marathon, certain tactical adjustments can yield rapid improvements. Because major credit bureaus update their data monthly when lenders report account activity, targeted interventions can shift your numbers in weeks rather than years.
Understanding how scoring models like FICO and VantageScore weigh your financial behavior helps you prioritize which steps to take first. Rather than guessing what might work, focusing on proven, data-driven methods ensures that your time and financial resources are deployed for maximum impact.
1. Correct Errors on Your Credit Reports
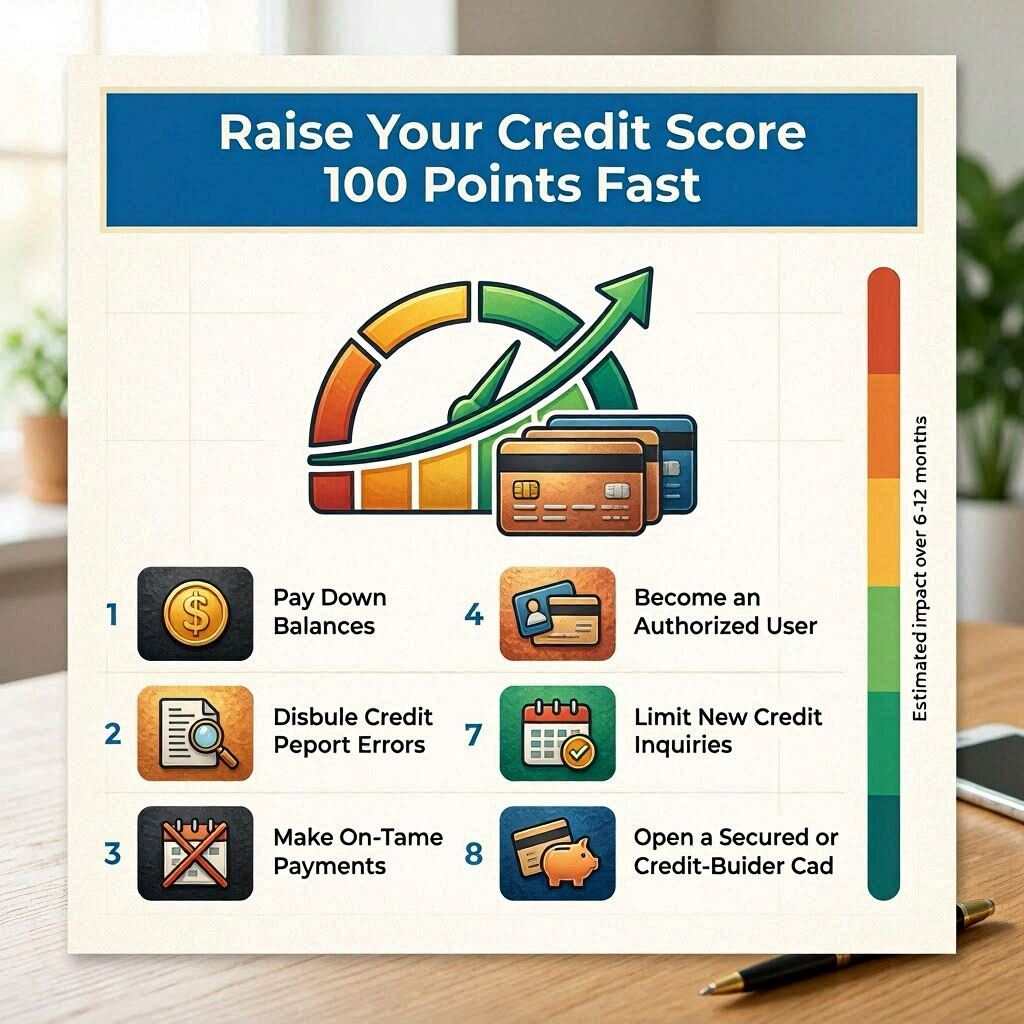
One of the fastest ways to see a dramatic jump in your credit score is to dispute and remove inaccurate negative information from your credit reports. Mistakes are more common than many realize; they can range from misspelled names and misreported late payments to entirely foreign accounts resulting from mixed files or identity theft.
How to Execute This Strategy
Under the Fair Credit Reporting Act (FCRA), you are legally entitled to a free copy of your credit report every week from the three major credit bureaus—Equifax, Experian, and TransUnion—via AnnualCreditReport.com.
- Review Thoroughly: Examine each report line by line. Look for unfamiliar accounts, incorrect balances, or accounts listed as delinquent when you paid on time.
- File a Dispute: If you find an error, file a dispute directly with the credit bureau that holds the incorrect information. You can do this online, by phone, or via certified mail. Include documentation that supports your claim, such as bank statements or cancellation receipts.
- Wait for Investigation: By law, credit bureaus generally have 30 days to investigate and respond to your dispute. If the furnisher of the information cannot verify its accuracy, the error must be removed, which can instantly elevate your credit score.
2. Pay Down Revolving Debt to Lower Your Credit Utilization
Your credit utilization ratio—the amount of revolving credit you are currently using compared to your total credit limit—is the second most influential factor in your FICO score, accounting for 30% of your total calculation. Lowering this ratio is the single most reliable method for engineering a rapid score increase.
Mechanics of Credit Utilization
Credit utilization is evaluated both overall and on a per-card basis. Scoring models generally reward a total utilization rate below 30%, but elite scores typically feature a utilization rate under 10%.
- The Math: If you have a total credit limit of $10,000 across all your cards and your total balance is $5,000, your utilization is 50%. Paying that balance down to $1,000 drops your utilization to 10%.
- The Timing: Lenders typically report your balance to the credit bureaus on your statement closing date, not your due date. To see a fast score boost, pay down your balances before the statement closing date so a low balance is what gets reported.
3. Request Credit Limit Increases
If you cannot immediately inject cash into paying down your balances, you can artificially improve your credit utilization ratio by asking your existing creditors for a credit limit increase.
Best Practices for Limit Increases
- Check for Soft Pulls: Many credit card issuers allow you to request a limit increase online or via their mobile app without triggering a hard inquiry on your credit report. A hard inquiry can temporarily dip your score by a few points, whereas a soft inquiry has no impact.
- Maintain Spending Discipline: The golden rule of this strategy is that your spending habits must remain static. If your credit limit increases from $5,000 to $10,000 and your balance is $2,000, your utilization drops from 40% to 20%. However, if you use the new room to spend an additional $3,000, your utilization will worsen, damaging your score.
- Timing: Generally, issuers prefer that you have held the account for at least six months and have a consistent record of on-time payments before approving a limit increase.
4. Become an Authorized User on an Established Account
Piggybacking on someone else's good credit history is a fast-track method to inject positive payment history and age into your credit profile. When you become an authorized user on a seasoned account with a high limit and zero late payments, that entire account history can be added to your credit report.
Evaluating Authorized User Potential
- Choose Wisely: The primary account holder must have a pristine payment history and low utilization on that specific card. If the primary user misses a payment or maxes out the card, those negative marks will also reflect on your credit report.
- Issuer Reporting: Ensure the credit card issuer reports authorized user data to all three major credit bureaus. Most major banks do, but it is prudent to verify before being added.
- No Financial Liability: As an authorized user, you gain the benefit of the positive tradeline without bearing legal liability for the debt balance, though you should clarify expectations with the primary cardholder regarding physical card usage.
5. Pay Bills Multiple Times a Month
Waiting for your monthly billing cycle to make a single payment can leave your credit utilization artificially inflated for weeks, even if you pay your bill in full every month.
Micro-Payments and Statement Cycles
Credit card companies report your balance to the bureaus once a month on the statement closing date. By making micro-payments—such as paying your balance every two weeks or immediately after every major purchase—you ensure that the balance reported to the credit bureaus is consistently near zero. This micro-management of your account prevents high interim balances from dragging down your score during the calculation cycle.
6. Negotiate a "Pay for Delete" with Collection Agencies
If you have collection accounts dragging down your credit history, settling them does not automatically remove them from your credit report under standard scoring models like FICO Score 8. Older models factor paid collections differently, but unpaid collections severely damage your profile.
Negotiating Collections
- The Agreement: Contact the collection agency and propose a "Pay for Delete" arrangement. Offer to pay the collection amount in full (or a settled percentage) in exchange for the agency completely removing the collection tradeline from all three credit bureaus.
- Get It in Writing: Never send money or agree to terms over the phone without securing a written agreement from the collection agency stating they will delete the record upon receipt of payment. Once paid, monitor your reports to ensure compliance.
7. Ask Creditors for Goodwill Deletions
If you have a past-due payment or a single late mark on an otherwise immaculate credit history, you can write a goodwill letter to the creditor asking them to remove the derogatory mark as a gesture of goodwill.
Crafting a Goodwill Letter
- Acknowledge and Explain: Take responsibility for the late payment, briefly explain the extenuating circumstances that caused it (such as a temporary medical emergency or job transition), and emphasize that your account is now current and in good standing.
- Target the Right Audience: Send the letter to the executive customer service department or the original creditor rather than a front-line customer service representative who lacks the authority to alter reporting data. While creditors are not obligated to grant goodwill deletions, many do for loyal, long-term customers.
8. Add Alternative Data with Rent and Utility Reporting
Traditional credit scoring models rely heavily on revolving credit and installment loans, leaving individuals with thin credit files or no traditional credit cards at a disadvantage. Services like Experian Boost allow you to integrate everyday bills into your credit profile.
How Alternative Reporting Works
Services connect to your bank account to identify recurring payments for utilities, mobile phone bills, and streaming services. If you have a consistent history of paying these bills on time, this data is factored into your Experian credit file immediately, often resulting in an instant score bump for thin or moderate files.
9. Avoid Applying for New Credit Unnecessarily
Every time you formally apply for a new loan or credit card, the lender initiates a hard inquiry on your credit report. While a single hard inquiry usually drops your score by fewer than five points, multiple inquiries in a short window signal financial distress to scoring models.
Managing Inquiries
- Pre-Qualification Tools: Whenever possible, use soft-pull pre-qualification tools to check your approval odds before submitting a formal application.
- Rate Shopping Exception: Scoring models recognize that consumers shop around for the best rates on major loans (such as mortgages or auto loans). Multiple inquiries for the same type of loan within a 14-to-45-day window are typically counted as a single inquiry, protecting your score during focused comparison shopping.
10. Keep Old Accounts Open
A common misconception is that closing an inactive credit card improves your credit score. In reality, closing an old account can harm your score in two distinct ways: it shortens your average length of credit history, and it instantly reduces your total available credit limit, which spikes your credit utilization ratio.
Preserving Account Age
Even if you no longer use a specific credit card, keep the account open—provided it does not carry an annual fee. To prevent the issuer from closing the account due to inactivity, charge a small, recurring subscription to the card and set up automatic payments to pay the balance in full every month.
Credit Improvement Strategy Comparison
| Strategy | Speed of Impact | Difficulty Level | Primary Metric Affected | Cost |
|---|---|---|---|---|
| Dispute Report Errors | Fast (30 days) | Moderate | Accuracy / Negative Marks | Free |
| Lower Credit Utilization | Immediate (Next cycle) | Low to Moderate | Amounts Owed (30%) | Varies (Repayment funds) |
| Request Limit Increases | Fast (1–7 days) | Low | Amounts Owed (30%) | Free |
| Authorized User Status | Fast (30–45 days) | Low | Payment History & Age | Free or negotiated |
| Pay for Delete | Moderate (30–60 days) | Moderate | Negative Collections | Settled debt amount |
Frequently Asked Questions
How fast can my credit score realistically improve?
You can see score changes within 30 to 45 days if you lower your credit utilization, become an authorized user on a seasoned account, or successfully remove an error from your credit report. Credit card issuers typically report your updated balance and payment status to the major credit bureaus once a month, usually around your statement closing date.
Does paying off a collection account immediately raise my score?
Not always with older scoring models, though newer scoring models like FICO 9 and FICO 10 ignore paid collection accounts entirely. However, unpaid collections are viewed as active risks by virtually all lenders. Negotiating a "Pay for Delete" or settling the account is crucial for long-term health and manual underwriting reviews.
Will checking my own credit score lower it?
No. Checking your own credit score or pulling your own credit report is classified as a "soft inquiry." Soft inquiries have zero impact on your credit score and can be performed as frequently as you like without penalty. Only "hard inquiries," initiated when you formally apply for credit, affect your score.
Is it better to close old credit cards I no longer use?
No, keeping old cards open is almost always better for your credit score. Closing an old account shortens your average credit history length and reduces your total available credit limit, which automatically drives up your overall credit utilization ratio and can cause your score to drop.
What is considered a good credit score?
While scoring ranges vary depending on the model used, FICO scores generally range from 300 to 850. A score of 670 to 739 is considered good, 740 to 799 is very good, and 800 or above is exceptional. Lenders use these tiers to determine your interest rates and creditworthiness.
Next Steps
Begin your credit improvement journey by pulling your official credit reports from AnnualCreditReport.com to check for accuracy. Simultaneously, calculate your current credit utilization ratio across all revolving accounts. Prioritize paying down balances that sit above the 30% threshold before your next statement closing date, and explore soft-pull limit increase options to maximize your available credit immediately.