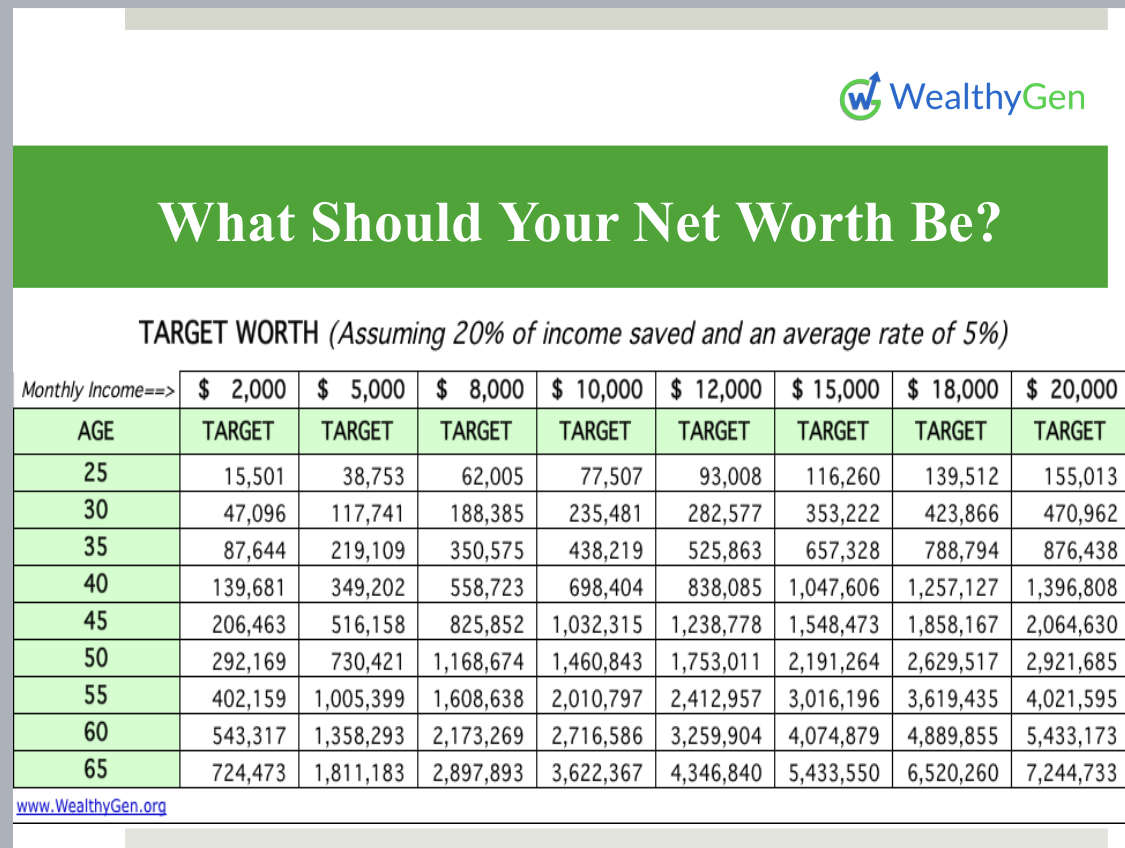
When you encounter the bold assertion, "So you’re telling me that this guy will triple my net worth," you are likely looking at a high-pressure marketing funnel designed to promise rapid financial transformation. In reality, no individual or singular investment strategy can guarantee a tripling of your net worth without commensurate, often extreme, levels of risk. Sustainable wealth accumulation is almost universally a function of time, compound interest, disciplined asset allocation, and risk management rather than the influence of a single person or "secret" system.
The Psychology of Financial Promises
The phrase "this guy will triple my net worth" acts as a powerful hook because it taps into the universal desire for financial security and, more specifically, the shortcut to it. Marketing campaigns that leverage this language often rely on the optimism bias—the tendency for individuals to believe they are less at risk of negative outcomes than others.
When a personality or a financial influencer suggests they can triple your assets, they are often conflating a hypothetical best-case scenario with a reliable investment outcome. Understanding this mechanism is the first step in financial literacy. Financial experts generally categorize such promises as "get-rich-quick" rhetoric, which ignores the fundamental trade-off between risk and reward. In the financial markets, the potential for a 300% return typically requires exposure to volatility that could just as easily result in a 300% loss.
Assessing the Source: Expert vs. Marketer
Distinguishing between a fiduciary advisor and a marketing influencer is critical for your financial health. A fiduciary is legally obligated to act in your best interest, meaning they must prioritize your goals and disclose risks. Conversely, many "gurus" who claim to triple net worth are operating as educators, entertainers, or affiliate marketers.
The Role of Regulatory Oversight
In 2026, financial advertising remains subject to strict regulations by agencies like the Securities and Exchange Commission (SEC) in the United States and the Financial Conduct Authority (FCA) in the UK. These bodies prohibit the guarantee of specific returns. If a program promises to triple your net worth without providing a detailed, risk-adjusted prospectus, it often falls outside the bounds of regulated financial advice.
Red Flags to Watch For
- Absolute Guarantees: Any claim of guaranteed high-percentage returns is a major red flag.
- Lack of Transparency: If the strategy relies on "secret" methods, proprietary algorithms that cannot be audited, or offshore accounts that are difficult to track, caution is required.
- High Upfront Costs: Many programs that promise massive returns require a large initial "coaching" or "access" fee, which may be the only money actually being made by the person selling the strategy.
The Mechanics of Net Worth Growth
Net worth is the difference between your total assets and your total liabilities. To triple it, you must either drastically increase the value of your assets (cash, investments, real estate, businesses) or substantially reduce your liabilities (debt).
The Time-Value Factor
True wealth growth is rarely the result of a single event. It is usually the product of:
- Compound Interest: Reinvesting earnings to generate further earnings over long horizons.
- Asset Allocation: Diversifying investments to mitigate systemic risk.
- Income Production: Increasing the gap between what you earn and what you spend.
Tripling net worth requires either a massive increase in income over a short period or a long-term strategy involving diversified investment vehicles. Any "guy" promising to facilitate this in a short timeframe is likely recommending high-leverage trading or speculative assets, which are essentially forms of gambling, not wealth building.
Comparative Framework: Realistic Growth vs. Speculative Claims
To evaluate any financial proposition, compare it against established market benchmarks. The following table illustrates the difference between standard wealth-building paths and the speculative promises often found in aggressive marketing funnels.
| Feature | Institutional Wealth Building | Speculative "Triple My Net Worth" Schemes |
|---|---|---|
| Typical Timeframe | 10 to 30 years | 6 to 24 months |
| Risk Profile | Moderate; diversified | Extremely high; concentrated |
| Methodology | Asset allocation; low-cost index funds | Proprietary strategies; high leverage |
| Transparency | Public financial records/Prospectuses | Private coaching/Exclusive "insider" access |
| Primary Goal | Compounding; inflation hedging | Rapid capital appreciation |
| Regulatory Status | Regulated/Fiduciary oversight | Often unregulated/Educational disclaimer |
The Role of Leverage and Risk
The only way to "triple" wealth quickly is through leverage—using borrowed money or derivatives to amplify the effect of price changes. While leverage can lead to a 300% increase in net worth if the market moves in your favor, it can also lead to total insolvency if it moves against you.
When a promoter claims to triple your net worth, they are likely ignoring the downside capture. Before engaging with any strategy that claims such aggressive growth, ask yourself: "How much of my current net worth am I willing to lose?" If the strategy does not have a clear answer for loss mitigation, it is not a financial plan; it is a high-stakes gamble.
Practical Steps for Vetting Financial Influencers
Before committing your capital, perform a due diligence check on the individual or program making the claim.
- Background Check: Search for the person’s professional history on the FINRA BrokerCheck tool or local equivalents. See if they are a registered investment advisor.
- Historical Performance: Ask for audited statements. A professional will have a track record verified by a third-party accounting firm. If they cannot provide this, assume the performance is hypothetical or fabricated.
- Cost-Benefit Analysis: If the program costs $5,000 to join, calculate the return on investment you need just to break even. Often, the cost of the "secret" program is the primary expense that hinders the very wealth creation it promises.
- Conflict of Interest: Understand how the person is compensated. If they earn a commission for getting you to sign up for a specific platform or buy a specific product, their advice is inherently biased.
Common Pitfalls and Troubleshooting
Many individuals lose significant capital by falling for the "so you’re telling me" narrative. The most common mistake is the failure to maintain an "emergency fund." Wealth building should always be built on a foundation of liquid cash that can cover 3–6 months of living expenses. If you divert your emergency fund into a speculative scheme, you are at risk of a "liquidity crunch," where you might be forced to sell assets at a loss because you cannot cover your immediate obligations.
If you find yourself already involved in such a program and suspect it is not yielding the promised results:
- Stop the bleeding: Avoid putting more capital into the program.
- Audit your accounts: Pull all bank and brokerage statements to see exactly where your money has gone.
- Seek neutral advice: Consult with a fee-only Certified Financial Planner (CFP) who has no stake in the program you joined. They can provide an objective assessment of your current financial position and help you build a legitimate, sustainable recovery plan.
Conclusion: Sustainable Wealth Over Shortcuts
Wealth is generally not created by a single "guy" or a singular "trick." It is the outcome of consistent behavior, patience, and the avoidance of catastrophic financial errors. While the promise of tripling your net worth in a short timeframe is alluring, it is almost exclusively rooted in speculative behavior rather than sound financial science.
Focus on the levers you can control: your savings rate, your tax efficiency, and the diversification of your investments. If you are looking to accelerate your growth, look toward increasing your human capital—improving your skills, earning power, and business acumen—rather than looking for an external figure to manage your financial destiny. True financial freedom is a marathon, not a sprint, and it requires protecting your capital more aggressively than you pursue high returns.