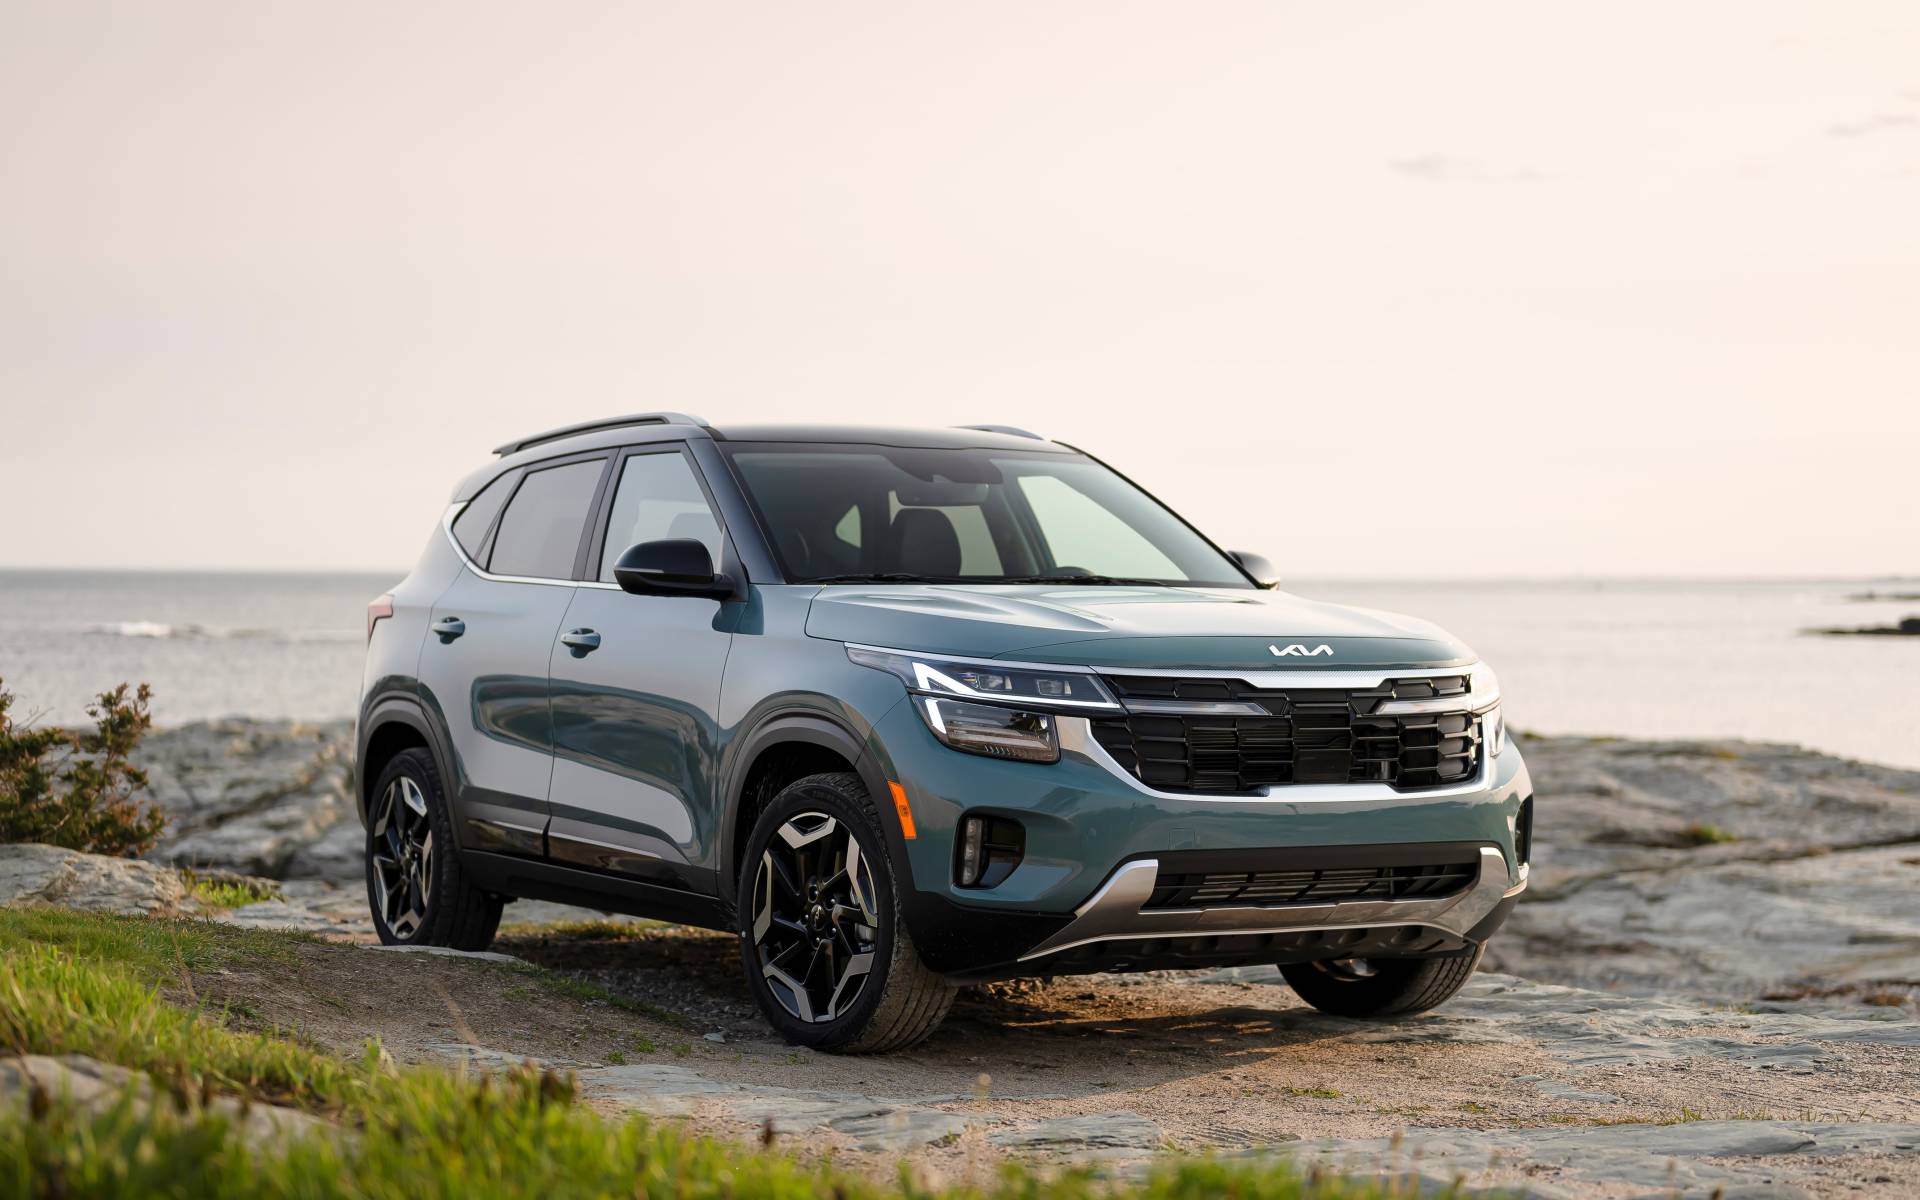
Navigating the automotive market for affordable utility vehicles requires a nuanced understanding of current financing structures, residual values, and manufacturer incentives. Securing cheap SUV leases in 2026 involves more than simply looking at the lowest monthly payment advertised on a billboard; it demands a strategic breakdown of capital cost reductions, mileage allowances, and localized tax impacts. This guide provides an analytical framework for identifying genuine lease value, dissecting lease contracts, and leveraging 2026 market dynamics to minimize your total cost of driving.
Unpacking 2026 Market Dynamics for Affordable Crossovers
The landscape of affordable SUV leasing has shifted significantly. Supply chain stabilization has driven inventory levels back to pre-pandemic baselines, yet interest rate fluctuations and residual value adjustments mean that monthly payments require careful auditing. Subcompact and compact crossovers continue to dominate the budget segment, offering a balance of utility, fuel economy, and lower capital costs.
Manufacturers frequently utilize subsidized leases—often called subvented leases—to move inventory off dealership lots. These programs artificially inflate the residual value or lower the money factor (the interest rate on a lease) to create artificially reduced monthly payments.
- Subvented Money Factors: Captive finance companies like Toyota Financial Services, Honda Financial Services, and Hyundai Motor Finance offer promotional interest rates that outperform traditional bank loans.
- Residual Value Resilience: Vehicles that retain higher percentages of their Manufacturer's Suggested Retail Price (MSRP) over a 36-month period yield lower monthly payments because you only finance the depreciation.
- Capital Cost Reductions: Minimizing cash down payments remains a core strategy for financial safety, mitigating total loss exposure if the vehicle is totaled shortly after delivery.
Evaluating Top Budget SUV Lease Contenders for 2026
When targeting affordability, categorizing vehicles by class helps isolate true value. Subcompact SUVs offer the lowest entry barrier, while compact options provide necessary cargo capacity without heavily inflating the payment structure.
| Make and Model | Class | Estimated Monthly Payment Range | Standard Mileage Allowance | Projected Residual Strength |
|---|---|---|---|---|
| Hyundai Kona | Subcompact | $239 - $289 / month | 10,000 miles/year | Moderate-High |
| Kia Seltos | Subcompact | $249 - $299 / month | 10,000 miles/year | Moderate |
| Chevrolet Trax | Subcompact | $199 - $249 / month | 10,000 miles/year | Moderate |
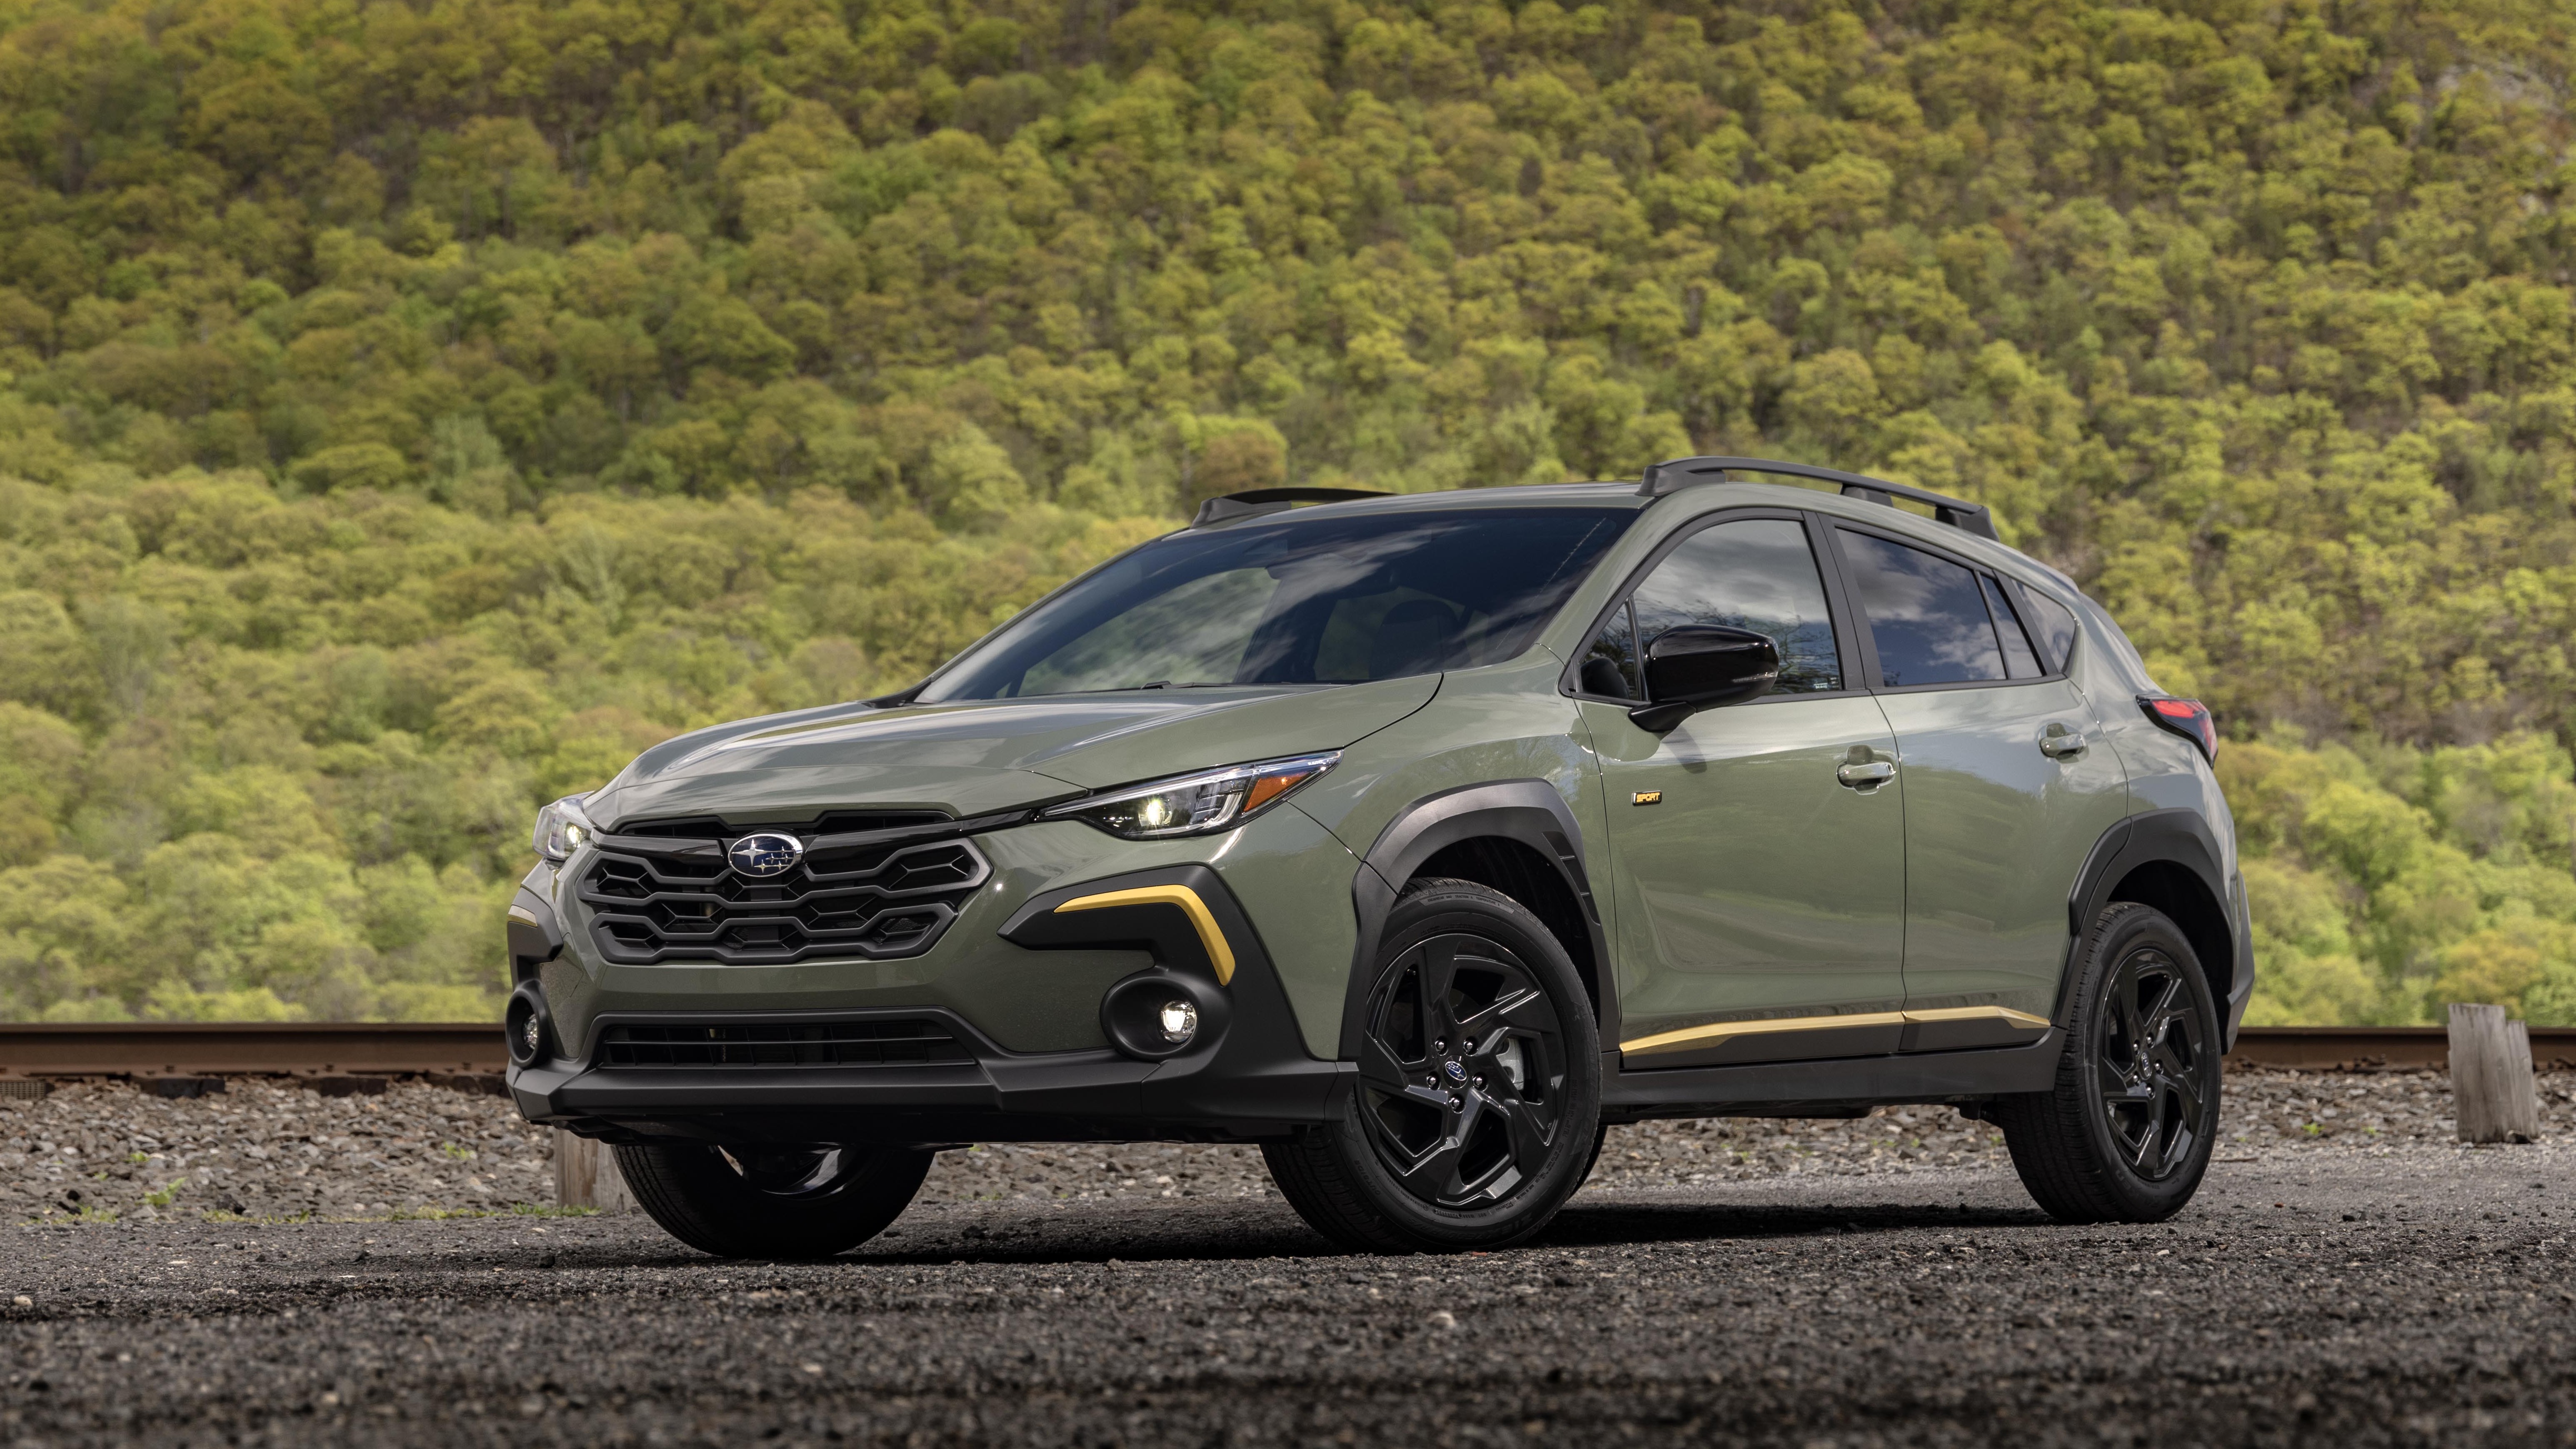
| Subaru Crosstrek | Compact Crossover | $279 - $329 / month | 12,000 miles/year | High |
| Nissan Kicks | Subcompact | $219 - $269 / month | 10,000 miles/year | Lower-Moderate |
The Chevrolet Trax continues to serve as an entry point for buyers prioritizing a low baseline payment, while the Subaru Crosstrek balances a slightly higher monthly commitment with standard all-wheel drive and a historically high residual value, which protects against equity loss.
The Financial Mechanics of a Low-Cost Lease Contract
To secure a genuinely cheap SUV lease, you must master the core mathematical components that dictate your monthly obligation. Dealerships often focus your attention exclusively on the monthly payment, which can mask inflated capitalized costs or hidden fees.
Core Lease Calculation Factors
Capitalized Cost: The negotiated selling price of the vehicle. Always negotiate this price independently of the lease structure as if you were making a cash purchase.
Residual Value: The predetermined value of the vehicle at the end of the lease term, expressed as a percentage of the MSRP. A higher residual value directly lowers your monthly depreciation charge.
Money Factor: The financial coefficient used to calculate the rent charge (interest). Multiply the money factor by 2,400 to convert it to an approximate equivalent Annual Percentage Rate (APR).
Hidden Costs to Monitor
- Acquisition Fee: Typically ranging from $595 to $995, this is charged by the leasing company to set up the account.
- Disposition Fee: Ranging from $300 to $500, due at lease-end unless you purchase the vehicle or lease another model from the same brand.
- Documentation and State Fees: Mandatory state registration, title, and local documentation fees that vary by jurisdiction.
Step-by-Step Strategy to Secure the Best Lease Deal
Executing a successful lease transaction requires a methodical approach that removes emotional decision-making from the showroom floor.
- Research Target Incentives: Check manufacturer websites for current regional lease specials, loyalty programs, and college graduate or military rebates applicable in 2026.
- Negotiate the Selling Price First: Treat the transaction as a purchase negotiation. Email local fleet or internet sales managers to solicit competitive quotes on the capitalized cost.
- Insist on a Zero Down Payment Structure: Avoid putting cash down toward the capitalized cost reduction. If the vehicle is stolen or totaled on the drive home, insurance payouts settle the actual cash value, and upfront cash payments are typically unrecoverable.
- Audit the Money Factor: Ask the dealer for the exact buy-rate money factor provided by the captive finance company. Ensure they are not marking it up for additional profit.
- Review Mileage Terms: Align the annual mileage cap (typically 10,000, 12,000, or 15,000 miles) with your actual driving habits to avoid steep overage penalties ranging from $0.15 to $0.25 per mile.
Pros and Cons of Leasing an Affordable SUV
Understanding the structural advantages and disadvantages of leasing ensures you select the right acquisition method for your lifestyle and financial goals.
Advantages
- Lower Monthly Payments: Lease payments are consistently lower than equivalent finance payments because you only pay for the vehicle's projected depreciation during the term.
- Warranty Coverage: Most lease terms (typically 36 months) run concurrently with the manufacturer's bumper-to-bumper warranty, eliminating major mechanical repair financial risks.
- Technological Upgrades: At the end of a short-term lease, you can easily transition into newer models equipped with updated safety technology and improved fuel efficiency standards.
Disadvantages
- Mileage Restrictions: Exceeding contracted mileage limits triggers expensive penalty fees at lease termination.
- No Equity Retention: Unless the vehicle's market value exceeds the residual value at lease-end (allowing you to buy it out and sell it), you build no physical equity in the asset.
- Wear and Tear Charges: Excessive interior wear, dents, scratches, or mismatched tires will result in penalty assessments upon return inspection.
Frequently Asked Questions
Is it better to put money down on a cheap SUV lease?
No, financial experts generally advise against putting money down on a lease. Paying cash upfront to lower the monthly payment does not reduce the total cost of the lease and puts that cash at immediate risk if the vehicle is totaled or stolen.
What credit score is required to qualify for advertised cheap lease deals?
Most Tier-1 promotional lease rates advertised by manufacturers require a FICO score of 720 or higher. Individuals with lower credit scores may still lease a vehicle, but the money factor will increase, resulting in a higher monthly payment.
Can I negotiate the residual value of a leased SUV?
No, the residual value is permanently fixed by the leasing company or captive lender based on forecasted market depreciation and cannot be negotiated by the dealership.
What happens if I exceed the mileage limit on my SUV lease?
Exceeding your mileage limit results in a per-mile penalty fee specified in your contract, usually ranging from 15 to 25 cents per mile. If you anticipate heavy driving, it is significantly cheaper to purchase higher mileage tiers upfront at contract inception.
Can I terminate my SUV lease early without penalties?
Early lease termination is legally complex and expensive, typically requiring you to pay the remaining depreciation balance, early termination fees, and local taxes. Alternatives include lease transfers through specialized assumption platforms or purchasing the vehicle outright.
Conclusion
Securing a cheap SUV lease in 2026 requires strict adherence to financial principles, careful negotiation of the underlying capitalized cost, and avoidance of unnecessary upfront cash outlays. By focusing on subvented promotional rates, maintaining awareness of hidden fees, and accurately matching your mileage needs, you can secure reliable utility vehicle transportation while protecting your monthly cash flow.