Accumulating a $130,000 net worth by age 25 requires a deliberate combination of early income acceleration, aggressive savings rates, and strategic asset allocation. Reaching this milestone demands a distinct departure from standard consumer habits, shifting focus toward maximizing human capital, minimizing liabilities, and deploying capital into compounding investments well before the typical onset of peak earning years.
Understanding the Financial Landscape at Age 25
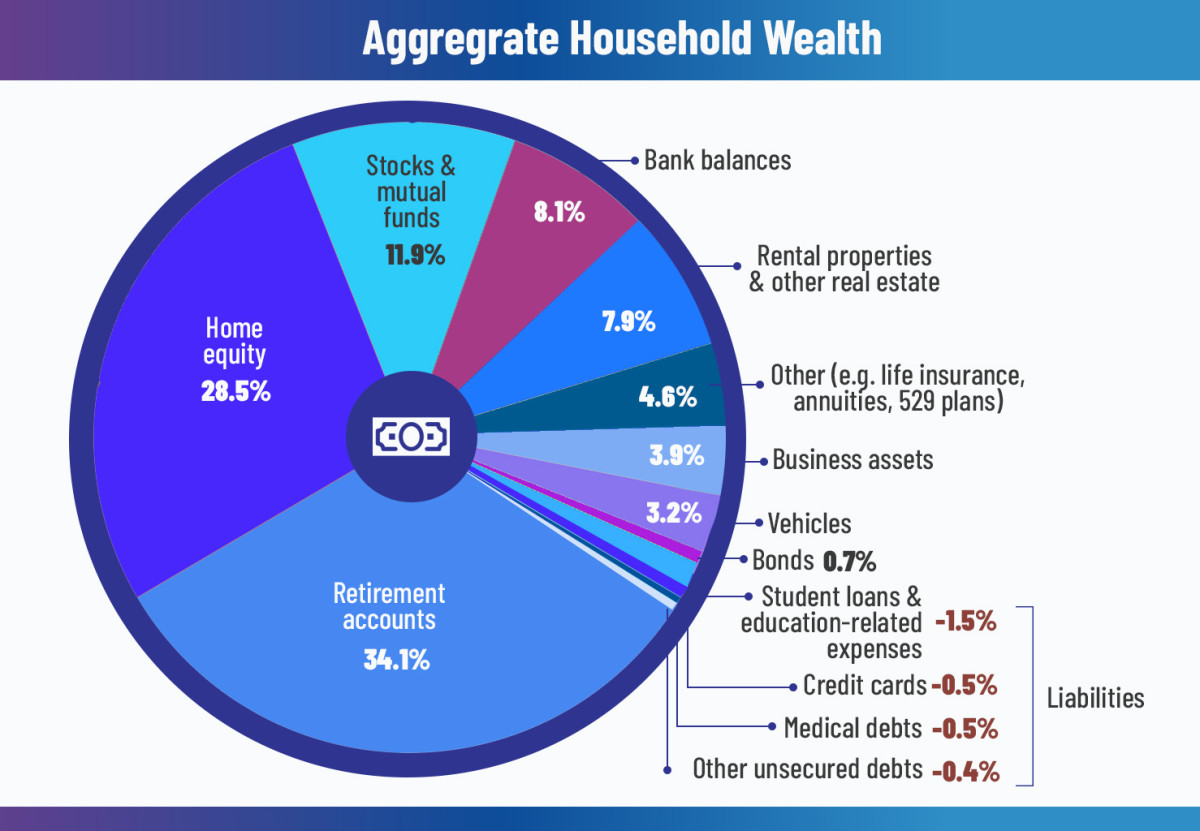
Reaching a six-figure-plus net worth by your mid-twenties places an individual significantly ahead of generational medians. According to data from the Federal Reserve's Survey of Consumer Finances, the median net worth for households under the age of 35 is substantially lower, making a $130,000 portfolio at 25 an outlier achieved by roughly the top decile of this demographic.
This financial position is rarely reached through a single windfall; rather, it is the cumulative result of early employment earnings, disciplined budgeting, minimal high-interest debt, and early-stage investing. At age 25, time is your most valuable asset. The compounding effect of capital invested during these years provides an exponential advantage over those who begin accumulating wealth in their 30s.
Phase 1: Maximizing Human Capital and Income Acceleration
The foundation of a $130,000 net worth by 25 begins long before investment returns compound—it begins with maximizing earning potential. Relying solely on a modest entry-level salary makes saving six figures exceptionally difficult due to the friction of basic living expenses.
Choosing High-ROI Career Paths
Young adults who achieve high net worths typically focus on high-return-on-investment (ROI) career paths. This includes fields in software engineering, quantitative finance, specialized healthcare, high-ticket technical sales, management consulting, or targeted entrepreneurship.
When formal education costs are kept manageable through scholarships, community college transitions, or public universities, the net return on early career earnings rises dramatically. Avoiding excessive student loan debt prevents negative net worth anchors during the crucial accumulation window from ages 18 to 22.
Cultivating High-Income Side Ventures
Beyond primary employment, accelerating income through scalable side ventures provides additional capital that can be funneled directly into investment vehicles. Effective side income sources share specific traits:
- Low Overhead: Businesses requiring minimal initial capital expenditure.
- Skill-Based: Leveraging specialized software, writing, design, or analytical skills.
- Scalability: Offering services or products that are not strictly traded hour-for-hour for wages.
Phase 2: Mastering the Savings Rate and Cash Flow Control
Income generation alone is insufficient; retaining and converting that income into equity is what builds net worth. A high savings rate is the primary engine of early wealth accumulation.
The Mathematics of the Savings Rate
While conventional financial planning often recommends saving 10% to 15% of income, achieving an accelerated net worth target requires savings rates of 40% to 60%. If an individual earns an average net income of $65,000 per year from ages 21 to 25 and maintains a 50% savings rate, they retain $32,500 annually. Over four years, simple accumulation yields $130,000 even before accounting for investment returns. When combined with market appreciation and compound interest, the target is reached even faster.
Optimizing Fixed and Variable Expenses
To sustain a high savings rate without lifestyle fatigue, focus optimization on the three largest fixed budget items:
- Housing: Securing roommates, living in lower-cost-of-living areas, or staying with family for a transition period post-college.
- Transportation: Driving reliable, depreciated, fuel-efficient vehicles purchased with cash, thereby eliminating auto loan interest and high insurance premiums.
- Food: Minimizing dining out and food delivery services in favor of grocery planning and meal preparation.
Phase 3: Strategic Asset Allocation and Investment Vehicles
Accumulated cash sitting in a standard checking account loses purchasing power to inflation. To transform savings into a $130,000 net worth, capital must be deployed into structured, tax-advantaged, and growth-oriented investment vehicles.
Leveraging Tax-Advantaged Accounts
Maximizing tax-advantaged accounts protects investment gains and reduces taxable income during peak earning years. Young professionals should understand the utility of specific accounts:
- Traditional or Roth 401(k) / 403(b): Particularly when employer matches are offered, contributing enough to capture the full match provides an immediate 100% return on invested capital.
- Roth IRA: Contributions are made with post-tax dollars, but all future growth and withdrawals in retirement are entirely tax-free. For a 25-year-old, a Roth IRA provides decades of tax-free compounding.
- Health Savings Account (HSA): When paired with a High-Deductible Health Plan (HDHP), an HSA offers a triple tax advantage (tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses).
Core Investment Portfolio Structure
A typical asset allocation strategy for a growth-oriented 25-year-old prioritizes equities over fixed-income assets due to a multi-decade time horizon.
| Asset Class | Target Allocation | Primary Purpose | Risk Profile |
|---|---|---|---|
| Broad-Market Index Funds (Equities) | 70% – 85% | Long-term capital appreciation via global stock market exposure. | Moderate-High |
| Growth Stocks / Sector ETFs | 5% – 15% | Tactical exposure to secular growth trends (e.g., technology, energy transition). | High |
| High-Yield Cash Equivalents | 5% – 10% | Emergency reserves and dry powder for market opportunities. | Low |
| Alternative Assets (Crypto/Commodities) | 0% – 5% | Speculative diversification (strictly managed to prevent portfolio ruin). | Very High |
Phase 4: Avoiding Debt Traps and Liability Pitfalls
Building a high net worth requires distinguishing strictly between assets that put money in your pocket and liabilities that drain cash flow.
High-interest consumer debt—such as credit card balances carried month-to-month and high-APR personal loans—acts as an anchor on financial progress. Paying 20% interest on a credit card balance outpaces almost any legitimate investment return. Consequently, maintaining a zero-balance credit discipline, utilizing credit cards solely for rewards while paying them off in full each billing cycle, is mandatory.
Similarly, purchasing a brand-new luxury automobile financed through a long-term, high-interest loan is one of the most common derailments for young earners. Vehicles depreciate rapidly; tying up $30,000 to $50,000 in a depreciating asset limits the capital available for compounding investments.
Phase 5: Common Mistakes in Early Wealth Building
Even high-earning young adults frequently encounter pitfalls that stall net worth progression. Recognizing these errors helps preserve momentum.
- Lifestyle Creep: Automatically increasing spending proportionally with every salary raise or bonus, preventing the savings rate from expanding.
- Chasing Speculative Trends: Allocating significant capital to highly volatile, unverified assets (meme stocks, speculative cryptocurrencies, or unproven startups) hoping for overnight riches.
- Neglecting Emergency Reserves: Failing to maintain a dedicated 3-to-6-month cash cushion, forcing the liquidation of long-term investments during a market downturn or job transition.
- Failing to Track Net Worth: Operating without a clear, periodic accounting of total assets minus total liabilities, which obscures the actual financial trajectory.
Frequently Asked Questions
How is net worth calculated?
Net worth is calculated by subtracting your total liabilities (student loans, credit card balances, auto loans, mortgages) from your total assets (cash savings, investment accounts, vehicle equity, real estate equity). If your assets total $145,000 and your remaining student loans total $15,000, your net worth is $130,000.
Is it better to invest in the stock market or real estate at age 25?
For most 25-year-olds, broad-market stock index funds are more practical than direct real estate investing due to lower capital requirements, instant diversification, and lack of operational management. Real estate requires significant capital for down payments, closing costs, and maintenance reserves, though homeownership or real estate investment trusts (REITs) can be integrated later.
How much should I keep in an emergency fund?
A standard emergency fund covers three to six months of essential living expenses. For a 25-year-old with stable employment, holding this amount in a high-yield savings account (HYSA) ensures liquidity without exposing critical survival funds to market volatility.
How do taxes impact a $130,000 net worth?
Net worth measures the total value of your assets minus liabilities, not your annual income. However, optimizing your tax liability through retirement accounts reduces the drag of capital gains and income taxes, allowing your underlying investments to compound faster.
Next Actions for Building Wealth Young
To transition from financial planning concepts to execution, focus on three immediate steps:
- Calculate Your Baseline: Establish a transparent spreadsheet tracking every asset and liability to determine your exact current net worth.
- Automate Savings: Set up automatic transfers on every payday to route a predetermined percentage of income directly into investment and retirement accounts before discretionary spending occurs.
- Audit Fixed Expenses: Review your last three months of bank and credit card statements to identify and eliminate recurring subscriptions, inefficient housing costs, and unnecessary discretionary spending.