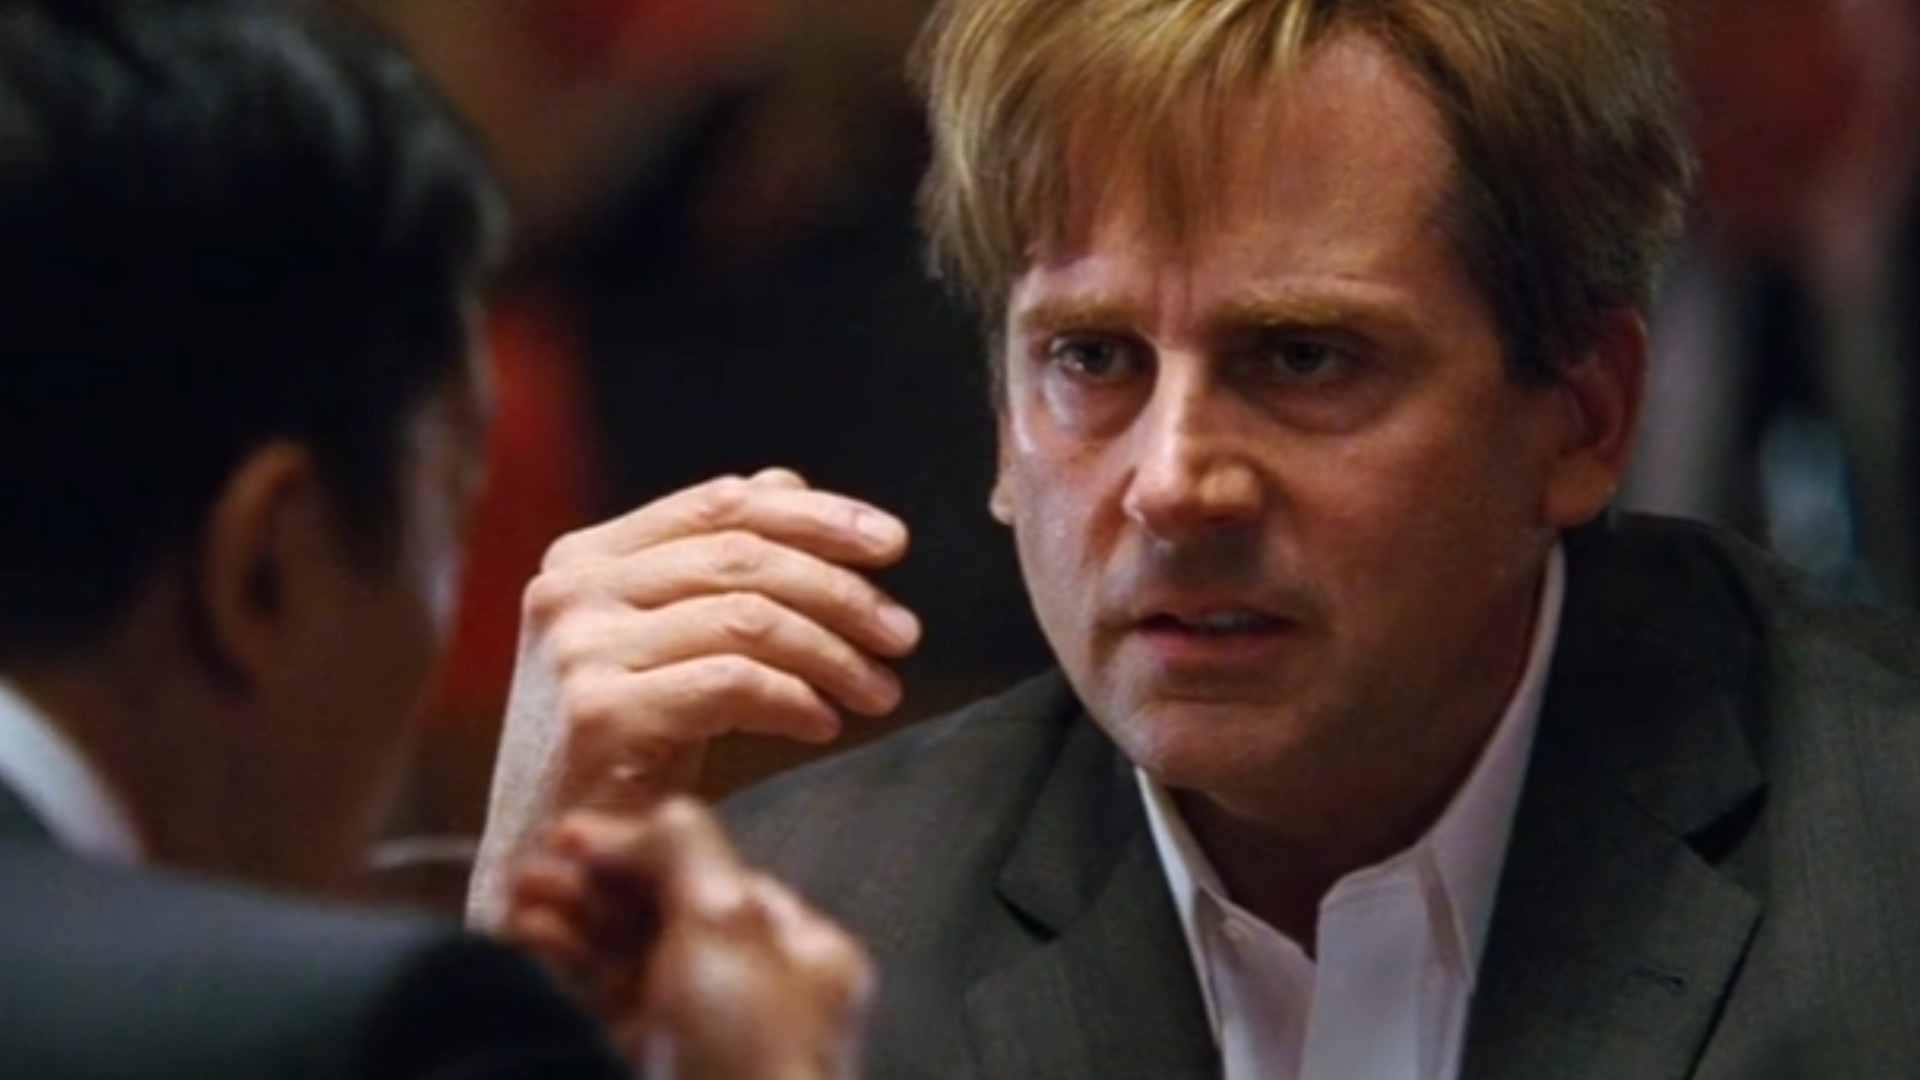
Mark Baum, the outspoken hedge fund manager portrayed by Steve Carell in the 2015 film The Big Short, is the fictionalized version of real-life investor Steve Eisman. As of 2026, Steve Eisman’s estimated net worth is approximately $1.5 billion, a fortune built on his legendary short position against the U.S. housing market in 2008 and his subsequent decades of high-level asset management at firms like Neuberger Berman.
While the film characterizes him as a man driven by moral outrage against a corrupt system, his professional reality is rooted in rigorous fundamental analysis and a contrarian investment philosophy. Understanding the career facts of the man behind the character requires a deep dive into the mechanics of the 2008 financial crisis, the evolution of his investment strategies, and his current standing in the global financial landscape of 2026.
The Disambiguation: Mark Baum vs. Steve Eisman
In Michael Lewis’s book The Big Short and the subsequent film, several names were changed for legal or narrative reasons. Mark Baum is the cinematic surrogate for Steve Eisman. While the film captures Eisman’s intense personality, skepticism, and ultimate vindication, it is important to distinguish between the dramatized "Baum" and the professional "Eisman."
Eisman’s career began not in finance, but in law. After graduating from the University of Pennsylvania and Harvard Law School, he worked as a legal clerk before transitioning to Wall Street as an equity analyst. This legal background likely contributed to the "Mark Baum" persona—a figure obsessed with the fine print of prospectuses and the structural flaws of financial contracts.
The Trade of a Lifetime: Shorting the Housing Bubble
The primary reason for the enduring interest in Mark Baum (Eisman) is his role in predicting and profiting from the 2007-2008 subprime mortgage collapse. Unlike many who simply got lucky, Eisman’s team at FrontPoint Partners (a unit of Morgan Stanley at the time) conducted boots-on-the-ground research that revealed a systemic rot in the American financial system.
The Mechanics of the Short
Eisman did not simply "bet against houses." He targeted Collateralized Debt Obligations (CDOs), specifically the "mezzanine" tranches. These were bundles of subprime mortgages that were rated as investment-grade (BBB or higher) despite being composed of loans to borrowers with poor credit.
His strategy involved purchasing Credit Default Swaps (CDS). A CDS acts as an insurance policy on a bond. By paying a small premium, Eisman’s fund would receive a massive payout if the underlying mortgage bonds defaulted. When the housing market stalled and defaults surged, the value of these swaps skyrocketed.
The Scale of Profit
During the period depicted in The Big Short, Eisman’s fund at FrontPoint reportedly grew from approximately $700 million in assets to over $1.5 billion. While the exact personal payout for Eisman is a matter of private record, the performance fees generated during this period laid the foundation for his current billionaire status. He was one of the few managers who remained solvent and profitable while the institutions around him—including his parent company, Morgan Stanley—faced existential threats.
Career Milestones: Beyond The Big Short
Eisman’s career did not end with the 2008 crisis. His trajectory following the "Big Short" demonstrates a shift from a niche hedge fund manager to a broader institutional leader.
FrontPoint Partners and the Aftermath
Following the success of his subprime short, Eisman continued to manage FrontPoint’s financial services fund. However, the firm faced internal turmoil unrelated to Eisman, leading to his departure in 2011. He subsequently founded EmTrace Capital, though the firm eventually closed as the post-crisis market environment favored passive indexing over aggressive short-selling strategies.
Neuberger Berman (2014–Present)
In 2014, Eisman joined Neuberger Berman as a Managing Director and Senior Portfolio Manager. This move signaled a transition toward long-only and long/short equity strategies for institutional and high-net-worth clients. In 2026, he remains a prominent figure at the firm, overseeing significant assets and providing market commentary that is closely followed by the financial media.
Public Advocacy and Regulatory Testimony
Unlike many hedge fund managers who prefer anonymity, the real-life "Mark Baum" became a vocal critic of certain sectors. He famously testified before Congress regarding the practices of for-profit colleges, arguing that their business models were predatory and destined to fail—a prediction that largely came true as several major chains faced regulatory shutdowns and bankruptcy.
Steve Eisman (Mark Baum) Career Summary and Stats
The following table outlines the key phases of the career that inspired the character of Mark Baum.
| Period | Organization | Role | Key Focus |
|---|---|---|---|
| 1991–2001 | Oppenheimer & Co. | Equity Analyst | Specialty Finance & Banks |
| 2004–2011 | FrontPoint Partners | Portfolio Manager | The Subprime Mortgage Short |
| 2012–2014 | EmTrace Capital | Founder/CIO | Long/Short Financials |
| 2014–2026 | Neuberger Berman | Managing Director | Multi-Cap Equity/Opportunistic |
| 2026 | Global Markets | Senior Strategist | Macro Risk & Financial Valuation |
Analyzing the $1.5 Billion Net Worth in 2026
Determining the net worth of a private hedge fund manager involves analyzing several revenue streams. As of 2026, Eisman’s wealth is derived from three primary sources:
- The 2008 Performance Fees: The carry (performance fee) from the FrontPoint years provided a massive capital base. In the hedge fund world, a 20% performance fee on a billion-dollar gain is $200 million. When compounded over 15+ years of personal investing, this figure grows exponentially.
- Institutional Compensation: As a Managing Director at a firm like Neuberger Berman, which manages hundreds of billions in assets, Eisman commands a significant salary and a share of the management fees generated by his specific funds.
- Personal Investment Portfolio: Eisman is known for a "value-driven" personal portfolio. By applying the same rigorous analysis to his own wealth that he uses for clients, he has likely seen steady growth in a decade of generally rising equity markets (notwithstanding periods of volatility).
It is important to note that net worth figures for individuals in finance are often "paper wealth" tied up in fund stakes and private equity. However, based on his historical earnings and current institutional standing, the $1.5 billion estimate is consistent with industry standards for top-tier hedge fund alumni.
Investment Philosophy: The "Mark Baum" Method
The character in The Big Short is defined by a refusal to trust "the experts." This translates to a specific investment philosophy used by Eisman throughout his career.
Fundamental Skepticism
Eisman’s approach is rooted in the belief that the "narrative" of a stock is often a distraction from the balance sheet. He looks for discrepancies between what a company says and what the data proves. This was evident in his analysis of the ratings agencies (Moody's and S&P) in 2008, where he realized they were incentivized to provide high ratings to bad debt.
Focus on "The Moat"
In the 2026 market environment, Eisman has often discussed the importance of a company’s "moat"—its competitive advantage. He frequently avoids companies that rely on high leverage, a lesson reinforced by the 2008 collapse. His current strategies at Neuberger Berman focus on high-quality earnings and sustainable business models.
Identifying Tail Risks
Eisman is a "tail risk" specialist. He looks for events that are perceived as unlikely by the market but have a high probability of occurring due to structural flaws. While he is often labeled a "short-seller," he has spent much of the last decade as a "long" investor, only shorting when he identifies a specific, systemic catalyst.
The Cultural Legacy of Mark Baum
The character of Mark Baum helped bridge the gap between complex Wall Street mechanics and the general public. Because of The Big Short, the term "shorting" entered the common lexicon. For Steve Eisman, this fame has provided a platform to discuss financial ethics and the necessity of transparency in the banking sector.
In 2026, the "Mark Baum" archetype remains relevant as investors navigate new financial frontiers, from decentralized finance to AI-driven algorithmic trading. The core lesson of the character—and the man—is that no institution is too big to fail if its foundation is built on bad data and misplaced trust.
Frequently Asked Questions
Did Steve Eisman really behave like Mark Baum in real life?
While Steve Carell’s performance is a dramatization, friends and colleagues of Eisman have confirmed that his real-world personality is indeed intense, skeptical, and prone to blunt honesty. The scene in the film where he disrupts a presentation to challenge a speaker is based on his reputation for not tolerating "Wall Street spin."
How much did the real Mark Baum make from the 2008 crash?
While exact personal figures are private, the FrontPoint fund Eisman managed reportedly made roughly $1 billion in profit. As the lead manager, Eisman would have received a significant percentage of the "carry" (performance fee), which likely totaled in the tens of millions for that single year, not including his existing equity in the firm.
Is Steve Eisman still shorting the market in 2026?
Eisman is not a perma-bear (someone who is always betting on a crash). In 2026, his role at Neuberger Berman involves both long and short positions. He has stated in interviews that "the big short" was a once-in-a-lifetime trade and that he now spends more time looking for high-quality companies to buy than looking for systems to collapse.
What happened to the other people in Mark Baum’s office?
The team depicted in the film was based on real-life analysts like Danny Moses, Vincent Daniel, and Porter Collins. Most of these individuals went on to start their own successful hedge funds (such as Seawolf Capital) or continued to hold prominent roles in the financial sector, maintaining their reputation as sharp, data-driven contrarians.
What is Steve Eisman's advice for retail investors?
Eisman generally advises retail investors to avoid the "get rich quick" mentality. He emphasizes the importance of understanding what you own and being wary of high-leverage investments. He has often noted that if you cannot explain a financial product in two sentences, you probably shouldn't be invested in it.
Practical Recommendations for Following the "Big Short" Strategy
If you are looking to apply the principles of Mark Baum/Steve Eisman to your own financial journey in 2026, consider the following actions:
- Analyze the Prospectus: Do not rely on "buy" ratings from analysts. Read the underlying financial filings (10-K and 10-Q) to understand a company's debt structure and cash flow.
- Look for Incentives: In any investment, identify who gets paid and how. Eisman succeeded in 2008 because he realized the rating agencies were paid by the very banks they were supposed to be policing.
- Diversify Against Systemic Risk: Ensure that your portfolio is not overly concentrated in a single sector, especially one that is highly sensitive to interest rate changes or regulatory shifts.
- Monitor Institutional Movers: Follow the 13F filings of managers like Eisman at Neuberger Berman to see how they are positioning their portfolios in response to current economic trends.