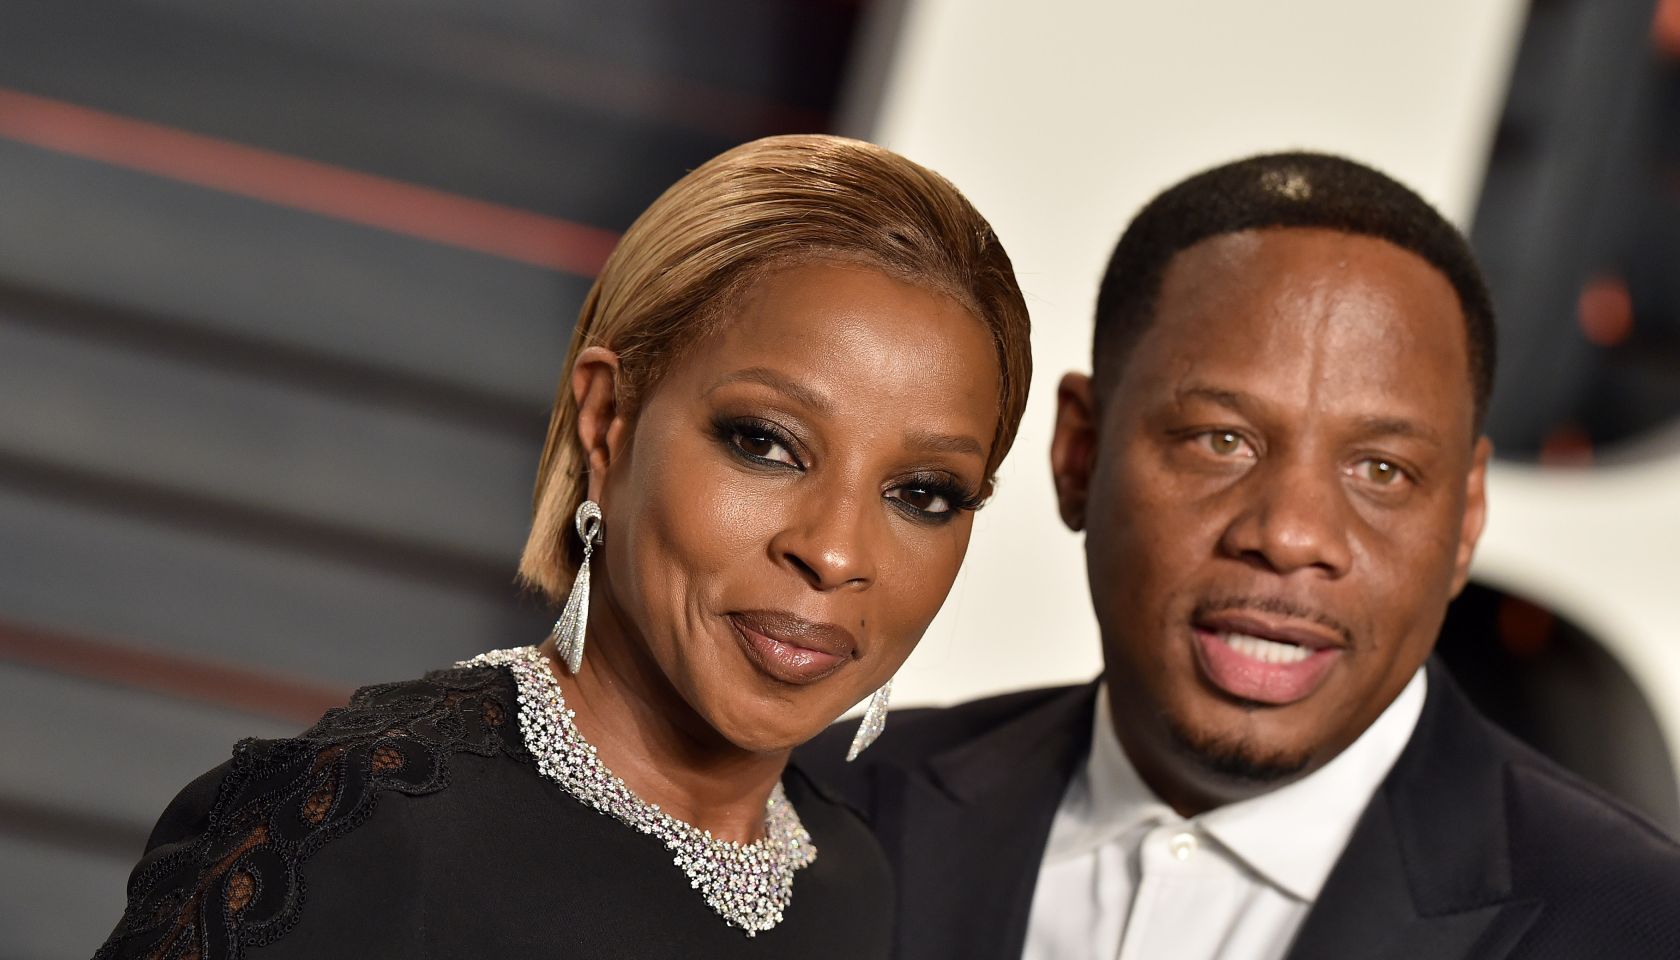
In 2018, Mary J. Blige and her ex-husband, Martin "Kendu" Isaacs, finalized a contentious divorce that centered on significant spousal support claims and complex financial obligations. While the final settlement remains confidential, court records revealed that Blige was initially ordered to pay Isaacs $30,000 per month in temporary spousal support, a sharp reduction from his original request of nearly $130,000.
The legal battle between the "Queen of Hip-Hop Soul" and her former manager serves as a landmark case in celebrity family law, particularly regarding the intersection of marital partnership and professional management. As of 2026, the case remains a frequently cited example of how prenuptial agreements and joint financial liabilities influence the dissolution of high-net-worth marriages.
The Background of the Blige-Isaacs Partnership
Mary J. Blige and Martin Isaacs married in 2003. For much of their 12-year marriage, Isaacs served as Blige’s manager, a dual role that complicated both their personal and professional finances. When Blige filed for divorce in July 2016, citing irreconcilable differences, the separation immediately triggered a dispute over how to untangle their intertwined financial lives.
The professional aspect of their relationship was a primary point of contention. As a manager, Isaacs was entitled to a percentage of Blige’s earnings. However, Blige’s legal team argued that his mismanagement contributed to substantial debt, which later became a central theme in the spousal support negotiations. This "manager-spouse" dynamic is often a double-edged sword in divorce proceedings, as the higher-earning spouse may claim that the dependent spouse’s professional failures should mitigate alimony obligations.
The Financial Dispute: Spousal Support Requests vs. Reality
One of the most publicized aspects of the divorce was the gap between what Isaacs requested in spousal support and what the court eventually granted. Isaacs’ initial filing sought $129,319 per month in temporary alimony. His legal team argued that this amount was necessary to maintain the "lavish lifestyle" to which he had become accustomed during the marriage.
Breakdown of the $129,000 Request
To justify the six-figure monthly request, Isaacs provided a detailed breakdown of his perceived needs. These expenses included:
- Rent and Housing: High-end property costs in Los Angeles and New Jersey.
- Personal Staff: Expenses for a private chef, personal trainer, and security.
- Travel: Costs associated with first-class travel and luxury vacations.
- Family Support: Financial assistance for his children from previous relationships.
- Charitable Contributions: Approximately $1,000 per month for donations.
Blige’s legal team vehemently opposed these figures, labeling them "outrageous" and "exorbitant." They argued that Isaacs was using the alimony request as a way to remain financially tethered to Blige’s success without contributing to his own self-sufficiency.
The Temporary Spousal Support Ruling
In June 2017, a Los Angeles Superior Court judge issued a ruling on pendente lite support—temporary support paid while the divorce is still pending. The judge ordered Blige to pay Isaacs $30,000 per month. While this was a significant sum, it represented less than a quarter of Isaacs’ original demand.
The court also ordered Blige to pay $235,000 in retroactive spousal support and $100,000 in legal fees. The judge noted that while Isaacs was entitled to support, the requested $129,000 was not "reasonable" or "necessary" to maintain a standard of living that aligned with the couple’s actual net income, which was hampered by significant debt.
The Impact of the Prenuptial Agreement
A central hurdle in the divorce was the validity of the couple’s prenuptial agreement. Isaacs challenged the document, claiming he signed it without proper legal representation and that it was unconscionable. In California, prenuptial agreements are generally enforceable unless a party can prove they were coerced or did not have a full understanding of the financial disclosures.
The dispute over the prenuptial agreement was one of the primary reasons the case dragged on for nearly two years. If the agreement had been thrown out, Isaacs might have been eligible for a larger share of Blige’s assets under community property laws. However, the eventual out-of-court settlement suggests that the prenuptial agreement likely provided a framework that limited Isaacs’ long-term claims, even if temporary support was granted.
Financial Obligations and Shared Liabilities
A significant factor that influenced the judge’s decision to lower the spousal support amount was the couple’s financial health at the time of the split. Despite Blige’s status as a global superstar, her legal filings revealed a grim financial picture.
Tax Liens and Joint Debts
Blige’s legal team presented evidence that the couple owed millions of dollars in back taxes to the Internal Revenue Service (IRS). In 2017, it was reported that Blige was dealing with approximately $6.5 million in unpaid taxes spanning several years. Under California law, when a couple has significant joint liabilities, the court must consider these debts when determining the "available income" for spousal support.
The court recognized that Blige was the sole breadwinner and was responsible for servicing these debts. Awarding Isaacs a massive monthly alimony check would have potentially hindered Blige’s ability to satisfy her obligations to the government, which took precedence over maintaining Isaacs’ luxury lifestyle.
The $10 Million Debt Claim
During the proceedings, Blige famously stated in court documents that she was "overwhelmed" by the debt accrued during the marriage, which she claimed exceeded $10 million. She attributed much of this to Isaacs’ spending habits and mismanagement of her career.
This claim was a strategic move by her legal counsel to demonstrate that the "marital standard of living" Isaacs was trying to maintain was built on borrowed money and unpaid taxes, rather than sustainable income. This is a critical nuance in family law: the "marital standard" is not just about what you spent, but what you could afford to spend.
Comparative Analysis of High-Stakes Celebrity Alimony
The Blige-Isaacs case is often compared to other celebrity divorces where the female breadwinner was ordered to pay significant spousal support. This table highlights how her obligations compared to other notable cases.
| Celebrity | Ex-Spouse | Initial Support Request | Final/Temporary Order | Key Factor |
|---|---|---|---|---|
| Mary J. Blige | Kendu Isaacs | $129,319 / month | $30,000 / month | Heavy debt and tax liens |
| Kelly Clarkson | Brandon Blackstock | $436,000 / month | $115,000 / month | Primary earner vs. manager |
| Halle Berry | Gabriel Aubry | $16,000 / month | $8,000 / month | Child support/alimony mix |
| Dr. Dre | Nicole Young | $2,000,000 / month | $293,306 / month | Massive net worth disparity |
Legal and Professional Ramifications
The divorce had a profound impact on Mary J. Blige’s career and public image. She used her personal turmoil as inspiration for her 2017 album, Strength of a Woman, which detailed the emotional and financial betrayal she felt.
From a legal perspective, the case reinforced several key principles:
- The Limitation of "Lifestyle" Claims: Courts are increasingly skeptical of "lifestyle" arguments when they are not supported by the couple’s actual net cash flow after debts are paid.
- Managerial Misconduct: When a spouse acts as a business manager, their professional performance can be used as evidence in alimony disputes, especially if their actions led to financial loss for the earning spouse.
- Temporary vs. Permanent Support: The difference between temporary (pendente lite) and permanent support is vast. Temporary support is designed to maintain the status quo, while permanent support is based on the California Family Code Section 4320 factors, including the duration of the marriage and the ability of the supported spouse to work.
Lessons for High-Net-Worth Individuals
The Blige-Isaacs divorce provides a cautionary tale for high-earning individuals, particularly those who work closely with their spouses. In the years since the settlement, legal experts have pointed to this case as a reason to maintain strict boundaries between marital and professional assets.
The Importance of Independent Legal Counsel
One of Isaacs’ main arguments was the lack of independent counsel when signing the prenuptial agreement. To ensure a prenuptial agreement is ironclad, both parties must have their own separate attorneys. If one party uses the other's lawyer or "waives" counsel, the agreement becomes much more vulnerable to being overturned in court.
Mitigating the "Manager-Spouse" Risk
When a spouse manages the other's career, it is advisable to have a formal employment contract that exists independently of the marriage. This contract should specify severance terms and management fees, which can help simplify the financial separation if the marriage ends.
Managing Joint Tax Liability
As seen in Blige’s case, joint tax returns make both spouses "jointly and severally liable" for the debt. High-earners may consider filing "married filing separately" if they suspect their spouse is mismanaging funds, although this often results in a higher tax rate.
Frequently Asked Questions
Did Mary J. Blige have a prenuptial agreement?
Yes, Mary J. Blige had a prenuptial agreement, which she signed prior to her 2003 marriage. However, Kendu Isaacs challenged its validity during the divorce proceedings, leading to a protracted legal battle. The eventual settlement was reached out of court, suggesting the prenup likely played a role in the final terms.
How much did Kendu Isaacs receive in the final settlement?
The exact terms of the final settlement, reached in March 2018, are confidential. While it is known that Blige paid $30,000 per month in temporary support during the proceedings, the final "lump sum" or ongoing payment amounts were never made public. Settlement agreements often include non-disclosure clauses to protect the privacy of both parties.
Why was the spousal support amount reduced from $129,000 to $30,000?
The judge reduced the amount because Isaacs' request was deemed unreasonable given the couple's actual financial situation. The court took into account the $10 million in debt and $6.5 million in tax liens, concluding that the income available for support was much lower than Isaacs claimed.
Can a spouse's mismanagement of money affect alimony?
In many jurisdictions, including California, "economical misconduct" or "marital waste" can be considered by the court. If one spouse significantly mismanaged or squandered marital assets, the court may adjust the distribution of property or the amount of spousal support to compensate the other spouse.
What is the difference between temporary and permanent spousal support?
Temporary support (pendente lite) is intended to maintain the standard of living from the time of separation until the divorce is final. Permanent support is determined at the end of the divorce and is based on a wider range of factors, including the age, health, and earning capacity of both parties, as well as the length of the marriage.
Final Recommendation for Those Facing Similar Financial Disputes
If you are navigating a divorce involving high-net-worth assets or manager-spouse complications, it is essential to conduct a forensic accounting of all marital and professional finances. As demonstrated by the Mary J. Blige case, the presence of debt and tax liabilities can significantly alter the court's perception of "lifestyle" requirements.
Prioritize the validation of your prenuptial agreement early in the process and ensure that all professional contracts between spouses are reviewed by independent counsel. For those in the public eye, seeking an out-of-court settlement—as Blige and Isaacs eventually did—can prevent further public disclosure of sensitive financial data and personal liabilities.