Evaluating the 2025 status requires looking back at a pivotal twelve-month period defined by shifting macroeconomic markers, rapid technological deployment, evolving regulatory frameworks, and sector-specific milestones. Rather than representing a single isolated event, the status of 2025 encompasses multiple distinct operational phases across industries, markets, and institutional domains. This overview examines the foundational metrics, verified achievements, structural challenges, and systemic outcomes that shaped the year, offering a clear baseline for current and future decision-making.
Defining the Scope and Historical Context of 2025
The year 2025 functioned as a critical transitional bridge between recovery-focused post-pandemic planning and long-term structural transformation. To understand the landscape, analysts must evaluate how prior commitments—such as international climate accords, corporate digital transition roadmaps, and monetary policy adjustments—reached crucial operational deadlines during this timeframe.
During this period, organizations across both public and private sectors moved away from experimental frameworks toward standardized implementation. This shift was particularly evident in enterprise technology integration, energy infrastructure modernization, and supply chain restructuring. Rather than dealing purely with crisis response, stakeholders confronted the realities of sustained high interest rates, shifting geopolitical trade routes, and maturing consumer expectations regarding digital privacy and automation.
Key Macroeconomic Indicators
Economic performance throughout the year varied significantly by region, yet several global trends remained consistent:
- Inflation Stabilization: Central banks in major economies managed to bring consumer price index metrics closer to target corridors, though sticky service-sector inflation persisted.
- Labor Market Adaptation: Employment figures showed stabilization, accompanied by a growing emphasis on upskilling programs to counter the displacement effects of automated workflows.
- Capital Access: Venture capital and commercial lending environments remained selective, favoring enterprises demonstrating immediate operational profitability over speculative expansion.
Sector-by-Sector Status Analysis
A comprehensive evaluation of the 2025 status demands breaking down performance metrics and operational milestones across core industries. Each sector faced distinct pressures and achieved different levels of progress relative to pre-established benchmarks.
Technology and Digital Infrastructure
The technology landscape in 2025 was defined by the transition from generative artificial intelligence hype to pragmatic enterprise deployment. Organizations prioritized return on investment, data governance, and cybersecurity resilience.
- Artificial Intelligence Governance: Regulatory bodies worldwide began enforcing stricter compliance standards regarding data sourcing, algorithmic bias, and transparency, leading to the institutionalization of AI ethics frameworks.
- Cloud and Edge Computing: Decentralized data processing saw accelerated adoption, driven by the demand for low-latency applications in manufacturing, logistics, and autonomous systems.
- Semiconductor Supply Chains: Manufacturing capacity diversified geographically, mitigating single-region vulnerabilities that had disrupted global hardware supplies in preceding years.
Energy and Sustainability
Environmental, social, and governance (ESG) targets faced a reality check in 2025 as energy security concerns intersected with decarbonization goals.
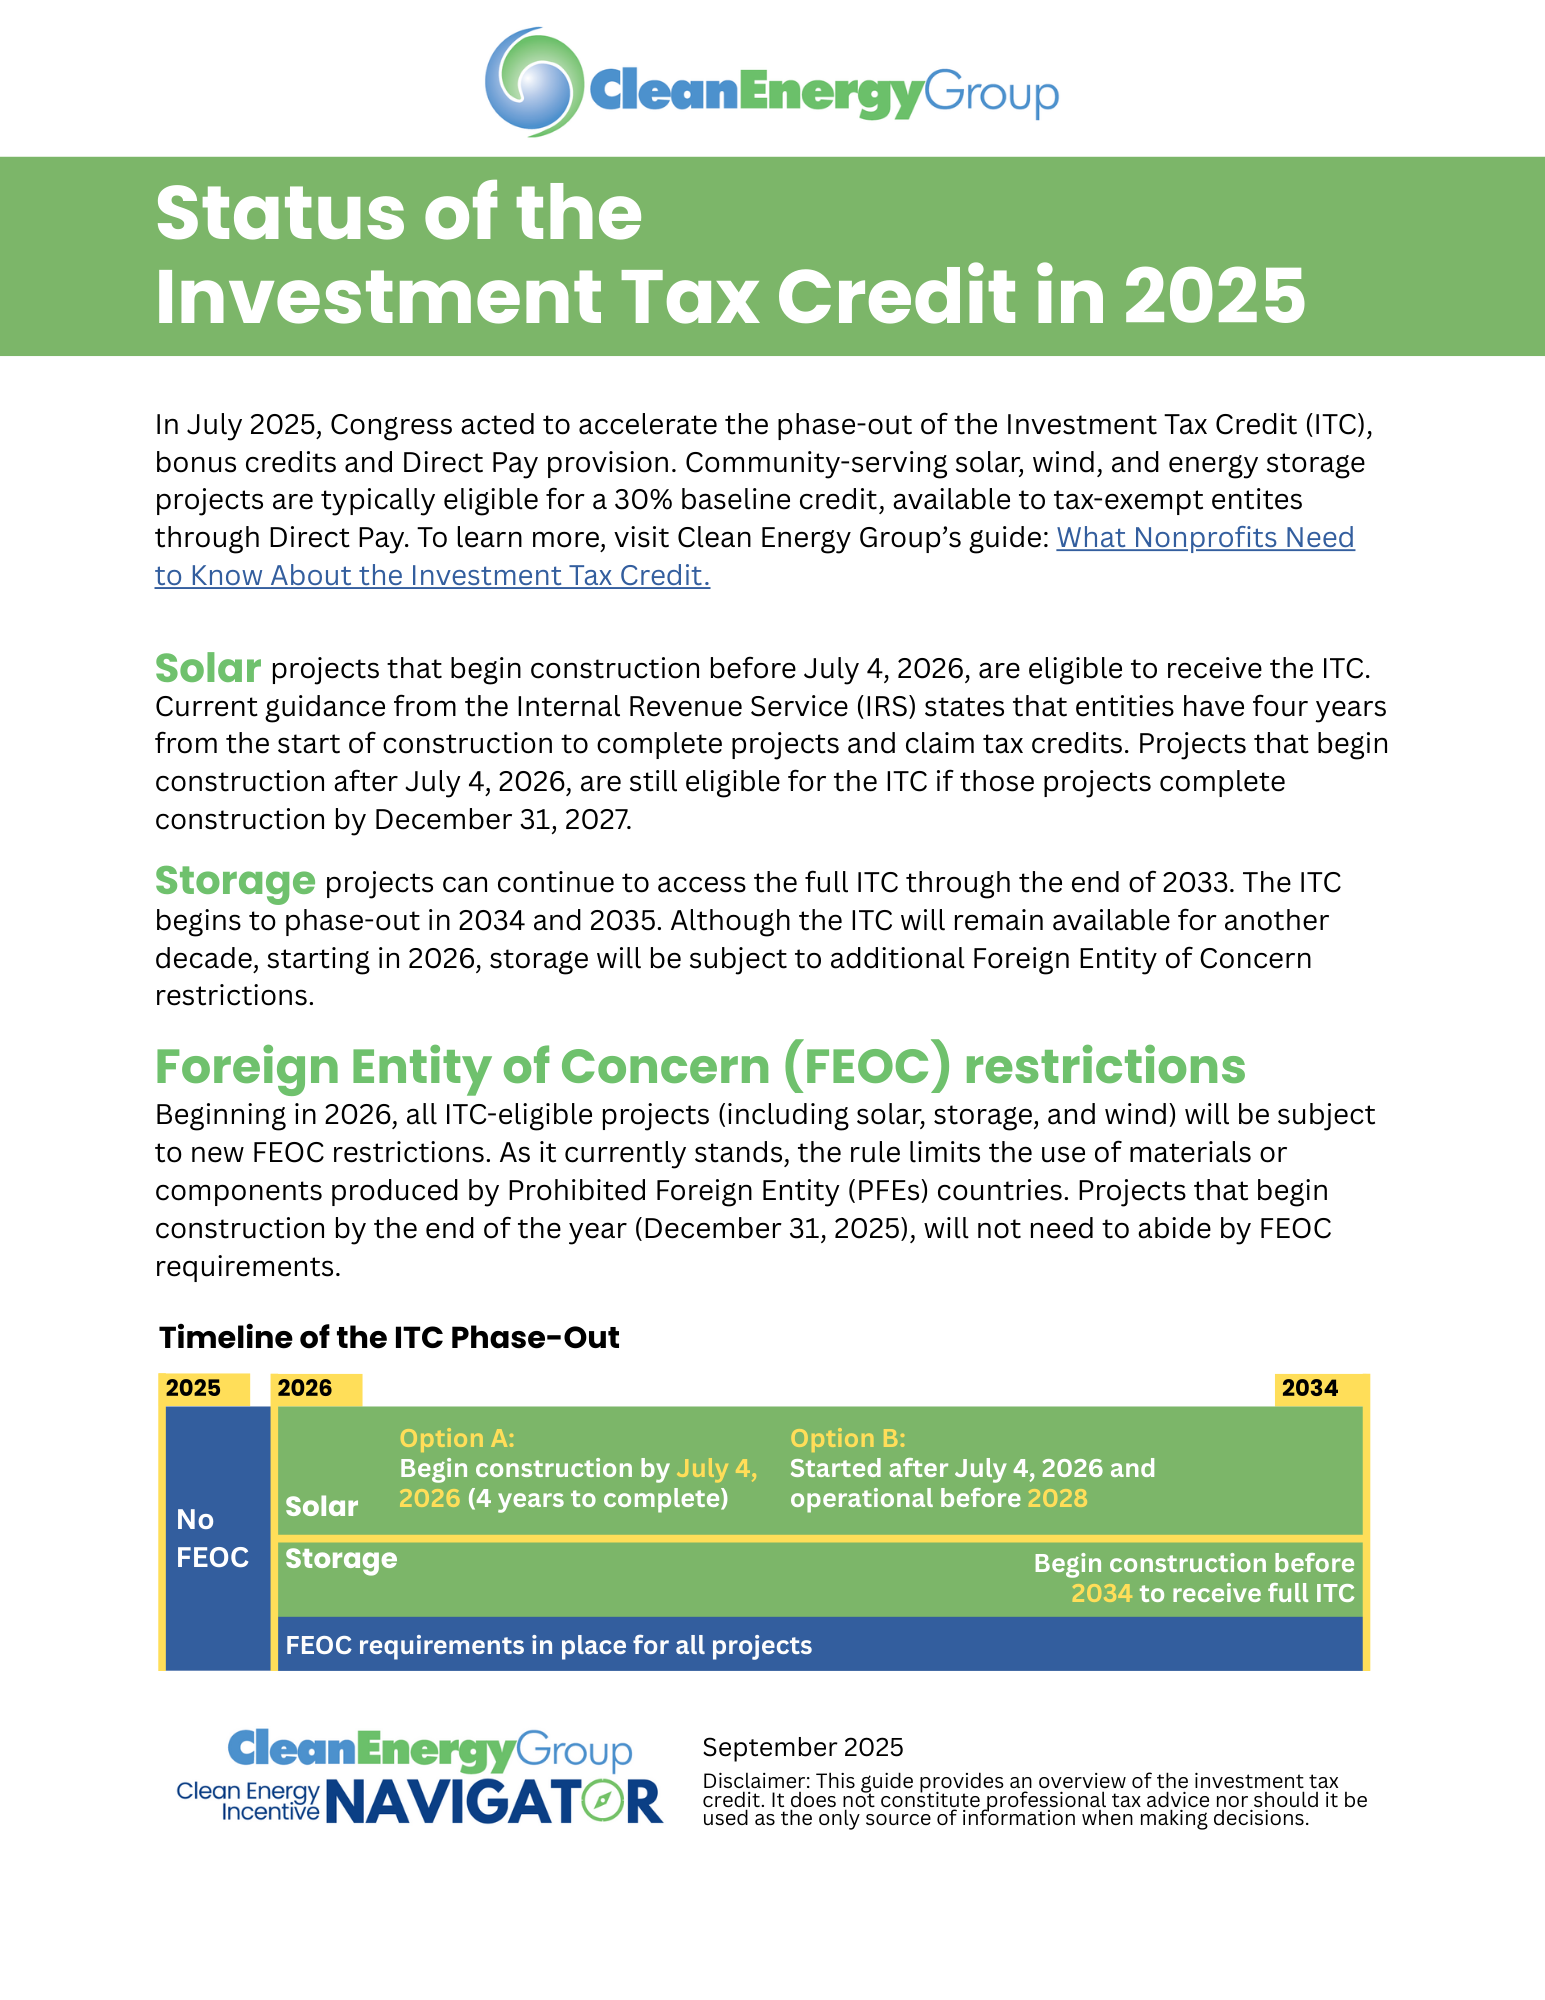
- Renewable Integration: Solar and wind deployment continued to scale rapidly, supported by government subsidies and falling component costs. However, grid congestion and storage limitations remained primary bottlenecks.
- Fossil Fuel Transition: Traditional energy producers balanced ongoing hydrocarbon demand with targeted investments in carbon capture, utilization, and storage (CCUS) technologies.
- Policy Compliance: Corporations encountered mandatory carbon reporting requirements in several major jurisdictions, shifting sustainability metrics from voluntary marketing initiatives to auditable financial disclosures.
Comparative Sector Performance Matrix
The following table outlines the status, primary drivers, and primary challenges across key industries during the period.
| Sector | Operational Status | Primary Growth Drivers | Core Operational Challenge |
|---|---|---|---|
| Technology | Maturing Implementation | Productivity gains, enterprise cloud migration | Cybersecurity threats, talent scarcity |
| Energy | Transitional Divergence | Government incentives, capacity expansion | Grid storage, transmission bottlenecks |
| Healthcare | Digitized Delivery | Telehealth adoption, personalized medicine | Regulatory compliance, staffing shortages |
| Supply Chain | Regionalized Resilience | Nearshoring, predictive analytics | Geopolitical friction, transport costs |
Regulatory and Legal Developments
Legal frameworks underwent substantial modernization to keep pace with rapid commercial and technological evolution. Compliance officers and legal counsel navigated complex new mandates spanning digital assets, cross-border data transfers, and consumer protection.
Data privacy laws saw harmonization attempts in multiple regions, though compliance fragmentation remained a challenge for multinational enterprises. Simultaneously, antitrust authorities maintained rigorous scrutiny over corporate mergers and acquisitions, particularly within the technology and pharmaceutical sectors, aiming to preserve competitive market structures.
Frequently Asked Questions
What were the defining characteristics of the 2025 status across global markets?
The period was characterized by a shift from rapid experimentation to disciplined execution. Organizations focused on operational efficiency, regulatory compliance, and sustainable growth amidst fluctuating macroeconomic conditions.
How did regulatory frameworks impact technological adoption during this time?
New regulations governing data privacy, artificial intelligence deployment, and cybersecurity forced organizations to embed compliance into the early stages of product development rather than treating it as an afterthought.
What role did macroeconomic factors play in corporate strategy?
Stabilizing inflation and disciplined capital markets forced companies to prioritize profitability, cash flow visibility, and cost optimization over aggressive, debt-financed expansion.
Were there significant supply chain adjustments completed during this period?
Yes, many enterprises accelerated nearshoring and friendshoring strategies to build redundancy against geopolitical disruptions and logistical vulnerabilities.
How are historical metrics from this period verified today?
Analysts rely on official reports from central banks, international regulatory bodies, audited corporate earnings statements, and peer-reviewed industry research to establish accurate baseline data.
Strategic Outlook and Next Actions
Evaluating the status requires translating historical lessons into actionable guidance for ongoing planning. Stakeholders should review their operational roadmaps through the lens of resilience, adaptability, and compliance. Organizations must continuously monitor regulatory updates, invest in workforce adaptability, and maintain rigorous risk management protocols to navigate ongoing market shifts effectively.