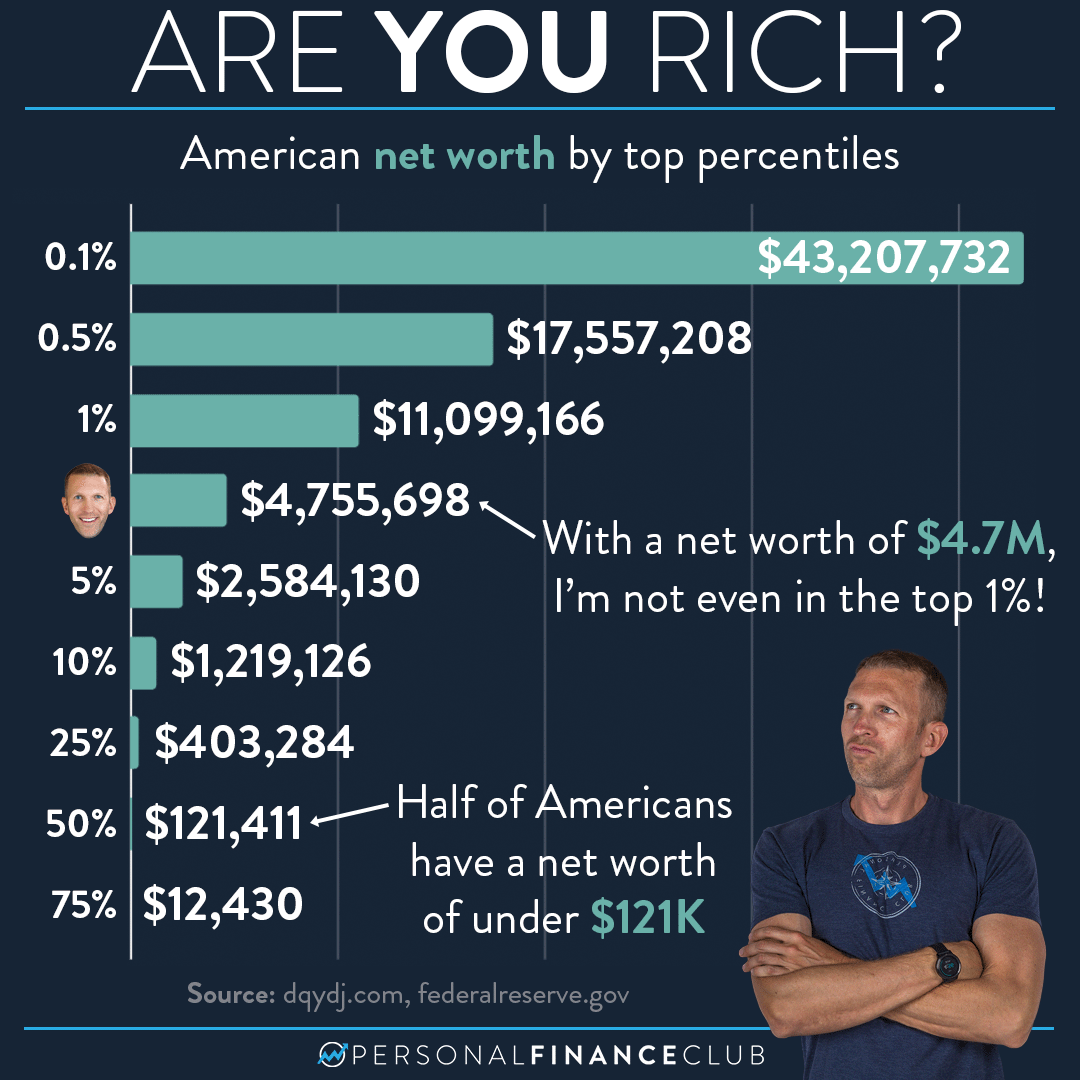
A net worth of $1.27 million places an individual in approximately the top 5% to 10% of households in the United States, depending on age, household size, and whether the metric measures liquid assets or total net worth including real estate. This threshold signifies an upper-middle-class or mass-affluent status, reflecting substantial financial accumulation, disciplined saving, and long-term asset growth.
Evaluating financial standing through the lens of net worth percentiles requires looking past raw totals to understand how wealth is distributed across populations. Achieving a $1.27 million net worth is a significant financial milestone, but the percentile rank shifts dramatically depending on the demographic cohort, geographic location, and macroeconomic conditions. This comprehensive guide explores what a $1.27 million net worth means in terms of percentiles, how wealth is calculated, and what factors influence these rankings.
Defining Net Worth and Its Core Components
Net worth is a fundamental financial metric representing the difference between total assets and total liabilities. To determine where a $1.27 million net worth ranks, it is essential to understand what constitutes these opposing sides of the financial ledger. Assets include liquid holdings such as cash, savings accounts, checking accounts, and certificates of deposit, alongside investment vehicles like stocks, bonds, mutual funds, and exchange-traded funds (ETFs). Retirement accounts—including traditional and Roth Individual Retirement Accounts (IRAs), 401(k) plans, 403(b) plans, and pensions—also contribute heavily to this figure. Furthermore, tangible property such as primary residences, investment real estate, vehicles, and valuable personal property count toward total assets, provided they can be valued accurately at current market prices.
Liabilities, conversely, diminish net worth. These obligations include mortgage debt on primary and secondary residences, student loans, consumer debt such as credit card balances, personal loans, and auto loans. A person with $1.5 million in total assets and $230,000 in combined mortgage and consumer debt possesses a net worth of exactly $1.27 million.
Distinguishing between liquid net worth and total net worth is vital when evaluating financial security. Total net worth includes illiquid assets like real estate equity, which cannot be accessed immediately without selling the property or securing a home equity loan. Liquid net worth strips away real estate, personal possessions, and locked retirement vehicles, focusing strictly on cash and easily marketable securities. While a $1.27 million total net worth offers substantial long-term security, a portfolio heavily tied up in a primary residence differs fundamentally from one composed of liquid brokerage accounts.
Where $1.27 Million Ranks in the United States
Wealth distribution data published by institutions like the Federal Reserve through its Survey of Consumer Finances (SCF) provides a clear picture of how household wealth clusters across the nation. According to recent Federal Reserve data and wealth tracking studies, a net worth of $1.27 million generally positions a household around the 85th to 90th percentile nationally. This means that an individual or household with this net worth has accumulated more wealth than approximately 85% to 90% of the American population.
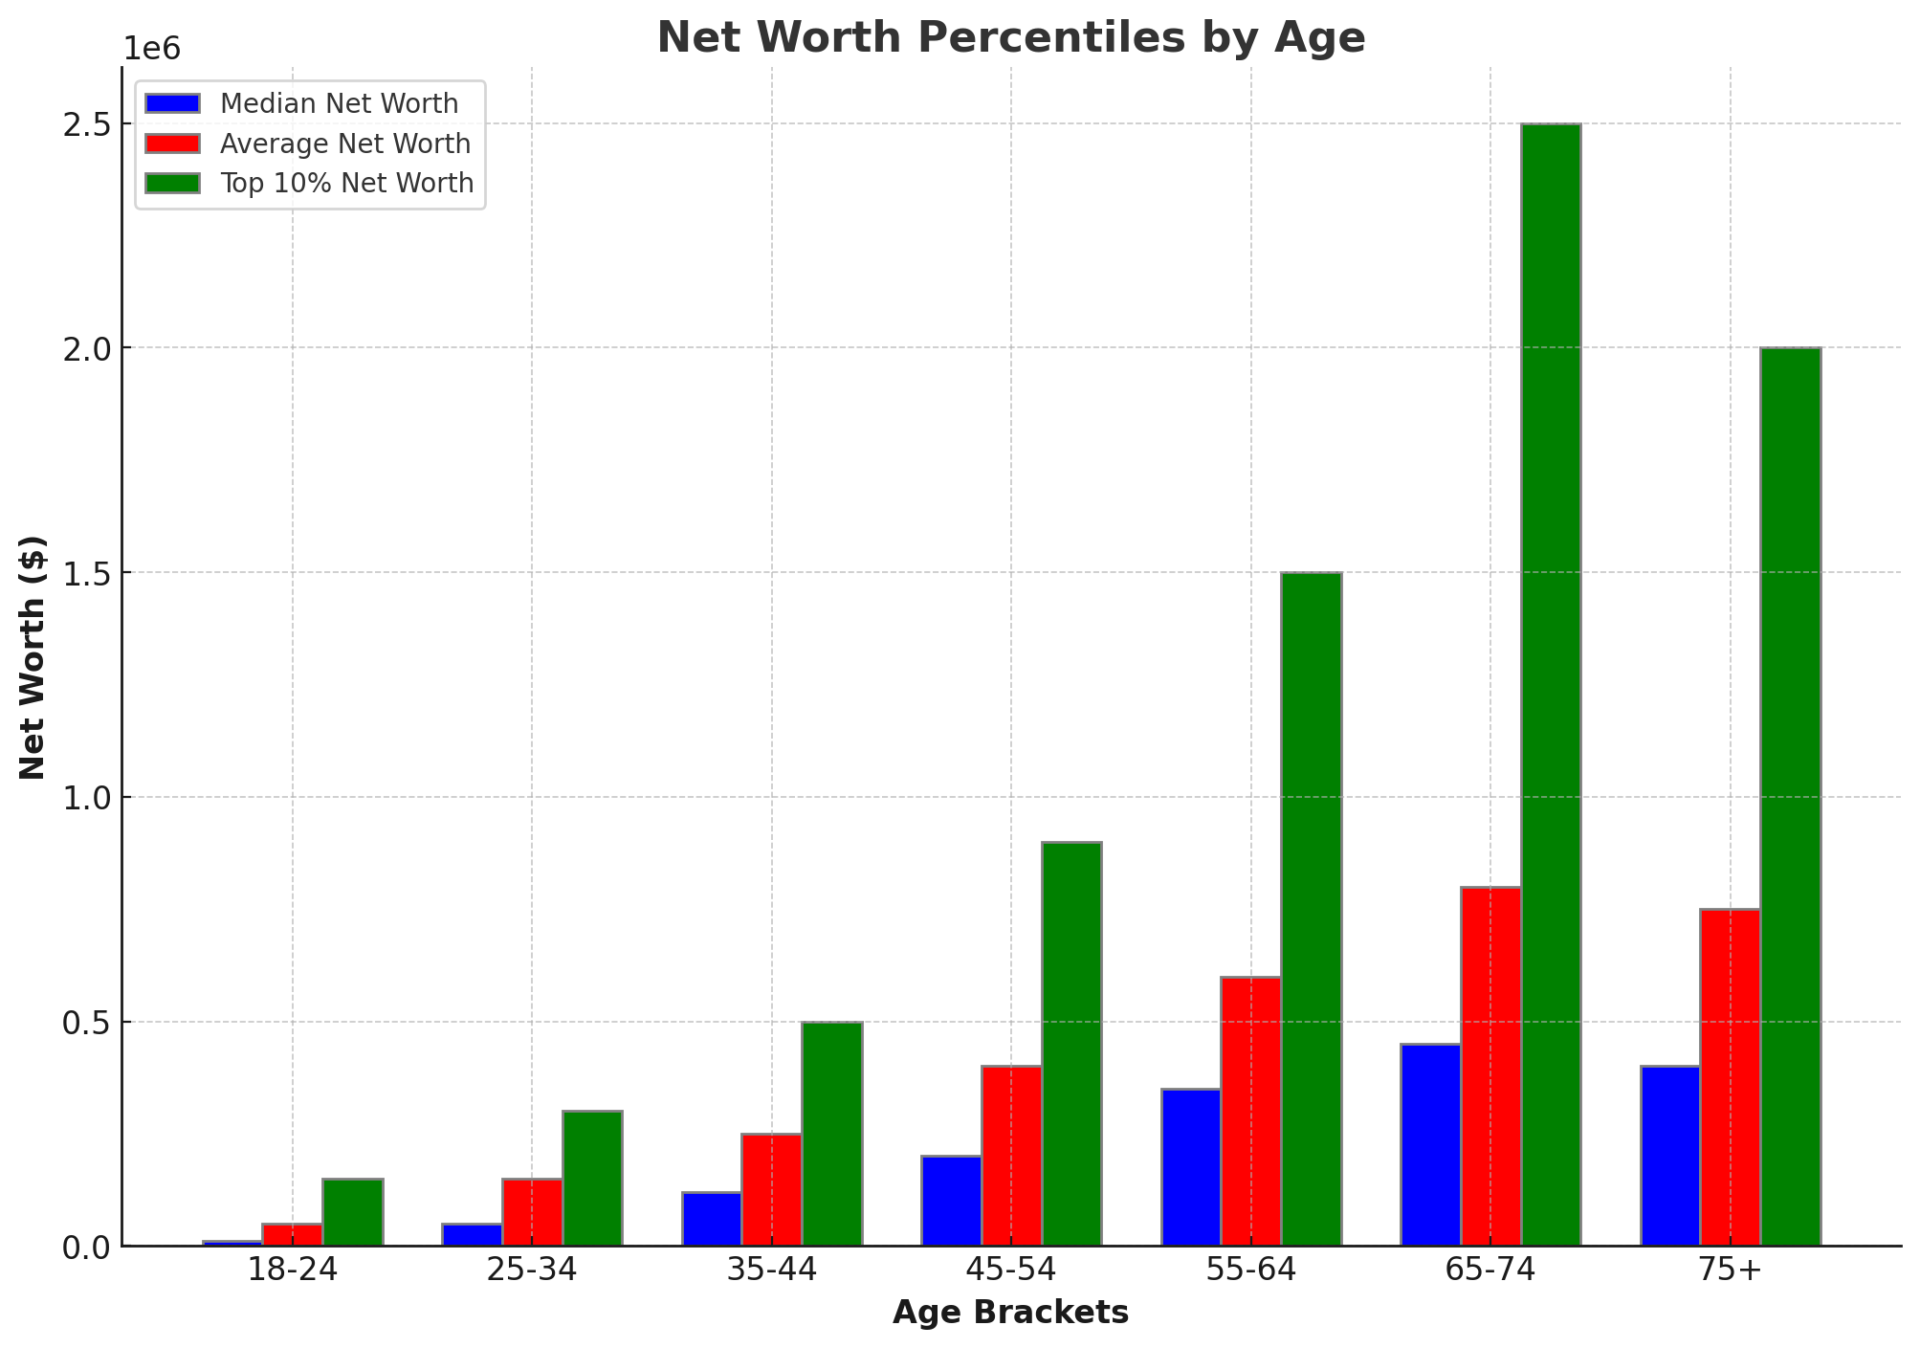
However, national percentiles mask significant variations when evaluated across different age brackets. Wealth accumulation is closely correlated with time; younger individuals have had less time to compound investments, pay down mortgages, and advance in their careers. Consequently, a $1.27 million net worth represents a vastly different percentile depending on the age of the asset holder.
| Age Group | Estimated Net Worth for Top 10% | Estimated Net Worth for Top 5% | Where $1.27M Ranks (Approximate) |
|---|---|---|---|
| Under 35 | ~$240,000 | ~$500,000+ | Top 1% to 2% |
| 35–44 | ~$550,000 | ~$1,100,000 | Top 5% to 7% |
| 45–54 | ~$1,200,000 | ~$2,300,000 | Top 10% to 12% |
| 55–64 | ~$2,000,000 | ~$3,800,000 | Top 15% to 18% |
| 65–74 | ~$2,600,000 | ~$4,700,000 | Top 20% to 22% |
| 75+ | ~$2,400,000 | ~$4,400,000 | Top 20% to 25% |
As illustrated in the table, a $1.27 million net worth is exceptionally rare for individuals under the age of 45, frequently placing them in the top 5% or higher of their generational cohort. For individuals approaching or in retirement (ages 55 and older), $1.27 million is a respectable and comfortable sum, though it falls closer to the 80th percentile due to the cumulative nature of lifetime savings among older demographics.
Key Factors Influencing Wealth Percentiles
Understanding why a $1.27 million net worth yields different percentile rankings requires analyzing the structural factors that drive wealth accumulation in modern economies.
Age and Career Stage
Time in the market and career progression are primary drivers of net worth. High earners in their twenties may possess high income but low net worth due to student loans and a lack of accumulated assets. Conversely, individuals in their fifties and sixties benefit from decades of compound interest, home equity appreciation, and peak earning years. A $1.27 million net worth achieved at age 35 reflects an aggressive savings rate, high income, or early investment success, whereas the same net worth at age 65 represents a standard, solid retirement nest egg achieved through decades of steady saving.
Geographic Location and Cost of Living
Geography heavily dictates asset values and wealth distribution. In high-cost-of-living metropolitan areas like New York City, San Francisco, or Washington, D.C., a $1.27 million net worth—driven largely by high real estate values—is relatively common and may only place a household in the 75th to 80th percentile locally. In contrast, in rural or mid-sized Midwestern cities, that same net worth places a household well into the top 5% locally, affording significantly more purchasing power and lifestyle flexibility.
Household Structure and Dual Incomes
Whether a net worth belongs to a single individual or a dual-income household changes the comparative baseline. Dual-income-no-kids (DINK) households often reach milestones like $1.27 million faster due to combined earnings and reduced household expenses. Single-earner households face a steeper tax burden and higher per-capita living costs, making the achievement of a seven-figure net worth an even more pronounced milestone.
Financial Implications of a $1.27 Million Net Worth
Reaching a net worth of $1.27 million alters financial planning strategies, moving the focus away from basic survival and debt elimination toward asset preservation, tax efficiency, and sustainable drawdown strategies.
The 4% Rule and Sustainable Withdrawal
For individuals considering retirement or financial independence, a $1.27 million portfolio can be evaluated using the foundational financial concept known as the 4% rule. Derived from historical market returns, this rule suggests that a retiree can safely withdraw 4% of their initial portfolio value in the first year of retirement, adjusting subsequent withdrawals for inflation, without exhausting the principal over a 30-year timeframe.
Applying a 4% withdrawal rate to a $1.27 million portfolio yields an initial annual pre-tax income of approximately $50,800. Combined with potential Social Security benefits, pension income, or part-time work, this provides a stable middle-class retirement in many parts of the country. However, for individuals living in high-cost areas, $50,800 a year requires careful budgeting and disciplined expense management.
Asset Allocation and Risk Management
At the $1.27 million threshold, protecting capital becomes as important as growing it. A balanced asset allocation typically combines equities for growth, fixed-income instruments like bonds or Treasury securities for stability, and cash equivalents for immediate liquidity. Overexposure to a single asset class—such as a single company stock or an undiversified real estate portfolio—introduces unnecessary volatility that can threaten long-term financial security.
Common Misconceptions Regarding Millionaire Status
Pop culture and historical definitions often frame a "millionaire" as someone living an extravagant lifestyle of luxury cars and sprawling estates. In the modern economic landscape, a $1.27 million net worth is representative of the mass-affluent middle class rather than ultra-high-net-worth status.
Inflation and escalating asset prices mean that $1 million today possesses significantly less purchasing power than it did decades ago. Furthermore, because net worth includes illiquid assets like primary residences and retirement accounts that carry early-withdrawal penalties, an individual with a $1.27 million net worth may not have immediate access to lavish amounts of spending money. Much of this wealth is locked away to fund future healthcare, housing, and retirement expenses. Recognizing this distinction helps contextualize where a seven-figure portfolio stands in relation to true financial independence.
Frequently Asked Questions
Is a $1.27 million net worth considered rich in the United States?
A $1.27 million net worth is considered upper-middle-class or mass-affluent rather than wealthy or rich. While it places a household in the top 10% to 15% nationally, much of this wealth is typically tied up in retirement accounts and home equity, meaning it does not translate into endless discretionary spending money.
How much passive income can a $1.27 million net worth generate?
Using the traditional 4% safe withdrawal rule, a $1.27 million portfolio can generate approximately $50,800 per year in pre-tax income. Actual income will vary based on investment yields, dividend payouts, real estate rental income, and overall portfolio asset allocation.
Does primary residence equity count toward net worth?
Yes, primary residence equity—calculated as the current market value of the home minus the remaining mortgage balance—is a standard component of total net worth. However, financial planners often evaluate liquid net worth separately when assessing retirement readiness, as selling a home to access equity incurs transaction costs and requires alternative housing.
Why do net worth percentiles vary so much by age?
Wealth accumulation is a cumulative process that relies on compounding interest, career advancement, and asset appreciation over decades. Younger individuals have had less time to save and invest, making a $1.27 million net worth rare for someone under 35, whereas it is much more common for individuals nearing retirement age.
How can I accurately calculate my own net worth?
To calculate net worth, compile a comprehensive list of all assets—including cash, checking and savings balances, investment portfolios, retirement accounts, vehicles, and real estate valued at current market prices. Subtract all outstanding liabilities, including mortgages, student loans, auto loans, and credit card debt. The remaining figure is your total net worth.
Next Steps for Managing and Growing Seven-Figure Wealth
Achieving a $1.27 million net worth is a significant milestone that requires deliberate planning to maintain and expand. To protect and optimize this capital, review asset allocation regularly to ensure investments align with personal risk tolerance and time horizons. Implement tax-advantaged strategies, such as utilizing tax-loss harvesting in taxable brokerage accounts and maximizing contributions to employer-sponsored plans. Finally, consult with a certified financial planner (CFP) or fiduciary tax professional to establish a robust estate plan, draft a sustainable withdrawal strategy, and safeguard accumulated assets against unforeseen market downturns or liability risks.