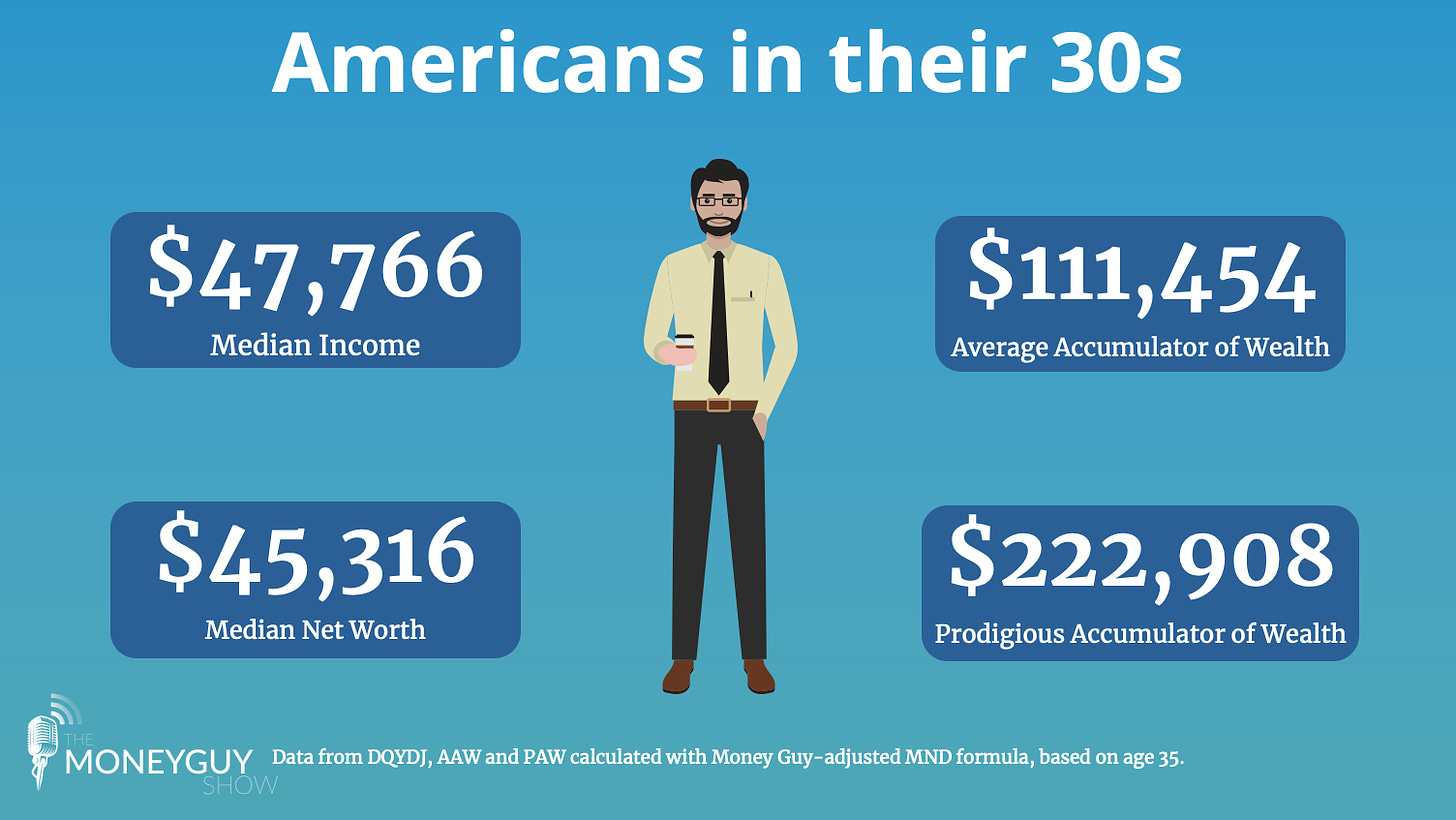
At age 37, a strong financial baseline typically involves a net worth equal to roughly two times your annual household income, though individual targets vary significantly based on career trajectory, geography, and starting debt loads. Reaching this milestone requires balancing aggressive retirement savings, real estate equity, and liquid investments while managing liabilities like mortgages and student loans.
As you navigate your late thirties, financial planning shifts from early career accumulation to a more strategic, multi-decade wealth-building phase. At 37 years old, you are roughly midway through your professional working life. Questions surrounding your net worth often bring up anxieties or comparisons, but understanding personal benchmarks requires looking beyond a single arbitrary number. Financial health is an aggregate of your assets, liabilities, income stability, and long-term goals. Achieving clarity on what your net worth should look like at this specific stage of life involves examining standard multipliers, asset allocation strategies, and actionable steps to optimize your financial trajectory for the decades ahead.
Understanding Net Worth in Your Late Thirties
Net worth is fundamentally a simple mathematical calculation: your total assets minus your total liabilities. Assets include cash, retirement accounts, taxable brokerage investments, real estate equity, vehicles, and valuable personal property. Liabilities encompass mortgages, student loans, auto loans, credit card balances, and any other outstanding debts.
For a 37-year-old, the composition of net worth matters just as much as the final dollar amount. While a 27-year-old might measure wealth primarily in cash savings and entry-level retirement contributions, a 37-year-old’s balance sheet is typically more complex. It often features real estate equity from a first or second home, larger retirement account balances, and potentially child-rearing expenses or education funds.
Standard financial guidelines, popularized by researchers like Thomas J. Stanley and William D. Danko in The Millionaire Next Door, suggest that a balanced net worth for your age can be estimated using a simple income multiplier formula. While these rules of thumb are helpful starting points, they assume a continuous career path starting in your early twenties. Consequently, individuals with advanced degrees, career pivots, or entrepreneurial ventures may see vastly different trajectories.
Financial Benchmarks and Multipliers at Age 37
To determine how much net worth you should have at 37, financial advisors frequently reference a multiple of your current annual pre-tax household income. By your late thirties, standard financial models suggest aiming for a net worth equal to 2x to 3x your annual income.
If your household earns $80,000 per year, a target net worth between $160,000 and $240,000 aligns with traditional wealth accumulation benchmarks. For a household earning $150,000, the target range shifts to $300,000 to $450,000.
| Annual Household Income | Target Net Worth Range (2x–3x Income) | Primary Wealth Drivers |
|---|---|---|
| $60,000 | $120,000 – $180,000 | Employer retirement match, primary vehicle equity, modest cash savings |
| $90,000 | $180,000 – $270,000 | Growing 401(k)/IRA balances, early home equity, emergency fund |
| $120,000 | $240,000 – $360,000 | Substantial retirement accounts, primary mortgage principal reduction, taxable investments |
| $150,000 | $300,000 – $450,000 | Maximized tax-advantaged accounts, significant home equity, diversified portfolios |
| $200,000+ | $400,000 – $600,000+ | Advanced investment portfolios, multiple real estate holdings, business equity |
It is essential to separate liquid net worth from total net worth. Total net worth includes illiquid assets like your primary residence and personal property, which cannot be easily accessed in an emergency without selling the underlying asset or taking on new debt. Liquid net worth—comprising cash, high-yield savings accounts, and brokerage investments—provides true financial flexibility.
Core Components of a 37-Year-Old’s Balance Sheet
Evaluating your financial health at 37 requires a thorough audit of what makes up your assets and liabilities. Understanding where your money is tied up helps identify structural imbalances in your portfolio.
Retirement Accounts (401(k), 403(b), IRAs)
By age 37, retirement accounts should form a substantial pillar of your net worth. General retirement milestones suggest having the equivalent of one to two times your current salary saved specifically for retirement by this age. If you started saving consistently in your twenties through employer-sponsored plans with matching contributions, compounding interest should be visibly working in your favor.
Real Estate and Home Equity
For many 37-year-olds, real estate represents the largest single asset on the balance sheet, paired with the largest liability (the mortgage). While home equity counts toward net worth, it is important to remember that equity is unrealized until the property is sold or refinanced. Real estate should be valued conservatively, subtracting remaining mortgage balances and estimated selling costs from the current market value.
Taxable Brokerage and Liquid Savings
Beyond retirement accounts, having a healthy cash cushion and taxable investment portfolio is crucial. Financial security at 37 requires an emergency fund covering three to six months of essential living expenses kept in liquid, high-yield accounts. Taxable brokerage accounts offer flexibility for intermediate goals, such as funding a child's education or purchasing a secondary property before retirement age.
High-Interest Consumer Debt
Liabilities can severely depress net worth. While a mortgage is considered "good debt" due to potential asset appreciation, high-interest consumer debt—such as credit cards, personal loans, and high-interest car notes—acts as a direct drag on wealth accumulation. Eliminating toxic debt should take precedence over aggressive investing for anyone falling behind net worth benchmarks.
Factors That Influence Your Net Worth
No two financial journeys are identical. Comparing your net worth blindly to demographic averages or rules of thumb can be misleading because several structural factors heavily influence your financial capacity.
- Geographic Location: The cost of living and regional real estate markets drastically skew net worth figures. A 37-year-old owning a home in a high-cost metropolitan area like San Francisco or New York City will often show a significantly higher net worth purely due to property appreciation compared to someone with identical savings living in a lower-cost rural market.
- Education and Advanced Degrees: Individuals who pursued advanced degrees—such as medicine, law, or doctoral studies—often enter the full-time workforce later, sometimes carrying significant student loan debt well into their thirties. Consequently, their wealth accumulation phase starts later, even if their ultimate earning potential is higher.
- Family Structure and Dependents: Raising children, supporting aging parents, or navigating single-income household dynamics alters cash flow dramatically. Childcare costs, medical expenses, and education savings shift priorities away from rapid asset accumulation during certain years.
- Inheritances and Family Support: Windfalls, family gifts, or the absence of generational debt can accelerate net worth milestones. Recognizing your baseline starting point helps contextualize whether you are building wealth independently or benefiting from external support.
Actionable Steps to Boost Net Worth in Your Late Thirties
If your net worth at 37 falls below standard benchmarks, panic is unnecessary. Your late thirties offer a powerful window for wealth acceleration, driven by peak earning years and the compounding effects of sustained investment.
1. Optimize Your Savings Rate
Consistently saving a high percentage of your income is the most reliable driver of net worth growth. Aim to automate your savings, increasing your contribution rates automatically whenever you receive a raise or bonus. Directing at least 15% to 20% of your gross income toward retirement and long-term investments keeps you on track for financial independence.
2. Ruthlessly Audit and Eliminate High-Interest Debt
Carrying revolving credit card balances at double-digit interest rates sabotages investment returns. Prioritize paying off high-interest liabilities using either the debt avalanche method (targeting highest interest rates first) or the debt snowball method (targeting smallest balances first) to free up monthly cash flow for wealth-building assets.
3. Diversify and Automate Investments
Avoid keeping excessive capital sitting idle in low-interest checking accounts. Once your emergency fund is fully funded, put excess cash to work in low-cost, diversified index funds or exchange-traded funds (ETFs) within tax-advantaged vehicles like Roth IRAs and traditional 401(k)s. Automating these investments removes emotional decision-making from market volatility.
4. Focus on Income Growth
While frugal budgeting is foundational, there is a hard floor on how much you can cut. Focus equal or greater energy on scaling your income. Whether through pursuing promotions, switching employers, developing high-income side skills, or negotiating compensation packages, expanding your top-line revenue accelerates every financial metric.
Frequently Asked Questions
Is a negative net worth at 37 normal?
A negative net worth is common for individuals carrying substantial student loan debt, medical bills, or recent mortgage acquisitions that outweigh their current liquid assets. However, if negative net worth is driven entirely by high-consumer credit card debt, it signals an urgent need to restructure spending habits and prioritize debt paydown.
Should home equity be counted in my net worth?
Yes, home equity is part of your total net worth because your home is an asset and the mortgage is a liability. However, because real estate is illiquid, it is wise to calculate both "total net worth" (including home equity) and "liquid net worth" (excluding home equity) to gauge your true financial agility.
How much should I have saved in retirement by 37?
Financial guidelines generally recommend having between 1x and 2x your current annual salary saved for retirement by age 37. For example, if you earn $100,000 annually, your retirement accounts should ideally hold between $100,000 and $200,000.
Does having a car loan hurt my net worth?
An auto loan negatively impacts your net worth because the loan balance typically exceeds the depreciating value of the vehicle during the first several years of ownership, resulting in negative equity. Financing reliable transportation is sometimes necessary, but luxury cars or over-leveraged auto loans represent significant drags on wealth building.
What is the difference between liquid and total net worth?
Total net worth encompasses everything you own minus everything you owe, including real estate and personal property. Liquid net worth strips away illiquid assets, measuring strictly cash, savings accounts, and readily sellable securities that can be converted to cash within days.
Next Actions for Financial Growth
Assess your current financial standing by calculating your exact net worth today using a reliable spreadsheet or financial tracking tool. Compare your assets and liabilities against standard income multipliers, identify any high-interest debt dragging down your balance sheet, and commit to automating an increased percentage of your monthly income toward diversified, growth-oriented investments.